

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Urethritis Drugs Market to Rise from USD 2,150 Million in 2025 to USD 2,994.85 Million by 2032 at a 4.85% CAGR

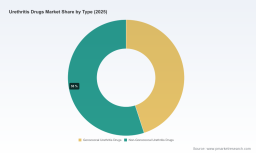
Worldwide Urethritis Drugs Market — Strategic Briefing for 2026 Decision‑Making
PW Consulting’s new market intelligence briefing on the Worldwide Urethritis Drugs Market (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) synthesizes clinical, regulatory, supply‑chain and commercial evidence into a single strategic compass for executives planning activity in 2026. The market reached approximately USD 2.15 billion in 2025 and, given our base assumptions on demand drivers and therapeutic shifts, is projected to expand at a compound annual growth rate (CAGR) of roughly 4.85% across 2026–2032, reaching the low‑to‑mid single‑billion USD range by the close of the forecast period. This briefing explains why that trajectory matters for near‑term choices while deliberately reserving the granular segmentation and provider‑level tables for the full report.
Worldwide Urethritis Drugs Market
Why this report is strategically material for decisions in 2026
-
Timing: 2026 is a pivot year for the urethritis therapeutic landscape. Recent regulatory approvals and late‑stage clinical results are beginning to reconfigure first‑line options for gonococcal disease, while resistance patterns for non‑gonococcal pathogens are pressuring stewardship and diagnostic practice. Our report converts these developments into actionable scenarios.
Worldwide Urethritis Drugs Market -
Portfolio prioritization: With established generics dominating standard regimens and novel oral agents entering the market, biopharma teams must choose between competing investment pathways (incremental reformulation, novel mechanism R&D, or licensing/partnering). The briefing articulates the tradeoffs, timelines and financial sensitivities executives need to decide between 2026 pipeline deployments and commercial launches.
Worldwide Urethritis Drugs Market -
Market access and payer strategy: Public health programs and national STI formularies continue to affect uptake. We map the evidence required to secure inclusion and reimbursement—critical for both originator and generic entrants—so market access teams can operationalize predictable pathways in 2026.
-
Supply‑chain and cost management: Generic competition and established API supply lines have compressed margins in mature segments. Our analysis identifies where upstream risks (API concentration, regulatory inspections, or tariff changes) can materially impact availability and unit economics within a 12–24 month window.
What the PW Consulting report delivers (actionable and operational)
-
Scenario‑based quantitative forecasts calibrated to clinical adoption curves, regulatory timelines and public health procurement patterns (base year 2025, forecast 2026–2032).
-
Commercial playbooks for product classes: go‑to‑market sequencing, pricing reference strategies, tender and formulary submission templates, and stewardship messaging tailored to payers and public health purchasers.
-
Regulatory and clinical pathway mapping, with recommended evidence packages and key opinion leader (KOL) engagement plans to support label expansion or new entry in core markets.
-
Supply‑chain risk heatmaps and sourcing playbooks including alternative API sourcing strategies, contract manufacturing partner (CMO) selection criteria, and contingency planning for capacity constraints.
-
Competitor dossiers and capability assessments that combine product portfolios, recent approvals and late‑stage trial readouts with distribution reach and commercial muscle—designed for M&A diligence or in‑market tactical response.
-
Customizable financial models enabling sensitivity testing by price, volume and adoption speed; scenario outputs provide decision‑ready indicators for licensing, acquisition or divestiture.
Note: this press briefing showcases our methodological depth, but does not disclose the full segmentation tables or provider‑level revenue schedules contained in the paid report. Those granular datasets (by region, treatment type and channel) are accessible via the full deliverable.
Competitive landscape: strategic implications for incumbents and new entrants
The urethritis market exhibits a mix of global originator firms, large generic manufacturers and specialist antibiotic developers. Market concentration is moderate: our CR3 stands in the high‑20s (percent) and CR5 approaches the high‑30s (percent), indicating a competitive market with room for scale plays but also meaningful fragmentation—an important context for M&A strategy and pricing discipline.
-
Innovation leaders: Companies with late‑stage novel antibiotics (for example, new mechanism oral agents) are positioned to reshape clinical practice if they deliver sustained efficacy and favorable safety profiles. Regulatory milestones achieved in 2025—most notably the authorization of a novel oral agent for uncomplicated gonococcal infections—reduce clinical uncertainty and lower the bar for uptake, particularly in settings seeking single‑dose, non‑injectable options.
-
Generics incumbents: Established generic manufacturers underpin global treatment programs through cost‑effective supply of foundational agents used in nongonococcal urethritis. Their supply reliability and formulary inclusion remain decisive competitive advantages, and they are likely to defend share on price and tender execution.
-
Mid‑sized and niche players: Producers of targeted therapies, combination regimens or diagnostics can exploit niche clinical needs created by antimicrobial resistance—especially where resistance‑guided therapy becomes standard practice.
Representative company considerations (high‑level):
-
Pfizer: Maintains presence in standard STI antibiotics through legacy products used in dual therapy regimens; has commercial scale to support stewardship education and formulary efforts.
-
GSK: As the sponsor of a newly approved novel antibiotic, GSK is well‑placed to capture early prescriber interest for single‑dose oral options; its regulatory momentum and commercial reach will determine uptake speed.
-
Teva, Sun Pharma, Cipla, Dr. Reddy’s: Large generic franchises with cost leadership and broad distribution—they form the backbone of public STI treatment programs and will be central to tender outcomes and price‑sensitive markets.
-
AbbVie and Merck: Players with broader anti‑infective portfolios whose strategic moves (portfolio rationalization, licensing) could affect available clinical options and negotiating dynamics with payers.
Recent clinical and regulatory dynamics that will shape 2026 choices
-
Novel approvals and late‑stage trial results: A 2025 regulatory approval for a novel oral agent targeting gonococcal urethritis and positive Phase 3 data for an alternative single‑dose oral antibiotic reported in late 2025 materially change the therapeutic landscape. These developments create opportunities for substitution away from parenteral regimens and may compress hospital/clinic administration volumes.
-
Guideline evolution: Public health guidance remains a critical adoption lever. Current CDC recommendations continue to prioritize doxycycline for nongonococcal urethritis, with azithromycin as an alternative; WHO guidance on managing Neisseria gonorrhoeae has evolved in response to antimicrobial resistance trends. Producers must anticipate and influence guideline revisions through well‑structured evidence generation.
-
Resistance and stewardship: Rising resistance among non‑gonococcal pathogens—including Mycoplasma genitalium—forces a move toward resistance‑guided therapy and diagnostic integration. Firms that pair therapeutic offerings with diagnostic or stewardship services will gain differentiation.
-
Reimbursement realities: Standard antibiotics remain widely included in public health formularies, which keeps price pressure elevated in many regions. Manufacturers pursuing premium positioning for novel agents will need robust health economic arguments and clear value propositions to secure preferential placement.
Strategic playbook: five priority moves for 2026
-
Refine portfolio choices around resistance resilience: Prioritize assets or partners that demonstrate efficacy against resistant strains and can be supported with diagnostic guidance.
-
Secure supply continuity and cost advantage: Lock down diversified API routes, long‑term CMO agreements and regional buffer capacity to mitigate shortages and price volatility.
-
Accelerate evidence generation for guideline inclusion: Invest in pragmatic, real‑world studies and KOL networks to shorten adoption cycles where clinical practice still lags regulatory approval.
-
Design differentiated value propositions for payers: Create targeted health economic models that monetize reductions in clinic visits, injections, or spread of resistant infections—key levers in payer negotiations.
-
Evaluate M&A and licensing opportunistically: Given moderate market concentration, targeted acquisitions or licensing of novel oral agents or rapid diagnostics can rapidly improve competitive position; use our scenario models to stress‑test returns under conservative uptake assumptions.
How PW Consulting supports executive teams in 2026
Our full Worldwide Urethritis Drugs Market report is structured to serve both strategic and operational needs. Deliverables include customizable financial models, competitor benchmarking suites, regulatory and policy trackers, supply‑chain vulnerability matrices, and playbooks for market access and stewardship engagement. For boards and investment committees, we provide deal‑level valuation templates and downside stress scenarios tuned to antimicrobial resistance trajectories.
For decision‑makers preparing budgets, product roadmaps or transaction pipelines in 2026, our analysis turns market uncertainty into prioritized action. To access the full, source‑level segmentation (regional, type and channel breakdowns), provider‑level revenue schedules, and the interactive forecast workbook, please consult the complete PW Consulting Worldwide Urethritis Drugs Market report. That package contains the granular tables and appendices necessary to operationalize the strategies outlined here.
PW Consulting remains available to provide targeted briefings, bespoke modeling, and advisory support to teams seeking to convert the market’s medium‑term growth (CAGR ~4.85% through 2032) and evolving clinical dynamics into defensible, high‑impact decisions in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Urethritis Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com