

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Laboratory Glass Container Market to Rise from USD 4,255.5 Million in 2025 to USD 6,157.6 Million by 2032 at a 5.42% CAGR

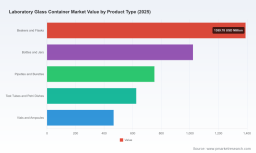
Worldwide Laboratory Glass Container Market: Strategic Imperatives for 2026 Decision‑Makers
PW Consulting's latest market study on the Worldwide Laboratory Glass Container Market (base year 2025; forecast period 2026–2032) equips C‑suite leaders, procurement heads, and private equity sponsors with a decision‑grade evidence base as they set strategy for 2026. The market grew steadily through the historical period (2020–2025), reaching roughly USD 4.26 billion in 2025, and our forecast model projects expansion to approximately USD 6.16 billion by 2032 at a compound annual growth rate (CAGR) of 5.42%. These headline numbers frame a market that is both established and primed for strategic repositioning — a sweet spot for companies who act with data, speed and selective investment.
Worldwide Laboratory Glass Container Market
Why this report matters for 2026 decisions
- Investment prioritization — realign capital allocation between capacity, premium product lines, and adjacent inorganic options based on forward demand scenarios and margin sensitivity.
- Supply‑chain resilience — quantify exposure to raw‑material cost shocks and single‑sourced inputs to design hedging, nearshoring or dual‑sourcing strategies.
- Commercial differentiation — shift from price competition to service and certification premiums for pharma, biotech, and diagnostics customers.
- M&A and portfolio strategy — identify target archetypes and exit valuation corridors informed by concentration metrics and revenue pools.
- Regulatory and sustainability compliance — evaluate product redesign and material choices against tightening pharma and laboratory standards.
What PW Consulting’s report delivers (practical, board‑ready tools)
Our intent is operational impact. The report contains granular deliverables designed to be applied directly in 2026 planning cycles:
Worldwide Laboratory Glass Container Market
- Dynamic demand model (2026–2032) with scenario toggles for end‑market growth, pricing, and substitution effects — exportable to client Excel models.
- Price‑sensitivity and raw‑material stress tests that translate boron and silica cost trajectories into P&L impact at plant and corporate level.
- Supplier and competitor heatmaps mapping production footprint, capacity vintage, and risk scores (labor, logistics, regulatory exposure).
- Commercial playbooks for premiumization, channel segmentation, and contract design for institutional buyers (pharma, diagnostics, academia).
- M&A screening matrix and valuation multipliers calibrated to current concentration metrics and recent strategic deals in the ecosystem.
- Regulatory and sustainability matrices including likely certification timelines and CAPEX implications for switching to alternative materials or upgraded containment systems.
To preserve the strategic advantage for our subscribers we have deliberately withheld point‑by‑point segment tables and granular regional splits in this release. The full data pack and model are available at PW Consulting’s report page.
Worldwide Laboratory Glass Container Market
Market dynamics that will govern outcomes in 2026
Three structural dynamics deserve special attention when planning for 2026:
- End‑market demand elasticity — continued growth in pharmaceutical R&D, biologics manufacturing and clinical diagnostics underpins baseline demand, but pockets of volatility remain linked to capital allocation cycles at large pharma and university budgets.
- Raw‑material pressure and substitution economics — borosilicate glass remains the material of choice for many laboratory applications because of its thermal and chemical resilience. However, rising costs for boron feedstocks and differential pricing versus soda‑lime glass are squeezing margins and driving technical teams to evaluate hybrid solutions, design rationalization and selective polymer substitution for non‑critical use cases.
- Market structure and consolidation — the market exhibits moderate concentration: the top three suppliers capture just under four in ten dollars of industry revenue, while the top five capture a little over half. That concentration pattern creates a competitive tempo in which scale matters for cost leadership, but specialization and IP offset scale in certain niches.
Competitive landscape — players to watch
Our competitive brief profiles legacy leaders, scale challengers and specialist innovators whose strategic choices will define 2026 outcomes.
- Corning Incorporated (Corning, NY) — a global leader whose PYREX branding carries strong trust in thermal and chemical resistance; Corning’s scale and brand equity position it well to compete on pharma‑grade specifications and global distribution.
- DWK Life Sciences (Mainz, Germany) — a portfolio built from historic brands and focused on premium laboratory containers and volumetric ware; consolidation of legacy names gives DWK an advantaged product breadth for research markets.
- Schott AG (Mainz, Germany) — a pioneer in borosilicate glass with deep engineering capability for high‑precision pharmaceutical containers; Schott’s capabilities make it a primary ally for strategic partnerships in pharma primary packaging.
- Borosil Scientific Limited (Mumbai, India) — executing a strategic expansion beyond glassware into vials, filtration and pharma primary packaging through targeted acquisitions and capability expansion — a model for how regional players can move up the value chain.
- BRAND GmbH + Co KG (Wertheim, Germany) — specialist in volumetric and liquid‑handling glassware; excellence in precision measurement makes BRAND relevant where accuracy and calibration matter most.
- Bellco Glass (Vineland, NJ) — a family‑owned innovator focused on engineered systems and cell culture apparatus, offering differentiation through bespoke product engineering and niche process expertise.
- Selected regional manufacturers and innovators (Ace Glass, Witeg, Goel, Adrian, Glassco) — these firms collectively support endpoint diversity and local supply chains; their agility is a counterpoint to the scale playbook and often makes them attractive partners for contract manufacturing or regional sourcing strategies.
Notable 2025–2026 developments underscore strategic direction: Borosil Scientific broadened its portfolio via acquisitions to enter analytical vials and pharma packaging, signaling premiumization and vertical integration moves; distribution deals in the US expanded reach for certain life‑science consumables, illustrating the value of channel partnerships for penetration.
Strategic playbook for 2026 — recommended actions
Below are distilled, prioritized actions for different stakeholders based on our modelling and competitor benchmarking.
- Manufacturers with scale — pursue selective premiumization (pharma containers, certified volumetrics), invest in higher‑margin specialty lines, and use scale to lock preferred boron contracts or vertically integrate where margins justify CAPEX.
- Specialists and regional players — double down on speed to market, customization and contract manufacturing; target partnerships with distributors and pharma formulators to move up the value chain.
- Distributors — leverage expanded logistics and bundled services (certification, traceability, Just‑in‑Time programs) to become an integrated procurement partner rather than a pure reseller.
- Private equity and corporate development — screen targets using PW’s M&A matrix: prioritize bolt‑ons that close technical gaps (vials, filtration) or add critical channel access; value discipline should reflect concentration and margin pressure from raw materials.
- Corporate procurement — deploy our supplier risk‑scoring approach: hedge raw‑material exposure, negotiate indexed contracts linked to boron/silica indices, and pilot consignment models with high‑use customers.
- R&D and product teams — invest in material R&D and hybrid designs where polymer/glass trade‑offs can reduce cost without compromising regulatory compliance for targeted applications.
How boards and executive teams should use the report in 2026
- Use the forecast scenarios in capital‑allocation conversations to justify or pause greenfield capacity investments.
- Leverage the pricing and raw‑material sensitivity analyses during supplier negotiations and to set inventory policies for 12–24 month rolling horizons.
- Inform M&A diligence with our competitor heatmaps and valuation multipliers rather than relying on headline multiples alone.
- Incorporate the regulatory and sustainability matrices into product roadmaps and investor‑facing ESG narratives.
PW Consulting’s Worldwide Laboratory Glass Container Market report is expressly built to convert market intelligence into executable initiatives during 2026 planning cycles. This briefing purposely omits segment‑level tables and regional breakdowns to preserve the operational utility of those datasets; subscribers receive the full data pack, modeling workbook and scenario engine designed for immediate integration into business planning tools.
Next steps
For access to the full report, the downloadable data model and a tailored briefing with our senior industry team, please visit PW Consulting’s report page or contact our research desk. The market’s headline growth and concentration patterns make 2026 an inflection year — firms that translate this report’s insights into concrete supply, commercial and M&A moves will capture disproportionate upside as the market matures.
For detailed analysis of this topic, please visit the official page: Worldwide Laboratory Glass Container Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com