

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Pseudomonas aeruginosa Infection Treatment Market Forecast to Reach USD 2,825.53 Million by 2032 at a 5.51% CAGR

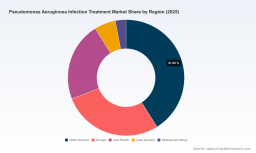
Worldwide Pseudomonas aeruginosa Infection Treatment Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
PW Consulting’s newest market study on Worldwide Pseudomonas aeruginosa Infection Treatment offers a tightly focused, decision-ready intelligence package designed to inform executive choices across product strategy, portfolio prioritization, and commercial operations in 2026. The market has expanded steadily through the early 2020s, rising from an estimated USD 1,484.22 Million in 2020 to USD 1,942.38 Million in 2025, and our model forecasts continued expansion to approximately USD 2,825.53 Million by 2032. The forecast period (2026–2032) embeds a compound annual growth rate (CAGR) of 5.51% and reflects both persistent clinical demand for antipseudomonal agents and an increasingly complex mix of branded innovation, generics supply, and stewardship-driven uptake patterns.
Worldwide Pseudomonas Aeruginosa Infection Treatment Market
Why this report matters for 2026 planning
-
Actionable macroforecast: The report reconciles historical performance (2020–2025) with multiple scenarios through 2032, translating a broad-market CAGR into revenue sensitivities that matter to CFOs and portfolio heads.
Worldwide Pseudomonas Aeruginosa Infection Treatment Market -
Concentration and competitive posture: Market concentration remains meaningful — our CR3 and CR5 metrics indicate that a small group of multinational and generic players capture a material share of value, with downstream implications for access, pricing pressure, and tender dynamics.
Worldwide Pseudomonas Aeruginosa Infection Treatment Market -
Regulatory and guideline inflection points: Recent regulatory decisions and clinical guidance are reshaping prescriber preferences and payer coverage for difficult-to-treat Gram-negative infections; this report synthesizes those developments into commercial and clinical adoption roadmaps.
Market dynamics shaping strategic options
Three structural forces define the Pseudomonas treatment space heading into 2026. First, clinical stewardship and guideline updates continue to steer clinicians toward newer beta-lactam/beta-lactamase inhibitor combinations and novel agents for difficult-to-treat resistant strains — a dynamic that drives premium pricing and selective uptake for differentiated products while constraining volume growth for older, broad-spectrum agents. Second, the generics supply chain remains a stabilizing force: established generic manufacturers sustain baseline access for established therapies and are pivotal in low-margin hospital procurement decisions. Third, real-world evidence (RWE) and post-market data are emerging as pivotal adoption levers for newer molecules, particularly in life-threatening indications where randomized-controlled-trial evidence is limited.
Our study integrates regulatory signals — for example, updates aligning susceptibility testing standards and breakpoint discussions — and reimbursement trends such as society guidance that preferentially recommends certain newer agents for resistant infections. These factors combine to create a market that is both growth-oriented and nuanced: incremental revenue accrues to differentiated, guideline-endorsed therapies, while volume-based segments are exposed to generic erosion and tender competition.
Practical contents of the report (what you will get)
-
Top-down and bottom-up forecasts (2026–2032) including scenario-adjusted revenue curves and sensitivity analyses mapped to policy and resistance trend inflection points.
-
Revenue modeling templates with levers for adoption rates, hospital formulary penetration, tender pricing, and patent/launch timelines to stress-test investment cases.
-
Regulatory and guideline tracker summarizing recent FDA/EMA activity, CLSI standard impacts, and major society recommendations that affect utilization patterns.
-
Commercial playbooks tailored to incumbent multinationals, mid-sized specialty developers, and generic manufacturers — covering pricing strategies, formulary engagement, and field force prioritization.
-
Pipeline and innovation assessment — a concise view of late-stage clinical candidates, mechanism differentiation, and RWE priorities that will determine next-wave adoption.
-
Primary market research outputs: interviews with infectious disease KOLs, hospital pharmacists, procurement officers, and infectious disease program directors that inform realistic adoption curves and purchasing dynamics.
-
Vendor and supply-chain risk mapping for active pharmaceutical ingredients and injectable manufacturing capacity — essential for manufacturers reliant on complex global inputs.
Competitive landscape: what incumbents and challengers must weigh
The market is characterized by a mix of large integrated pharmaceutical firms with established hospital portfolios and agile generics manufacturers that control distribution and price-sensitive channels. Major multinational players maintain strong footholds in hospital and critical care settings through well-known antipseudomonal agents and supportive services, while specialty firms and newer entrants compete on differentiation through novel mechanisms or targeted approvals for limited-treatment populations.
Strategic implications for core player types:
-
Large originators: Preserve premium positioning by investing in RWE generation, securing formulary positioning through outcome-based contracts where feasible, and leveraging hospital education programs that align new agents with stewardship imperatives.
-
Generics and high-volume suppliers: Optimize margin through manufacturing scale and tender execution, while selectively evaluating authorized generics or value-added service bundles to defend against price erosion.
-
Specialty innovators: Prioritize regulatory alignments and post-approval evidence that address real-world effectiveness in resistant phenotypes; targeted geographic launches and managed access programs can accelerate uptake in high-need centers.
Recent developments that change playbooks
Several regulatory, clinical, and commercial events over the last 18 months materially affect how organizations should think about portfolio decisions in 2026. New real-world data presentations for siderophore cephalosporins have strengthened the clinical narrative around utility in carbapenem-resistant contexts. Approvals of novel combination agents have added to the clinician’s toolbox for complicated intra-abdominal and urinary infections involving resistant Gram-negatives. Meanwhile, generic approvals for inhaled antibiotic formulations in cystic fibrosis broaden access but also compress pricing in niche, high-utilization segments.
These events collectively increase the importance of differentiated evidence generation and targeted payer engagement. Our analysis quantifies how these discrete events influence adoption curves, formulary inclusion timelines, and expected revenue trajectories under alternative uptake scenarios.
How to use the report in 2026 strategic planning
-
Portfolio prioritization: Use our scenario models to rank candidate assets by expected net present value under multiple resistance and reimbursement scenarios.
-
Launch sequencing: Apply our regional and hospital-level adoption templates to design staging strategies that balance revenue potential with evidence-generation costs.
-
Commercial resource allocation: Recalibrate field force deployment and hospital account plans based on the report’s segmentation of high-opportunity clinical settings and formulary gatekeepers.
-
Risk mitigation: Leverage the supply-chain and API risk maps to hedge manufacturing exposures and secure continuity for injectable antibiotics in high-demand periods.
Data provenance and methodological transparency
The report combines primary interviews, proprietary hospital utilization datasets, public regulatory filings, and surveillance/RWE inputs to produce an evidence-backed forecast. We triangulate multiple data sources to deliver robust topline forecasts and provide clients with the underlying modeling spreadsheets to run bespoke sensitivity tests. To preserve competitive advantage for our subscribers, granular sub-segment tables (detailed regional shares, application-specific line items, and product-level price curves) are intentionally reserved for the full report package.
Concluding recommendation
For executives making resource allocation and product strategy decisions in 2026, the choice is no longer between “innovate” or “defend” — it is about sequencing innovation, evidence, and commercialization in a resistance-aware, stewardship-constrained ecosystem. PW Consulting’s Worldwide Pseudomonas aeruginosa Infection Treatment Market report equips leaders with a transparent macro view (historical growth from USD 1,484.22 Million in 2020 to USD 1,942.38 Million in 2025; forecast to roughly USD 2,825.53 Million by 2032 at a 5.51% CAGR), a calibrated assessment of market concentration dynamics, and ready-to-deploy commercial playbooks that translate insights into 90–180 day action plans.
To access the full analytical depth — including the withheld sub-segment data, granular competitive benchmarking, and the downloadable forecasting models — please visit our report landing page or contact PW Consulting’s industry team for a briefing and a private demonstration.
For detailed analysis of this topic, please visit the official page: Worldwide Pseudomonas Aeruginosa Infection Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com