

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Augmented Bone Graft Market Reaches USD 4,137.15 Million in 2025; Poised for 6.18% CAGR from 2026–2032

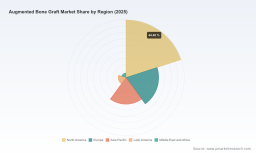
Worldwide Augmented Bone Graft Market — Strategic Insights for 2026 Decision-Making
PW Consulting’s latest market research, Worldwide Augmented Bone Graft Market (base year 2025; historical 2020–2025; forecast 2026–2032), delivers a decision-grade intelligence pack designed to shape boardroom choices and commercial plans in 2026. Our analysis shows the market reached USD 4,137.15 Million in 2025 and is modeled to expand at a compound annual growth rate (CAGR) of 6.18% over the 2026–2032 forecast window, with implied upside and downside scenarios mapped to clinical adoption, regulatory shifts, and reimbursement dynamics. The study synthesizes company reporting, procedure-volume trends, pricing models, and primary interviews to produce action-oriented recommendations for medtech manufacturers, private equity investors, and hospital systems.
Worldwide Augmented Bone Graft Market
Why this report matters for 2026
-
Timing for portfolio choices: With mid-single-digit CAGR and sizable headline growth through 2032, companies must decide whether to accelerate investment in biologics, double down on synthetic substitutes, or pursue hybrid augmentation strategies that blend scaffold and growth-factor technology.
Worldwide Augmented Bone Graft Market -
Evidence-driven commercialization: Clinical evidence and hospital contracting are the primary levers separating winners from also-rans. The report identifies which clinical endpoints (fusion rates, time-to-union, complication reduction) drive purchasing committees and how to structure clinical programs to shorten the path to adoption.
Worldwide Augmented Bone Graft Market -
M&A and partnership triage: Fragmented supply bases and an industry where the top three vendors capture a meaningful share (CR3) and the top five a larger majority (CR5) create distinct opportunities for bolt-on acquisitions and distribution alliances. Our intelligence highlights where scale matters versus where clinical differentiation trumps scale.
-
Regulatory and reimbursement readiness: The space sits at the intersection of device regulation and biologic safety considerations. Preparing 510(k) pathways, mapping country-specific reimbursement codes, and pre-empting payer objections are all necessary 2026 preparations detailed in the report.
Report contents — what you get
-
Market sizing and validated forecast model (2020–2032): A bottom‑up revenue model tied to procedure volumes, device ASPs, and expected uptake curves. The report provides a downloadable Excel model with scenario toggles for adoption rates, pricing pressure, and geographic expansion assumptions.
-
Segmentation framework (by product type, application, and region): Deep qualitative analysis of each segment’s clinical value proposition and competitive dynamics. Note: this press summary intentionally omits granular segment revenue tables — full splits and region-by-application cells are available on the report portal.
-
Clinical and commercial evidence mapping: Comparative tables summarizing pivotal and post-market studies, endpoints that move hospital formularies, and design considerations to accelerate reimbursement approval.
-
Competitive landscape and capability audit: Company-level profiles, distribution strategies, manufacturing footprints, and near-term catalysts. We assess R&D pipelines, partnership footprints, and contract wins that move the needle commercially.
-
Supply chain and cost model: Unit‑cost drivers, raw-material sensitivity analysis, and critical control points (e.g., sterilization and logistics). We include procurement reference points to stress-test margin scenarios.
-
Regulatory and reimbursement playbooks: Practical checklists for 510(k) planning, payer dossier construction, and engagement timelines for major public payers and hospital systems.
-
Strategic options and M&A screening framework: Priority target criteria, valuation multiples observed in the last 24 months, and diligence templates for rapid target triage.
Competitive landscape — players to watch and strategic positioning
The market displays a concentrated but competitive structure: the top three vendors control a near-majority share while the top five capture roughly two-thirds of market value. Several incumbent medtech and biologics companies are jockeying for position through differentiated technology, distribution scale, or clinical data.
-
Medtronic (Dublin) remains a market leader with a clinically proven biologic platform leveraging recombinant BMP-2 for spine and trauma indications; recent multi-year supply agreements with major hospital systems strengthen its procurement advantage.
-
Stryker (Portage, MI) competes strongly on synthetic, bioactive scaffolds and continues to refine composites that balance handling and osteoconductivity for orthopedic voids.
-
Zimmer Biomet (Warsaw, IN) sustains a diversified portfolio with synthetic matrices and cancellous chips, focusing on surgeon ergonomics and operative efficiencies as purchase drivers.
-
Orthofix Medical (Lewisville, TX) has demonstrated clinical signal strength in recent studies for DBM products and is expanding regulatory footprints in Asia, which supports a differentiated allograft/DBM play.
-
Mid-sized specialists, including Integra, Globus, DePuy Synthes (J&J), and several allograft providers, leverage niche clinical evidence, supply relationships, or biologic enhancements to secure tendon-to-bone and spinal niches.
-
Smaller innovators and allograft networks are attractive targets for roll-up strategies, especially where viable-cell allografts or peptide-augmented implants present near-term commercialization catalysts.
Recent industry developments underscore competitive dynamics: new clinical readouts demonstrating high fusion rates, distribution agreements that expand reach in spine centers, and targeted regulatory clearances for synthetic products in Asian markets. These moves accelerate consolidation and raise the bar for market entry.
Strategic implications and recommended actions for 2026
-
Prioritize clinical evidence aligned to hospital procurement metrics. Early stage R&D should focus on endpoints that reduce OR time, lower reoperation rates, or shorten length-of-stay — variables that translate into faster formulary uptake.
-
Lock down supply chain quality controls. For allograft and biologic providers, sterilization practices and traceability are not optional. Adhering to industry sterilization standards and documenting process control (including gamma-irradiation parameters where applicable) is mandatory for institutional buyers.
-
Design a hybrid commercialization strategy. Where feasible, pair product launches with distribution partnerships to accelerate hospital access while building clinical evidence via targeted investigator-initiated studies.
-
Engage payers early. Reimbursement is a practical gatekeeper; developing CPT/CMS-aligned economic dossiers and demonstrating cost-effectiveness in relevant DRGs materially shortens procurement cycles.
-
Use M&A to secure scarce capabilities. If clinical differentiation is time-consuming, consider bolt-on acquisitions to obtain manufacturing scale, proprietary biologics, or access to high-value hospital networks.
Methodology, robustness, and how to use the forecast
PW Consulting’s forecast synthesizes historical revenue tracking (2020–2025), device and biologic shipment data, procedure volumes, and price trends. We apply a blended approach: bottom‑up unit modeling for product classes combined with top‑down reconciliation to company financial disclosures. Scenario and sensitivity analyses allow users to test assumptions — surgical adoption curves, price erosion, and regulatory delays. The report includes guidance on which inputs are most sensitive to valuation (clinical readouts, ASP changes, and payer coverage) so teams can prioritize data collection.
Appendix — selected industry dynamics (high-signal reference points)
-
Regulatory: In the U.S., many bone graft substitutes are regulated as Class II devices and typically follow 510(k) premarket notification pathways for dental and orthopedic indications. This affects development timelines and evidence requirements.
-
Reimbursement: Established procedure codes and DRG frameworks determine hospital revenue capture; for example, widely used billing codes and average reimbursement ranges significantly influence hospital willingness to adopt premium grafts.
-
Sterilization and quality: Allograft sterility control (including validated irradiation doses and documented sterility assurance levels) is a procurement prerequisite for major health systems.
-
Material cost drivers: Key synthetic components (such as beta‑tricalcium phosphate granules) display meaningful price sensitivity at scale and should be modeled in unit-cost scenarios when assessing margin profiles.
-
Safety considerations: Certain growth‑factor products carry specific warnings that affect label strategy and surgeon adoption; risk management and appropriate clinical indications remain essential to commercialization plans.
How to access the full intelligence
This communiqué is a strategic preview intended to guide 2026 planning. PW Consulting’s full report contains the full segmentation matrix, downloadable models, company-level financial estimates, and granular regional and application splits that are intentionally omitted here to preserve the report’s tactical value. For access to the complete dataset, scenario models, and bespoke advisory engagements tailored to your strategic objectives, please visit our report portal or contact our client services team to schedule a deliberative briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Augmented Bone Graft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com