

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Thermoplastic-sheathed Cable Market to Rise from USD 52,150 Million in 2025 to USD 79,981 Million by 2032 at a 6.29% CAGR—Asia Pacific Leads with USD 23,476.6M

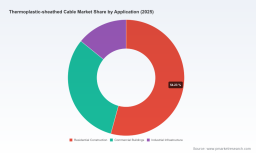
Worldwide Thermoplastic-Sheathed Cable Market: Strategic Signals for 2026 Decision-Making
PW Consulting’s newest market brief on the Worldwide Thermoplastic-Sheathed (TPS) Cable market synthesizes five years of historical tracking (2020–2025) with a seven‑year forecast (2026–2032) to translate industry dynamics into actionable strategies for executives, investors, and procurement leaders planning for 2026 and beyond. Our core finding: the TPS market, valued at roughly USD 52.15 billion in 2025, is set to expand at a compound annual growth rate (CAGR) of 6.29% through 2032, reaching approximately USD 79.98 billion under the base forecast. That topline growth masks critical operational, regulatory, and supply‑chain inflections that will determine winners and laggards in the coming planning cycle.
Worldwide Thermoplastic-sheathed Cable Market
Why this report matters for 2026 planning
-
Timing. 2026 is the pivot year when near‑term recovery investments transition into medium‑term infrastructure and retrofit programs driven by energy efficiency, grid modernization, and data center expansion. Capital allocation and sourcing choices made in 2026 will establish cost baselines and contractual footprints through the latter half of the decade.
Worldwide Thermoplastic-sheathed Cable Market -
Risk concentration. Despite a sizeable global market, the TPS space remains relatively fragmented (CR3 ≈ 18.5%, CR5 ≈ 24.8%), creating both margin pressure and M&A opportunities. Fragmentation means differentiated product, supply assurance, and regulatory compliance will be decisive competitive levers.
Worldwide Thermoplastic-sheathed Cable Market -
Regulatory inflection. Revised fire safety and environmental requirements introduced since 2024–2025 materially change product specifications and qualification lead times. Procurement teams need to pre‑position certifications in 2026 to avoid late‑cycle specification failures.
What the report delivers (practical content overview)
-
Top‑down market sizing and scenario forecasts (2026–2032) with sensitivity analysis around raw material volatility and regulatory adoption rates.
-
A regulatory & standards matrix detailing changes to IEC and regional standards (including recent updates affecting flame retardancy and performance), certification timelines, and cost implications for qualifying new compound formulations.
-
Raw‑material cost modeling (PVC resin and alternatives) with pass‑through analysis and hedging playbooks calibrated to recent price points and supply trends.
-
Supplier benchmarking and a proprietary scoring framework covering production footprint, standards compliance, product breadth, and route‑to‑market strength.
-
Commercial playbooks for OEMs, distributors, and EPCs: product positioning for low‑smoke zero‑halogen (LSZH) offerings, contract design for tariff exposure, and channel strategies for emerging demand corridors.
-
M&A and partnership heat map identifying targets for bolt‑on scale, specialty product acquisition, or geographic footprint expansion—plus integration risk checklists.
-
CapEx and working capital guide for 2026 prioritization: recommended timing for capacity expansion, tooling changes to accommodate new compounding requirements, and inventory strategies under escalating tariff and logistics uncertainty.
Key market dynamics shaping 2026 choices
-
Standards & safety upgrades. The 2024 IEC amendments tightened flame‑retardancy performance for thermoplastic‑insulated products; complementary national standards (for example, Australia’s AS/NZS updates) have shortened product replacement cycles in certain markets. These regulatory shifts are prompting firms to revise formulations, re‑qualify product lines, and adjust pricing—actions that carry lead times extending well into 2026.
-
Demand pull from energy efficiency and renewables. Policy pushes for low‑emission buildings and grid‑edge electrification are accelerating demand for higher‑performance TPS variants (including LSZH grades). EU policy measures have been a notable accelerant, raising structural demand in the medium term.
-
Raw material exposure. PVC resin remains the dominant sheathing feedstock. Recent market observations show PVC pricing stability at roughly USD 1,200/metric ton in late 2025 in Asia, but feedstock risk persists due to petrochemical cycles. Procurement strategies that combine index‑linked contracts, regional sourcing, and selective substitution pathways will be essential to control margin erosion in 2026.
-
Trade and sourcing shifts. Tariff actions implemented in 2025—most prominently higher duties on Chinese cable imports in key markets—have already re‑routed sourcing flows toward Mexico and Southeast Asia. Manufacturers and buyers must evaluate near‑shoring and dual‑sourcing strategies during 2026 contracting cycles to mitigate tariff and lead‑time risks.
-
Digitalization and product‑service models. Data center operators and large EPC contractors increasingly demand traceability, logistics transparency, and performance warranties. Smart labelling, inventory-as-a-service, and predictive maintenance contracts for cable assets are nascent commercial vectors that will mature through 2026–2028.
Competitive landscape: how leading players are positioning
The TPS supplier universe includes well‑established global manufacturers and a broad set of regional specialists. Core global participants we analyze in the report include:
-
Prysmian Group (Milan, Italy) — https://www.prysmiangroup.com
-
Nexans (Paris, France) — https://www.nexans.com
-
Southwire Company (Carrollton, USA) — https://www.southwire.com
-
LS Cable & System (Seoul, South Korea) — https://www.lscns.com
-
Sumitomo Electric Industries (Osaka, Japan) — https://sumitomoelectric.com
-
Furukawa Electric (Tokyo, Japan) — https://www.furukawa.co.jp
-
NKT A/S (Brøndby, Denmark) — https://www.nkt.com
-
Leoni AG (Nuremberg, Germany) — https://www.leoni.com
-
Belden Inc. (St. Louis, USA) — https://www.belden.com
-
Lapp Group (Stuttgart, Germany) — https://www.lappgroup.com
Across these incumbents we observe three distinct strategic postures relevant to 2026 decision‑makers:
-
Product premiumization and standards leadership — firms investing in LSZH, enhanced fire performance, and renewables‑specific cable lines to capture specification‑driven spend.
-
Manufacturing footprint optimization — players redirecting capacity to tariff‑advantaged locations and closer to major infrastructure projects to reduce logistics risk and lead times.
-
Service differentiation — suppliers layering digital traceability, certification bundles, and extended warranties to protect margins in a commoditized core market.
Recent market activity illustrates these trends: Prysmian highlighted renewable‑focused low‑voltage TPS innovations at a major 2025 trade exhibition; Nexans introduced higher fire‑resistant thermoplastic grades for buildings; Southwire secured UL recertification for a new SIMpull family; LS Cable & System won project supply awards in the data center sector. These moves underline how product specification and certification cycles will be a gating factor for access to sizable projects in 2026.
Strategic imperatives for executives planning in 2026
-
Prioritize certification roadmaps now. Certification lead times are material—delayed qualifications translate directly into lost bids. Allocate engineering and commercial resources in 2026 to complete IEC and national approvals for any product intended for regulated building or infrastructure programs.
-
Lock in feedstock risk mitigations. Use the 2026 contracting window to implement outright purchase agreements, buy‑through options, or blended sourcing across regions to smooth PVC exposure and avoid single‑point supply shocks.
-
Design tariff‑resilient supply networks. Revisit supplier matrices and escalate dual‑sourcing with production located in tariff‑advantaged jurisdictions. Where relocation is infeasible, build cost models that internalize tariff scenarios and transport volatility.
-
Invest selectively in product adjacencies. Demand for LSZH and other enhanced performance compounds is widening—targeted R&D and co‑development agreements with compound suppliers can accelerate time to market with limited CapEx.
-
Explore consolidation with discipline. Given the fragmented market structure, attractive bolt‑on targets exist for firms seeking share and technical breadth. M&A models should stress test integration assumptions on standards, quality systems, and geographic licensing.
What PW Consulting recommends next
-
For manufacturers: produce a prioritized 24‑month certification and capacity plan tied to your five largest target tenders for 2026–2027; quantify margin impact of feedstock scenarios and revise pricing clauses accordingly.
-
For distributors and OEMs: require supplier traceability and certification SLAs in new RFPs; evaluate inventory‑as‑a‑service pilots for critical sites.
-
For investors: focus diligence on companies with defensible technical IP in LSZH and those with flexible, tariff‑resilient manufacturing footprints; demand granular raw‑material sensitivity analyses as part of any valuation.
PW Consulting’s Worldwide Thermoplastic‑sheathed Cable Market report provides the quantitative backbone and the decision tools to convert these imperatives into executable plans. The public summary establishes the strategic thesis; our full report contains the granular regional, application and product‑type breakdowns, supplier scorecards, and modelled scenarios that procurement, strategy, and M&A teams will need to finalize 2026 budgets and bids.
How to use this insight
-
Treat the 2026 planning cycle as the last window to reposition contracts and qualification cycles before the next phase of capacity investments comes online.
-
Use the report’s scenario models to stress test contracts for tariff shocks, PVC feedstock surges, and accelerated regulatory adoption of LSZH specifications.
-
Engage PW Consulting for a tailored workshop to convert the report’s findings into a 90‑day action plan that aligns procurement, product development, and commercial teams.
For access to the full set of regional and application‑level tables, vendor scorecards, and downloadable modeling tools, please consult the full report landing page. The data‑rich appendices and the executable playbooks are intentionally available there to support immediate operationalization in 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Worldwide Thermoplastic-sheathed Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com