

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Oilfield Traveling Block Market Poised to Expand at 5% CAGR from USD 672.37 Million in 2025 to USD 946.09 Million by 2032 — North America and 250–500T Units Lead

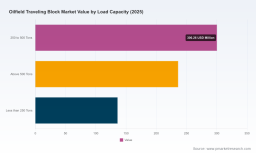
Worldwide Oilfield Traveling Block Market: Strategic Outlook for 2026 Decision‑Making
PW Consulting’s latest market research — the Worldwide Oilfield Traveling Block Market report (base year 2025, historical coverage 2020–2025, forecast 2026–2032) — delivers the actionable intelligence executive teams will need to set winning strategies in 2026. Our market model shows the global market reached an estimated USD 672.37 Million in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 5.0% through 2032, reaching approximately USD 946.09 Million by the end of the forecast horizon. This press overview summarizes the strategic implications, competitive landscape, and practical levers the full report explores in depth — while preserving the proprietary sub‑segment analytics available only in the full publication.
Worldwide Oilfield Traveling Block Market
Why this market matters now
Traveling blocks are foundational components of hoisting systems and are therefore a critical nexus between rig utilization, safety and lifecycle cost. Three converging dynamics make 2026 a pivotal year to revisit strategy:
Worldwide Oilfield Traveling Block Market
-
Demand rebound and rig activity: The global rotary rig count has strengthened, driving new and replacement demand for hoisting equipment and related retrofit opportunities. Operators and rig owners are prioritizing reliability and digital enablement as utilization improves.
Worldwide Oilfield Traveling Block Market -
Input cost and supply pressure: High‑strength alloy steel — a core raw material — experienced meaningful price inflation recently, and supply chain tightness has driven lead‑time sensitivity for key components. Parallel increases in hot‑rolled coil deliveries to the energy sector have helped, but procurement risk has become more strategic than transactional.
-
Regulatory and technical uplift: Modern API specifications now require enhanced load monitoring and telemetry for larger hoisting components, shifting value toward systems integrating sensing, analytics, and compliance assurance rather than commodity metalwork alone.
What the PW Consulting report delivers (practical contents)
Our research is purpose-built for executives who must make capital allocation, sourcing and M&A decisions in 2026. Key deliverables include:
-
Demand model and scenario analysis — granular vintage and replacement schedules driven by rig count scenarios, multiple oil‑price paths and differential offshore/onshore utilization dynamics. The model is designed to be used as a decision tool for CAPEX timing and inventory planning.
-
Cost‑to‑serve and procurement playbook — material cost sensitivities, supplier lead‑time mapping, and negotiation levers to protect margins in an inflationary raw‑material environment.
-
Technology and compliance roadmap — assessment of sensing, load‑monitoring, and integration pathways to meet current API requirements and to monetize predictive maintenance capabilities.
-
Competitive benchmarking and supplier scorecards — a repeatable framework for evaluating OEMs and regional suppliers across technical capability, quality certification, service footprint and aftermarket economics.
-
M&A and partnership playbook — prioritized targets, synergy matrices, and integration red flags for both bolt‑on consolidation and capability acquisitions.
-
Risk matrix and contingency plans — scenarios for raw material shocks, regulatory tightening, and offshore project deferrals, with prescriptive mitigation steps.
How the market will shape enterprise choices in 2026
For OEMs and tier‑one suppliers, 2026 is a year to lock in margin expansion through a combination of product premiumization and operational excellence. The dual pressures of higher input costs and elevated demand mean wins will go to manufacturers that can:
-
Differentiate via systems integration — coupling traditional mechanical strength with load sensing, connectivity and service contracts;
-
Shorten lead times through dual‑sourcing and closer raw‑material partnerships; and
-
Deploy targeted price adjustments underpinned by demonstrable cost transparency and guaranteed performance SLAs.
For operators and E&P companies, the imperative is to convert hoisting systems from a capital expense into a predictable reliability program. That means prioritizing lifecycle cost analysis, negotiating outcome‑based maintenance contracts, and accelerating retrofits where digital monitoring reduces unscheduled downtime.
Competitive landscape: who to watch and why
The market concentration metrics indicate a moderately consolidated market (top‑three firms account for a substantial share while the top five further extend reach), creating both competitive tension and partnership opportunities. Our full‑length profiles and supplier scorecards dig deeper; highlights below summarize strategic positions of leading players covered in the study.
-
NOV Inc. (Houston, TX, USA) — As an established provider across drilling equipment categories, NOV has moved to integrate advanced drawworks and smart hoisting components. Their recent product showcases at major trade events reflect a push to bundle hardware with monitoring and service platforms. Strategy implication: NOV is positioning to compete on total cost of ownership and digital differentiation; counter‑strategies for rivals include niche specialization and faster aftermarket response.
-
Bentec GmbH (Bad Bentheim, Germany) — Bentec’s emphasis on modular rig design and compliance with international standards makes it an attractive partner for integrated rig projects. Their trade‑show visibility underscores a focus on high‑spec installations. Strategy implication: Bentec is a natural partner for EPCs pursuing turnkey modular rigs; OEMs should anticipate bundling pressure on large tenders.
-
Honghua Group Limited (Chengdu, China) — A major exporter of land and offshore rig equipment, Honghua continues to compete on scale and price, while upgrading quality certifications to expand into higher‑value segments. Strategy implication: Expect continued pricing discipline in certain segments; western OEMs can defend by emphasizing lifecycle services and compliance credentials.
-
RG Petro‑Machinery (Yangzhou, China) — Specialist hoisting and drawworks supplier with a focused portfolio; RG Petro’s operational focus on API compliance and regional aftermarket support gives it a cost‑competitive service position. Strategy implication: For buyers prioritizing cost and regional service, RG Petro will remain a frequent choice; OEMs should compete on integrated digital service and faster engineering change response.
-
BOMCO (Baoji, Shaanxi, China) — Backed by major national operators, BOMCO blends heavy‑duty capability with access to large domestic projects and harsh‑environment credentials. Strategy implication: BOMCO’s state‑linked positioning may accelerate participation in national projects and certain international contracts where financing and local content weigh heavily.
Recent product launches and trade show activity across these players indicate two important trends: (1) premiumization around intelligent drawworks and integrated traveling blocks, and (2) renewed competition for aftermarket service and retrofits as operators seek to extend asset life while meeting regulatory expectations.
Priority plays for different decision‑makers in 2026
-
Operators / Rig Owners: Prioritize retrofitting load monitoring to bring legacy rigs into compliance and to capture early reliability gains. Adopt outcome‑based contracting to shift maintenance risk to suppliers while incentivizing performance.
-
OEMs and Equipment Suppliers: Invest in modular designs and systems integration capabilities. Protect margins by locking raw‑material supply agreements and by offering tiered service contracts that monetize digital data.
-
Investors and M&A Teams: Target bolt‑on acquisitions that fill missing capabilities — notably digital load monitoring, aftermarket logistics, or localized fabrication footprints. Use scenario stress‑testing from our demand model to size acquisition valuations.
-
Procurement and Supply Chain Leaders: Move from spot buys to strategic partnerships with steel suppliers; deploy hedging and just‑in‑time buffers calibrated to rig project pipelines to limit inventory drag while preserving delivery reliability.
Operational roadmap: a 100‑day plan for 2026
-
Days 0–30: Reconcile fleet inventories and map compliance exposure against current API requirements; quantify retrofit candidate list.
-
Days 30–60: Run cost‑sensitivity workshops with procurement and engineering using scenario inputs from the PW demand model; secure strategic raw‑material commitments where economically justified.
-
Days 60–100: Execute pilot retrofit with integrated load monitoring on representative rigs; negotiate an outcome‑based service contract with an OEM or specialist supplier to validate OPEX improvements.
Why access the full PW Consulting report
This press overview is designed to reveal the strategic value of the research without compromising proprietary datasets. The full Worldwide Oilfield Traveling Block Market report includes:
-
Complete time‑series demand and revenue model (historical and forecast), including downloadable spreadsheets to stress‑test your scenarios;
-
Supplier scorecards with detailed technical and commercial metrics used to rank partners and acquisition targets;
-
Regionally differentiated CAPEX timelines and retrofit prioritization matrices (note: we intentionally omit sub‑segment numbers here — these are included exclusively in the full report);
-
Step‑by‑step procurement playbook and contract templates for outcome‑based maintenance arrangements;
-
Interactive executive dashboards that allow you to visualize market sensitivity to rig counts, raw‑material price swings and regulatory adoption curves.
Conclusion
In 2026, decisions about traveling block procurement, retrofit prioritization and supplier partnerships will have an outsized impact on field reliability and capital efficiency. PW Consulting’s analysis synthesizes market sizing, supplier benchmarking, technology trends and regulatory drivers into a pragmatic, executable set of choices. If your 2026 agenda includes optimizing hoisting reliability, protecting margins against steel price volatility, or exploring acquisitions to close capability gaps, our full report is the operational playbook you will need.
Visit PW Consulting to access the full Worldwide Oilfield Traveling Block Market report, including proprietary segment datasets, model access and supplier scorecards that are intentionally withheld from this overview to preserve client value.
For detailed analysis of this topic, please visit the official page: Worldwide Oilfield Traveling Block Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com