

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
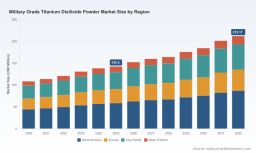
PW Consulting: Worldwide Military-Grade Titanium Disilicide Powder Market to Rise from USD 142.5 Million in 2025 to USD 212.17 Million by 2032 at a 5.85% CAGR — Micron Grade & Infrared Decoys Lead; Top 3 Firms Hold 64.5% (CR5: 82.2%)

Worldwide Military Grade Titanium Disilicide Powder Market — Strategic Preview for 2026 Decision-Makers
PW Consulting is pleased to release a strategic preview of our forthcoming Worldwide Military Grade Titanium Disilicide (TiSi2) Powder Market report (base year: 2025; historical coverage: 2020–2025; forecast window: 2026–2032). This briefing distills the report’s most consequential insights for corporate leaders, procurement strategists, and defense supply‑chain planners who must set direction in 2026. Consider this a trailer: we demonstrate methodology, market trajectory, supply‑chain stress points, and competitor posture to inform immediate strategy — while preserving the granular segmentation and proprietary forecasts that drive critical decisions for readers who access the full report.
Worldwide Military Grade Titanium Disilicide Powder Market
Executive summary: why this material matters in 2026
Titanium disilicide, in its military grade forms, is increasingly central to defense applications where high temperature tolerance, low resistivity, and long‑term performance under stress are required — from infrared decoys and pyrotechnics to high‑temperature coatings and microelectronics. Our analysis shows a steady and resilient market expansion: the market expanded from a modest base in 2020 through 2025 and is projected to continue its upward trajectory through 2032 at a compound annual growth rate (CAGR) of 5.85%. In dollar terms (USD Million), the market moved from the low hundreds in 2020 to approximately 142.5 Million in 2025 and is forecast to reach the low hundreds by 2032 under our central scenario.
Worldwide Military Grade Titanium Disilicide Powder Market
For executives making 2026 bets — on capacity, supplier integration, or product development — three strategic truths emerge from our work: (1) demand durability tied to defense modernization and aerospace renewals; (2) a constrained upstream linked to titanium and silicon feedstocks; and (3) a competitive landscape that is concentrated but evolving due to partnerships and capacity moves. These dynamics combine to make 2026 a pivotal year for cementing supplier relationships, locking in feedstock access, and selectively investing in production scale and certification.
Worldwide Military Grade Titanium Disilicide Powder Market
Market trajectory and what the headline numbers mean
Our base‑case projection — reflecting current procurement plans, rates of technology refresh in defense electronics, and thermal‑management demands in aerospace — yields a steady CAGR of 5.85% across 2026–2032. That pace implies meaningful but manageable growth: enough to justify incremental capacity investments and strategic M&A for mid‑tier suppliers, but not so explosive as to rapidly commoditize differentiated high‑purity and mil‑spec offerings. The market’s growth profile supports the economic rationale for capital projects that prioritize high‑purity, low‑oxygen production routes and particle‑size control (sub‑micron and nano grades) that serve military microelectronics and specialized coatings.
Importantly, our modelling includes scenario bands that account for defense spending shocks, downstream substitution risks, and raw‑material price volatility. Those scenarios are central to the full report and underpin recommended timing for investments and contracting strategies.
Supply chain and cost drivers: the upstream is the strategic chokepoint
Two upstream facts dominate economics and risk: titanium sponge and silicon metal. Titanium sponge is a foundational feedstock for titanium‑based compounds, and our analysis highlights its projected market scale and supply tightness into 2026. Silicon metal markets are large and exposed to energy‑intensive smelting cycles; recent industry assessments show the silicon space at multi‑billion dollar scale and modest near‑term growth. Critically, metallurgical‑grade silicon price swings — driven by energy costs and capacity utilization in smelting — can create 30–40% annual volatility in feedstock costs, a material input into TiSi2 production economics.
For procurement and operations teams, the implication is clear: securing long‑dated supply agreements for titanium sponge and silicon metal, or verticalizing feedstock processing where feasible, materially reduces margin exposure. Hedging strategies, strategic stockpiles calibrated to defense contract cycles, and co‑investment with feedstock suppliers are defenses against the asymmetric risk profile of the upstream.
Regulatory and quality constraints that drive supplier selection
Military‑grade TiSi2 is not a commodity. MIL‑SPEC compliance, export control regimes, and traceability requirements elevate the certification and documentation burden for every tier of the supply chain. Export controls and national security screening mean that supplier nationality, plant location, and validated process controls carry outsized contract value. For original equipment manufacturers (OEMs) and prime contractors, supplier risk assessments must now embed export‑control pathways and alternate‑source contingencies as standard operating procedures.
Competitive landscape — concentrated with targeted moves
The market exhibits meaningful concentration: the top three firms account for a substantial share of global supply, and the top five push that concentration considerably higher. This structure creates both stability and risk: established suppliers offer capacity and validated mil‑spec product lines, but the high concentration also raises the prospect of supply shocks if any leading producer reprioritizes capacity.
- American Elements (Los Angeles) — recognized for ultra‑high‑purity and mil‑spec offerings across submicron and nanopowder grades; a go‑to for defense customers requiring certified traceability.
- Stanford Advanced Materials (Lake Forest) — focused on microelectronics and high‑temperature aerospace applications; positions itself on purity and form factor control.
- Nanochemazone (Edmonton) — notable for customizable particle sizes and an explicit mil‑spec portfolio, attractive to specialists that require tailored material specs for advanced weapon systems.
- H.C. Starck Solutions (Newton) — part of a larger group with recent capacity expansions to serve semiconductor and high‑performance electronics demand — a strategic supplier for defense electronics producers.
- Treibacher Industrie AG (Althofen) — active in partnership development with semiconductor houses; a firm to watch for cross‑industry collaboration that could lift performance standards.
- Princeton Powder (USA) — offering low‑oxygen, high‑purity microns powder alternatives; a niche supplier for oxygen‑sensitive process chains.
Recent market activity reinforces this view: strategic partnerships between high‑purity suppliers and semiconductor manufacturers, product launches addressing stringent microelectronics needs, and capacity expansions announced by leading producers. These moves are the proximate drivers of competitive intensity in 2026. Executives should monitor partnership pipelines and capacity build plans as leading indicators of margin pressure and opportunity.
Strategic implications and recommended 2026 actions
- Prioritize supplier qualification and dual‑sourcing for mil‑spec grades. Given concentration and regulatory friction, dual‑sourcing mitigates single‑point failures and supports resilience in defense programs.
- Negotiate feedstock contracts with clauses keyed to energy cost indices. Silicon price volatility is non‑trivial; indexing or formula pricing can materially protect margins.
- Invest selectively in process capabilities that differentiate product value: low‑oxygen processes, sub‑micron control, and certified traceability systems command premium pricing and barrier protections.
- Explore strategic partnerships or minority equity in upstream suppliers (titanium sponge or silicon metal processors) where supply security is mission‑critical.
- Embed export‑control scenario planning into procurement and product roadmaps. Certification lags and cross‑border complexity can delay program timelines if not anticipated.
- Monitor competitor partnerships and capacity expansions closely — these are leading signals for pricing and availability shocks.
What PW Consulting’s full report delivers (operational, not just academic)
Our comprehensive report goes well beyond this preview. It includes detailed demand modelling by end‑use, particle‑size preference curves, supplier scorecards aligned to mil‑spec pathways, price‑sensitivity matrices, and scenario stress tests for supply shocks and defense‑budget swings. We provide granular procurement playbooks for defense primes and OEMs, including recommended contract clauses, inventory buffers by program lifetime, and a phased investment timetable for capacity scale‑up. The report also contains proprietary forecasts (2026–2032) built on a transparent, replicable methodology, plus appendices that map regulatory pathways and certification timelines across key jurisdictions.
To preserve commercial confidentiality and to encourage direct engagement with the full intelligence package, we intentionally withhold segment‑level revenue splits and fine‑grained regional shares in this press preview. These elements are central to program‑level decisions and are available exclusively in the full report and associated datasets.
Closing: why 2026 is a hinge year
2026 represents a pivot point. The market’s steady CAGR indicates growth sufficient to justify strategic investments, while structural supply‑chain and regulatory constraints create windows of advantage for first movers who secure feedstock, invest in differentiated processes, and lock in certification pathways. The concentrated supplier base amplifies the value of strategic supplier relationships and M&A. For executives who must make budgetary and capital allocation decisions this year, the actionable insight is to treat TiSi2 not as a routine raw material but as a strategic commodity that warrants integrated procurement, technical due diligence, and scenario planning.
PW Consulting’s full Worldwide Military Grade Titanium Disilicide Powder Market report (base year 2025) contains the detailed segmentation, forecast tables, and supplier analytics required to convert this strategic view into operational plans. Access the full intelligence package on our website to unlock the data and strategic templates you need to act with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Military Grade Titanium Disilicide Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com