

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Aescin Market to Grow from USD 318.45 Million in 2025 to USD 436.84 Million by 2032 at a 4.62% CAGR — Beta‑Aescin, Europe and Pharmaceuticals Dominate

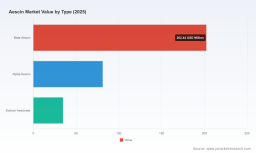
Worldwide Aescin Market — 2026 Strategic Preview for Decision-Makers
PW Consulting’s latest market study on the Worldwide Aescin Market delivers the actionable intelligence executives need to shape commercially successful strategies in 2026 and beyond. Built on a 2025 base year and a detailed historical window (2020–2025), the report projects the market across 2026–2032 and models a compound annual growth rate (CAGR) of 4.62%. Our top-line sizing shows a steady expansion from roughly USD 254 million in 2020 to an estimated USD 318 million in 2025, and continued growth through the forecast horizon. These macro dynamics set the stage for portfolio prioritization, supply-chain resilience, and regulatory positioning in the year ahead.
Worldwide Aescin Market
What’s inside the report — practical content you can act on
- Robust market sizing and a three-scenario forecast (base, upside, downside) covering 2026–2032, expressed in USD Million and reconciled to 2025 as the base year.
- Segmented demand analysis by region, product type (e.g., Beta‑ and Alpha‑Aescin, Sodium Aescinate) and application (pharmaceuticals, cosmetics/personal care, dietary supplements) with demand drivers and elasticities—granular tables and downloadable market models are available in the full report.
- Supply-side review including raw-material yield assumptions, extraction economics, and cost curve modelling informed by pharmacopeia parameters.
- Regulatory and reimbursement mapping (EU, US, selected national payers) with practical guidance for labeling, claims, and dossier preparation.
- Competitive profiling: strategic assessments of leading players, capability heatmaps, and a CR-based concentration analysis that quantifies market consolidation dynamics.
- Commercial playbook: go‑to‑market scenarios for novel formulations, co‑development frameworks, pricing levers, and M&A/inorganic growth options aligned to different strategic appetites.
- Risk register and mitigation matrix covering raw-material availability, regulatory shifts, adverse-event risk management, and reputational threats.
Why this report matters to executives planning in 2026
2026 will be a year of execution for companies that have spent 2024–25 validating portfolios and building evidence. The aescin market’s steady CAGR and predictable demand drivers create a clear window for investment — but success will require precise choices across three dimensions:
Worldwide Aescin Market
- Market access and claims strategy: regulatory treatments vary markedly by jurisdiction. In the EU, historical precedent and regulatory pathways exist for aescin-based herbal medicinal products, while in the US the class is typically positioned as dietary supplements—each pathway demands different clinical and labeling investments.
- Supply chain and raw-material optimization: extraction yields and saponin content materially influence cost per standardized unit; controlling or contracting upstream is a direct lever on margin and reliability.
- Portfolio differentiation: with clinically oriented pharmaceutical formulations on one end and cosmetics/consumer applications on the other, companies must align evidence generation with intended claim architecture to maximize reimbursement and premium pricing.
Key regulatory and clinical considerations
- European medicinal use: Horse chestnut seed extract formulations meeting a minimum escin dose threshold have established authorization pathways for symptomatic treatment of chronic venous insufficiency (CVI) in certain stages. This legacy regulatory position supports pharmaceutical claims in targeted EU markets, provided dossiers meet current quality and efficacy standards.
- Pharmacopoeial constraints and extraction science: The European Pharmacopoeia reports that aescin (the escin complex) comprises a defined share of saponins in dry horse chestnut seeds. This is a critical input into yield, standardization, and costing assumptions for extractors and formulators; small shifts in raw-material quality can meaningfully alter unit economics.
- US regulatory posture and safety signals: In the United States, aescin-containing products are frequently marketed as dietary supplements rather than approved drugs. This classification constrains medical claims and requires companies to be vigilant on adverse‑event communications and label disclaimers; public sources caution on potential kidney toxicity and bleeding risks, making pharmacovigilance and conservative marketing essential.
- Reimbursement precedence: Select national systems have pathways for partial or full reimbursement of topical aescin products when presented as therapeutic agents; Germany’s reimbursement frameworks have recognized certain topical aescin products in the venous insufficiency therapy space, demonstrating the value of payer-engaged evidence generation.
Competitive landscape — what the leading actors signal about the market
The market exhibits moderate concentration (CR3 ~32.5%; CR5 ~44.8%), indicating a mix of established specialists and differentiated mid‑sized players. Key incumbents illustrate the range of strategic postures:
Worldwide Aescin Market
- Mibe Jesu Christ GmbH (Bad Königshofen, Germany; https://www.mibe.de/): A legacy player in topical and oral formulations, known for branded topical therapeutics used in venous disorders. Strengths include established brand recognition and market access in Europe, supported by reimbursement pathways in specific national contexts.
- Indena S.p.A. (Milan, Italy; https://www.indena.com/): A botanical-extract specialist supplying standardized horse chestnut seed extracts to pharma customers. Indena’s capabilities in standardization, regulatory support, and supply agreements position it as a critical partner for formulators seeking consistent active profiles.
- Martin Bauer Group (Düsseldorf, Germany; https://www.martin-bauer-group.com/): A major herbal-extract supplier with strong nutraceutical and pharmaceutical channels. Its sourcing footprint and extract manufacturing scale are competitive advantages for customers prioritizing supply security and traceability.
- Aboca S.p.A. (Sansepolcro, Italy; https://www.aboca.com/): Focused on phytotherapeutic finished products, combining raw-material integration with branded consumer and clinical offerings. Aboca’s product development capabilities exemplify a vertically integrated strategy linking agricultural practices to finished‑product claims.
Together, these players highlight two viable strategic archetypes: (1) component specialists who monetize standardization and quality, and (2) integrated brand‑owners who capture value through finished formulations and market access. The moderate CR levels suggest opportunities for both differentiated entrants and consolidation plays aimed at scale.
Supply chain risks and raw‑material strategy
Raw-material variability is the single most actionable operational risk. The pharmacopoeial range for aescin in horse chestnut seeds means extraction yields can shift materially year-on-year. For 2026 planning, companies should consider:
- Securing multi-year offtake agreements or forward contracts with producers to stabilize input cost and availability.
- Investing in upstream traceability programs and agronomy partnerships that improve saponin yield and sustainability credentials.
- Assessing vertical integration or minority upstream investments to capture margin and reduce exposure to global agricultural volatility.
Priority actions for 2026 — an executive checklist
- Define claim architecture by market: allocate budget between clinical studies (to support pharmaceutical claims) and consumer-marketing (for cosmetics/supplement positioning) based on targeted geography and payer landscapes.
- Pursue supply resiliency: execute supplier audits, diversify sourcing geographies, and model extraction yield sensitivity to stress-test margins.
- Engage payers early in high-value markets where reimbursement is attainable; prepare dossiers that align to local HTA expectations where precedent exists.
- Optimize portfolio: prioritize SKUs with clear differentiation (standardization, novel delivery, combination therapies) and consider divesting low-margin commodity offerings.
- Explore inorganic options: target acquisition candidates that consolidate extraction capacity or expand formulation pipelines, measured against CR metrics and synergies.
- Implement robust pharmacovigilance and compliance programs, especially for markets where safety signals constrain labeling and claims.
How PW Consulting helps — the strategic support you can expect
The full PW Consulting report contains the quantitative and qualitative detail you need to operationalize the checklist above: downloadable market models (with region/application/type breakdowns), scenario P&L templates, supplier-scorecard tools, and a step‑by‑step reimbursement playbook for priority European and North American markets.
We intentionally present high-level market direction and strategic recommendations here while withholding granular segment tables and exact regional/application figures to ensure stakeholders access the validated data models directly from our report portal. For commercial teams, R&D heads, and corporate development officers preparing investment cases in 2026, the full dataset is the difference between directional insight and executable strategy.
Next step
PW Consulting is available to brief executive teams on the report findings and to run tailored workshops that translate global trends into localized action plans for 2026. Contact our industry practice to schedule a confidential, hands-on session that aligns your portfolio, supply-chain, and regulatory investments with the market pathways highlighted in this study.
For detailed analysis of this topic, please visit the official page: Worldwide Aescin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com