

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide GTCC Power Plants Market Reaches USD 29,400 Million in 2025, Poised for a 3.85% CAGR (2026–2032)

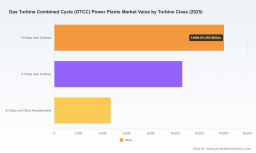
Worldwide Gas Turbine Combined Cycle (GTCC) Power Plants Market – Strategic Insights for 2026 Decision‑Makers
As organizations plan capital allocations and operational strategies for 2026, the GTCC power plant landscape presents both a resilient growth pathway and a complex set of execution risks. PW Consulting’s new market study (base year 2025, historical coverage 2020–2025, forecast 2026–2032) positions senior executives to navigate that landscape. The global GTCC market reached roughly USD 29.4 billion in 2025 and, under our central outlook, is expected to grow to approximately USD 38.3 billion by 2032 — reflecting a 3.85% CAGR over the forecast period. This briefing highlights the strategic value of the full report for board- and C-suite‑level decision making, while conserving the proprietary, deal‑critical granularity that sits behind our conclusions.
Worldwide Gas Turbine Combined Cycle (GTCC) Power Plants Market
Why GTCC remains strategically relevant in 2026
- Firm capacity and flexibility: GTCC assets continue to serve as the primary dispatchable partner for high‑penetration renewables. Advances in turbine start‑stop capability, faster ramp rates and combined cycle flexibility are directly linked to merchant revenue opportunities tied to ancillary services and peaking premiums.
- Technology convergence: Leading OEMs are pushing thermal efficiency boundaries (recent series are exceeding 64% in combined cycle configurations), and concurrently enabling hydrogen co‑firing and hybridization paths. These developments change the lifetime value equation of both greenfield plants and brownfield upgrades.
- Market dynamics and volumes: Global turbine shipment and order volumes have rebounded strongly since 2018, with significant ordering activity continuing into 2025. That volumetric demand has implications for lead times, risk premiums and the structure of long‑term service agreements.
- Fuel and regulatory sensitivity: Volatile natural gas pricing and rising capital cost expectations (including OEM reservation practices and increased financing scrutiny) materially influence project economics and procurement tactics in 2026.
Critical uncertainties that should shape 2026 decisions
- Fuel price trajectories and contracting strategy: With short‑to‑medium term spot price volatility and rising LNG flows, decisions about merchant exposure versus long‑term fuel indexing will determine project IRRs and lender comfort.
- Technology selection and retrofit optionality: Selecting turbine architectures that optimize current efficiency while enabling cost‑effective hydrogen blending and digital upgrades is a multi‑decade strategic choice.
- Supply chain and reservation risk: OEM delivery slots and reservation mechanisms are increasingly part of procurement negotiations; securing executable delivery dates and transferability provisions is now a procurement imperative.
- Market concentration and vendor risk: The GTCC supply chain is concentrated at the top; both competitive behavior and service economics are driven by a small number of OEMs whose decisions ripple across project pipelines.
What PW Consulting’s report delivers to CEOs, CIOs and investment committees
Our study is structured to be immediately actionable for capital allocation and operational planning, and comprises the following deliverables (selected highlights):
Worldwide Gas Turbine Combined Cycle (GTCC) Power Plants Market
- Top‑line market sizing and scenario forecasts through 2032, with downside and upside stress cases calibrated to fuel‑price, technology and policy shocks.
- Project economics toolkits — dynamic, model‑ready templates that let teams test merchant vs contracted revenue sets, hydrogen‑blend sensitivity, and different financing structures.
- Vendor benchmarking and procurement playbooks — comparative scorecards that evaluate OEMs on efficiency, hydrogen readiness, spare parts lead times, digital O&M capabilities and service agreement economics.
- Turnkey vs upgrade decision matrices — practical criteria and payback windows for choosing lifecycle extension, controls upgrades, or full replacement.
- Regulatory and permitting mosaics — overlays showing how emissions, grid codes and capacity‑market rules will influence project timelines in priority markets.
- M&A and JV playbooks — guidance for acquiring project pipelines, structuring minority stakes with OEM contractors, and mitigating execution risk in cross‑border engineering procurement and construction (EPC) engagements.
Competitive landscape: who matters and why
The GTCC vendor ecosystem is characterized by a handful of technology leaders and a broader tier of regional and specialty suppliers. Market concentration is high — the top three global OEMs account for roughly three‑quarters of the market by revenue, and the top five for close to nine‑tenths — a structural feature that affects negotiation leverage, delivery risk and long‑term service pricing.
Worldwide Gas Turbine Combined Cycle (GTCC) Power Plants Market
- GE Vernova — A strategic choice for clients prioritizing the highest‑output HA‑class machines and integrated digital services. Their positioning is oriented toward very large combined cycle plants and into markets where data‑center and AI‑driven electricity demand is reshaping baseload profiles.
- Siemens Energy — Competes on high‑efficiency H/HL‑class platforms with an explicit hydrogen‑capability roadmap and long‑term service models. Their commercial strength is in integrated solutions that marry high thermal efficiency with lifecycle service commitments.
- Mitsubishi Power (MHI) — Noted for the J‑series and JAC family, which deliver world‑class combined cycle efficiency and a strong turnkey EPC capability. Mitsubishi’s installed base has accumulated millions of operating hours, and recent award wins and upgrades confirm ongoing demand for their retrofit packages.
- Regional and specialty players — Manufacturers such as Ansaldo, Doosan, Kawasaki, Solar Turbines, Baker Hughes and others play differentiated roles: regional scale, smaller unit sizes, industrial cogeneration, or specialized service offerings. Their products are central to distributed GTCC and hybrid projects where modularity and local content are priorities.
Recent vendor developments underscore two operational themes for 2026: (1) OEMs are accelerating control‑system and reliability upgrades to support faster starts and greater renewables backup; and (2) large EPC awards and upgrade contracts continue to be the primary monetization path for the most advanced turbine series. These dynamics should be considered when timing procurement and negotiating LTSA or retrofit options.
Near‑term tactical moves for 2026 (fast‑action checklist)
- Lock in optionality: negotiate procurement contracts with explicit retrofit clauses for hydrogen and digital upgrades, and seek transferability on reservation deposits where applicable.
- Stress test fuel exposure: run project IRR scenarios across a range of gas‑price paths and secure fuel supply frameworks that balance price certainty with flexibility.
- Prioritize flexibility value: quantify revenues from ancillary services and fast‑start capability as part of the base case, not tails of the distribution.
- De‑risk delivery: require comprehensive milestone bankability in EPC contracts and tie milestone payments to verifiable supply‑chain deliverables.
- Plan for lifecycle services early: include LTSA negotiation strategies at RFP stage to avoid post‑deployment price escalation and ensure digital integration.
How PW Consulting’s proprietary intelligence adds decision‑making edge
Beyond the high‑level guidance above, the full PW Consulting study contains proprietary segmentations, granular project pipelines, vendor scorecards and monetized deal models designed for transaction teams and utility planners. We intentionally withhold those detailed splits in this public summary to preserve competitive confidentiality and to ensure our clients receive exclusive access to the datasets that drive investment decisions. Clients will gain access to:
- Project‑level pipelines with commissioning timelines, technology mappings and capital budgeting references;
- Vendor‑specific delivery and service risk matrices derived from recent OEM announcements and order books;
- Region‑to‑region comparative economics and regulatory overlays calibrated to capacity market rules and emissions regimes.
Final perspective: framing 2026 as a pivot year
For investors, utilities and industrial operators, 2026 represents a transition from opportunistic GTCC deployment toward an era where turbine choice, contractual architecture and retrofit flexibility materially determine asset value over multiple decades. The sector’s moderate compound growth masks a larger redistribution of value toward flexibility, digital services and decarbonization enablement. Strategic decisions taken in 2026 — from turbine class selection to LTSA structure and hydrogen readiness — will compound in value for the remainder of the asset lifecycle.
For executive teams preparing budgets, negotiating procurement or evaluating M&A opportunities this year, the full PW Consulting GTCC report provides the quantitative models, vendor intelligence and playbooks needed to convert the broad growth trend into executable strategy. To access the complete dataset, vendor scorecards and bespoke scenario models, please consult PW Consulting’s full report and advisory services.
For detailed analysis of this topic, please visit the official page: Worldwide Gas Turbine Combined Cycle (GTCC) Power Plants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com