

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: SiC Power Devices for New Energy Vehicles to Expand at 28.45% CAGR, Market Poised to Reach USD 31,616.9 Million by 2032

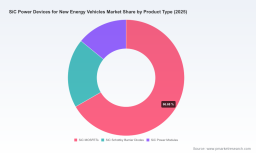
SiC Power Devices for New Energy Vehicles: Strategic Imperatives for 2026
PW Consulting’s latest market intelligence — the Sic Power Devices For New Energy Vehicles Market report (base year 2025) — reframes the strategic choices facing OEMs, tier‑1 suppliers, semiconductor vendors and private capital as SiC (silicon carbide) moves from specialist advantage to mainstream architecture in new energy vehicles (NEVs). Our analysis combines rigorous historical tracking (2020–2025), forward projections (2026–2032) and practical, decision‑grade tools to support the critical make/buy, architecture and partnership decisions companies must resolve in 2026.
Sic Power Devices For New Energy Vehicles Market
Market Trajectory and Strategic Context
The macro picture is decisive: the SiC power device market scaled rapidly through the first half of the decade — rising from a sub‑billion market in 2020 to a multi‑billion platform by 2025 — and is projected to continue at a high‑velocity growth path across our forecast window. PW Consulting’s modelling shows a compound annual growth rate (CAGR) of 28.45% during the 2026–2032 forecast period, taking total market value from the 2025 baseline into a distinctly larger multi‑billion market by 2032. That pace is not evenly distributed across projects and product types; rather, it is driven by a confluence of vehicle architecture shifts, supplier consolidation, and technology maturation.
Sic Power Devices For New Energy Vehicles Market
For executive teams planning capital allocation, product roadmaps, or supplier strategies in 2026, two facts stand out: (1) timing matters — early commitments to SiC supply and qualification accelerate product differentiation; (2) concentration matters — a relatively small group of suppliers now command a significant share of available automotive‑grade SiC capacity, affecting negotiating leverage, qualification timelines and risk exposure.
Sic Power Devices For New Energy Vehicles Market
Report at a Glance — Practical Outputs
- Market synthesis: validated historical market build (2020–2025) and a clear scenario‑based forecast for 2026–2032 with sensitivity to wafer supply, yield trajectories and 800V architecture adoption.
- Decision tools: procurement scorecards, supplier qualification checklists (AEC‑Q and JEDEC alignment), TCO and payback calculators calibrated to automotive powertrain and fast‑charging use cases.
- Technology roadmap: product maturity matrices for SiC MOSFETs, Schottky diodes and integrated modules, with guidance on generational trade‑offs (power cycling, switching loss, thermal management).
- Competitive playbook: concise supplier dossiers, partnership archetypes (licensing, OEM vertical integration, foundry relationships), and M&A filter criteria for acquirers and target screening.
- Operational templates: qualification timelines, test plans that map to JEDEC and AEC‑Q expectations, and pilot‑to‑scale transition checklists that reflect substrate and yield realities.
Key Strategic Insights for 2026 Decision‑Makers
- Locking in supply is a competitive necessity. With limited availability of 200 mm SiC substrates and a constrained volume profile among the handful of global substrate suppliers, lead times and allocation risk will determine product launch cadence for many OEM programs. Companies that secure multi‑year offtake or invest in upstream capacity will gain both assurance of supply and margin advantage.
- Architecture choices materially change SiC content and ROI. The industry shift to higher‑voltage vehicle architectures (e.g., 800V class) materially increases per‑vehicle SiC content and changes cost‑benefit thresholds for inverter and fast‑charging investments. Firms must align product roadmaps and supplier contracts to projected architecture mix in their vehicle programs.
- Qualification and standards are non‑negotiable calendar items. JEDEC’s test methods for wide‑bandgap switching energy and the entrenched AEC‑Q automotive qualification standards elevate the time and cost required to bring SiC devices into mainstream vehicle use. Starting qualification activities early is the most reliable way to avoid launch slippage.
- Quality and yield are the dominant cost drivers today. High defect densities in SiC wafer production (typical dislocation densities in the low thousands per cm²) keep yields below those of mature silicon processes, sustaining a cost premium. Buyers and investors should model yield improvement scenarios explicitly when evaluating pricing and payback.
- Consolidation creates both threat and opportunity. Market concentration metrics show that a small number of vendors control a large share of automotive‑grade capacity. That concentration increases pricing power for leaders but also sharpens the strategic value of partnerships, licensing deals and defensive vertical integration by OEMs and large tier‑1s.
Competitive Landscape — What the Leading Players Mean for Your Strategy
Our competitive analysis synthesizes product roadmaps, manufacturing footprints and go‑to‑market strategies for leading SiC suppliers and integrators. A few illustrative implications:
- Wolfspeed (Durham, NC) is pushing aggressive power density and cycling capability with Gen‑4 modules; recent introductions signal readiness for high‑power inverter platforms and place pressure on incumbents to match performance while balancing cost.
- European suppliers such as Infineon and STMicroelectronics bring deep automotive qualification experience and integrated power module offerings, appealing to OEMs prioritizing qualification speed and systems integration.
- Japanese players (ROHM, Mitsubishi Electric, Fuji Electric) emphasize module reliability and integration with established automotive supply chains — valuable for programs where ruggedized packaging and long lifecycle support are critical.
- onsemi and Semikron Danfoss reinforce the market’s diversity of approaches: from device‑level optimizations to module integrations, offering alternatives for differing system architectures and volume profiles.
- Vertically integrated OEM suppliers, exemplified by BYD’s semiconductor arm supplying internal vehicle programs, change market dynamics by internalizing value capture and shifting where volume commitments are directed.
Recent marketplace signals are compelling: Wolfspeed’s late‑2025 Gen‑4 six‑pack modules and high‑current capability underscore the performance trajectory; mainstream OEMs have begun production adoption, and suppliers such as Bosch continue to launch generational product updates. Each development tightens windows for procurement and qualification decisions.
Supply‑Chain and Manufacturing Dynamics
Two production realities require special attention. First, substrate capacity (200 mm SiC) remains concentrated and is a gating factor for scale; second, wafer defect densities and yield improve only incrementally year‑over‑year. These constraints combine to keep lead times and price volatility in play through at least the near term. For corporate strategists this translates into tactical playbooks:
- Adopt multi‑node sourcing with prioritized preferred partners and fallbacks to mitigate allocation risk.
- Structure long‑lead contracts with volume bands to secure capacity while preserving optionality as yields improve.
- Invest selectively in downstream packaging or joint‑venture pilot lines to capture margin without shouldering full upstream capex risk.
- Build qualification pipelines aligned to JEDEC and AEC‑Q roadmaps to compress time‑to‑production risks.
90‑Day and 18‑Month Roadmaps — Tactical Next Steps
- 90 days: Conduct supplier stress tests (financial, capacity, qualification history); model TCO under alternate yield and wafer price assumptions; launch pilot qualification with at least one Tier‑1 and one pure‑play SiC vendor.
- 6–18 months: Finalize architecture decisions for upcoming platforms (48V vs 800V implications), negotiate multi‑year offtake or strategic equity arrangements where warranted, and implement internal test benches aligned to JEDEC/AEC‑Q for in‑house validation cycles.
Why This Report Matters for 2026
Executives who treat SiC as merely a component cost will miss the strategic inflection: SiC decisions ripple across inverter design, thermal management, vehicle architecture and supplier ecosystems. PW Consulting’s Sic Power Devices For New Energy Vehicles Market report is built to convert macro growth narratives into executable plans. It combines the high‑level market trajectory (historical scale, 2025 baseline and a 28.45% CAGR through 2032) with granular, actionable frameworks — from supplier scorecards and qualification timelines to M&A screening filters and TCO calculators.
Importantly, this release follows a “trailer” principle: this briefing demonstrates our methodological rigor and the actionable nature of our insights while reserving the complete segmented datasets, supplier scorecards and scenario worksheets for the full report. That confidential data is where near‑term competitive advantage is created — and where clients will find the specific inputs needed to finalize procurement, investment and architectural choices in 2026.
Next Steps
If your 2026 plans include powertrain redesign, fast‑charging enablement, supplier consolidation, or strategic investment in SiC upstream capacity, PW Consulting’s full report and advisory services provide the empirically grounded, operationally focused guidance to prioritize and execute. Engage with our industry team to access the full dataset, bespoke scenario modelling, and implementation support tailored to your risk appetite and program timelines.
For detailed analysis of this topic, please visit the official page: Sic Power Devices For New Energy Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com