

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: High-Isolation RF Switches Market Set to Expand Rapidly — 9.12% CAGR Projected Through 2032

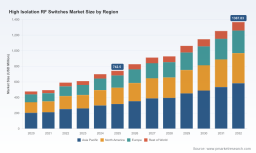
Worldwide High Isolation RF Switches Market — Strategic Outlook for 2026: A PW Consulting Preview
Executive snapshot
As organizations prepare their 2026 product roadmaps, procurement plans, and M&A theses, clarity on the trajectory of high isolation RF switches is no longer optional. PW Consulting’s latest market study (base year 2025, historical review 2020–2025, forecast 2026–2032) demonstrates a sustained growth runway: the worldwide market expanded from under half a billion USD in 2020 to approximately 742.5 Million USD in 2025, and our central-case forecast anticipates continued expansion at a compound annual growth rate of roughly 9.12% through 2032, when the market is projected to approach 1.37 Billion USD. This preview explains why that macro trend matters for executive decisions in 2026, what pragmatic levers leaders should consider, and where to find the detailed, transaction-grade intelligence contained in our full report.
Worldwide High Isolation RF Switches Market
Why high isolation RF switches matter to 2026 strategy
-
Critical enabler for next‑generation RF systems — High isolation switches remain a gating component across telecommunications infrastructure, aerospace & defense, instrumentation, and emerging automotive RF sub-systems. Their performance characteristics (isolation, insertion loss, power handling, linearity and bandwidth) directly influence system-level metrics, from RF front-end resiliency to signal-chain measurement uncertainty.
Worldwide High Isolation RF Switches Market -
Accelerating demand vectors — The confluence of higher frequency deployments, densification of wireless infrastructure, evolving radar and electronic warfare requirements, and stricter test & measurement tolerances underpins the market’s mid‑ to long‑term expansion. Our analysis shows that technical differentiation and supply continuity will drive premiumization in select product tiers.
Worldwide High Isolation RF Switches Market -
Strategic fragility under geopolitical and material pressures — Trade tensions and export control regimes are re-shaping sourcing strategies. Concurrently, materials and process shifts such as GaN adoption for high‑power/high‑isolation applications introduce both opportunities and execution risks for incumbents and new entrants alike.
What the PW Consulting report delivers — pragmatic, actionable intelligence
Beyond headline forecasts, our report is designed as an operational playbook for decision-makers. Key deliverables include:
-
Robust market model (2020–2032) with scenario variants — base, upside, and downside cases; sensitivity layers tied to adoption rates, technology substitution, and regulatory shocks.
-
Go‑to‑market and procurement frameworks — supplier shortlists, dual‑sourcing decision trees, and cost‑to‑serve mapping for OEMs looking to balance performance with supply security.
-
Vendor benchmarking and capability matrices — technical scorecards covering topology (absorptive vs reflective), semiconductor substrate (SOI, GaN, MEMS, PIN), frequency coverage, power handling, and manufacturability risk. These are calibrated to end‑market use cases and production volumes.
-
Technology roadmaps and migration playbooks — timing guidance for GaN‑on‑Si, MEMS and UltraCMOS migrations that balances performance upside with qualification and cost curves.
-
Supply‑chain risk assessment — export control impacts, single‑source exposures, and obsolescence timelines with mitigation tactics prioritized by probability and enterprise impact.
-
M&A and partnership scouting pack — target screens, valuation vectors, and integration checklists focused on strategic tuck‑ins and capability buys.
Competitive landscape — themes and strategic implications
The sector exhibits a moderate degree of concentration; our concentration metrics signal a market where a small group of established players control a meaningful share of revenue and design‑wins, yet there remains room for focused specialists and differentiated newcomers. Among the companies we profile in depth, several archetypes emerge:
-
Platform incumbents with portfolio breadth — Firms offering broad RF portfolios and multiple switch topologies (including high‑isolation silicon and absorptive switches) remain first-choice partners for large OEMs that require tight integration across transceivers and front‑ends. Their advantages include scale in qualification, long-standing OEM relationships, and multi‑region manufacturing footprints.
-
Specialist innovators — Companies that focus on enabling technologies (e.g., MEMS, UltraCMOS SOI, GaN-enabled switches) are displacing incumbents in niche, high‑performance segments. Examples include MEMS-based entrants that offer superior standoff voltage and wideband performance for EW and missile applications, and SOI-based platforms with proven broadband isolation up to single-digit GHz ranges for infrastructure and routing roles.
-
Electromechanical suppliers — Electromechanical coaxial and relay switches retain a distinct role where absolute isolation, linearity and high power handling are non‑negotiable (harsh RF environments, high-power ATE, and specific military platforms). These suppliers are focal points for defense primes and specialized test houses.
Recent product introductions underscore how quickly capability gaps can be filled: late‑stage launches of high‑standoff, wideband protection switches for aerospace & defense illustrate the ongoing push to combine higher isolation with increased power handling. For strategists, the implication is clear — product parity can shift rapidly and procurement roadmaps must reflect a shorter technology cycle for high‑end variants.
Practical recommendations for 2026 decision-makers
-
For OEMs and system architects: prioritize dual‑track development. Maintain design pathways for both incumbent silicon and emerging GaN/MEMS options to de‑risk time‑to‑market while preserving a route to performance uplift.
-
For procurement leaders: implement tiered sourcing playbooks that combine strategic long‑term agreements with fast‑reaction spot capabilities. Embed export‑control compliance and certificate-of-origin checks into supplier scorecards.
-
For suppliers and component vendors: invest selectively in capability adjacency (e.g., packaging expertise, high‑power characterization labs) that raises barriers to entry and shortens qualification cycles for large OEMs.
-
For investors and M&A teams: look for targets that provide either a defensible technology wedge (patented MEMS actuation, GaN process know‑how) or a proven channel to defense primes — those assets compress commercialization risk while commanding premium multiples in consolidation scenarios.
Supply chain, regulation, and materials — what keeps executives up at night
Trade policy and export controls are an active and visible risk vector. Organizations that rely on geographically concentrated suppliers for high‑isolation RF components face potential delivery and qualification disruptions. Our report presents a layered mitigation framework combining near‑term tactical measures (safety stock, alternate suppliers, localized assembly) with medium‑term strategic moves (multi‑country footprint, IP licensing, joint‑development agreements) that materially reduce enterprise exposure.
On the materials and process front, GaN is increasingly relevant for high‑power isolation roles; however, its supply chain and process maturity vary by geography and vendor. Decision-makers should treat GaN adoption as a staged investment, underpinned by clear qualification gates and cost‑of‑ownership modelling rather than pure performance benchmarks.
Technology horizon — from component to system value
Topology choice (absorptive vs reflective), substrate technology (SOI, GaN, MEMS, PIN), and packaging approaches will define the next three years of competitive differentiation. Our report maps adoption timing to end‑market readiness, showing where early adoption can translate into competitive advantage and where conservative approaches minimize technical debt. For instance, absorptive SPDT topologies with industry-leading isolation are rapidly becoming default choices in certain sensitive RF paths, while electromechanical relays remain indispensable in specific high‑power or legacy test environments.
How PW Consulting’s analysis empowers 2026 decisions
Clients tell us they need more than a forecast; they need a navigable path from insight to execution. The full Worldwide High Isolation RF Switches Market report includes the datasets, supplier profiles, scenario tools and checklists required to:
-
Quantify near‑term procurement exposure by supplier and topology;
-
Prioritize product investments and qualification spending across competing technology options;
-
Build M&A diligence materials that separate transient customer wins from defensible revenue streams.
In this preview we deliberately withhold granular region‑by‑region and application‑by‑application splits, detailed supplier share tables, and line‑item pricing curves — these are provided in the full report to enable program-level decisioning and supplier negotiations.
Next steps
For executives ready to translate the projected market momentum into executable 2026 plans — whether you are an OEM securing supply, a supplier shaping an investment thesis, or an investor screening targets — PW Consulting offers tailored briefings, data licensing options, and strategic workshops that put our model and recommendations into your operational context. Contact our advisory team to schedule a briefing and to obtain access to the full dataset and vendor dossiers referenced in this preview.
— PW Consulting, Senior Strategy & Industry Analysis Team
For detailed analysis of this topic, please visit the official page: Worldwide High Isolation RF Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com