

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Water-Soluble Vitamins & Minerals in Feed Market to Expand at 5.85% CAGR During 2026–2032

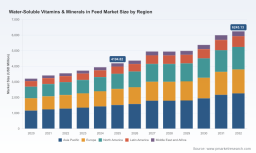
PW Consulting: Strategic Brief — Water Soluble Vitamins & Minerals in Feed Market (Preview)
PW Consulting’s latest market intelligence brief on Water Soluble Vitamins & Minerals in Feed synthesizes five years of historical data and a seven‑year forward outlook to arm industry leaders with the strategic context required for decisive action in 2026. The global market is on a steady expansion path — having grown through the early 2020s and reaching an estimated market size of USD 4,194.82 Million in our 2025 base year — and we project continued growth at a compound annual growth rate (CAGR) of 5.85% across the 2026–2032 forecast window. By 2032 the market is expected to surpass USD 6.2 billion (USD Million unit basis), driven by innovation in nutrient protection, changing production systems, and evolving regulatory pressure on feed quality and traceability.
Water Soluble Vitamins Minerals In Feed Market
Why this report matters for 2026 strategy
2026 will be a year when operational and commercial choices made now determine competitive position for the remainder of the decade. The water‑soluble vitamin and mineral segment sits at the intersection of feed formulation science, raw material market volatility, and regulatory scrutiny. Our report is designed to translate that intersection into practical decisions: where to allocate R&D budgets, how to structure supply agreements, which product formats to prioritize for stability and bioavailability, and how to design resilient sourcing strategies against geopolitical and input‑price shocks.
Water Soluble Vitamins Minerals In Feed Market
-
Evidence‑based foresight: We integrate historical trends (2020–2025) with granular demand drivers to produce scenario‑based forecasts for 2026–2032 that go beyond headline growth rates.
Water Soluble Vitamins Minerals In Feed Market -
Decision‑centric outputs: The brief contains templates for commercial sensitivity analyses, a supply‑risk heatmap, and a modular playbook for product and channel launches.
-
Investor and M&A lens: For financial sponsors and corporate development teams, the report highlights value pools and consolidation pathways that are actionable within a 12–24 month integration horizon.
What’s inside (practical contents)
-
Market architecture and demand drivers — A concise breakdown of the forces shaping adoption across production systems, including precision nutrition, feed conversion improvements, and species‑specific welfare initiatives.
-
Commercial modelling toolkit — Revenue scenarios, margin levers, and a cost pass‑through model that quantifies the impact of precursor price swings on finished premix economics.
-
Supply chain & sourcing playbook — Supplier mapping, critical input concentration risk, and contract structuring templates to mitigate dependence on single‑source geographies.
-
Regulatory watch and compliance mapping — A practical tracker that aligns regionally significant regulatory processes with product development timelines and market access milestones.
-
Technology adoption and formulation guidance — Evaluation of nutrient protection technologies (including microencapsulation), preservation strategies for oxidation‑sensitive vitamins, and recommendations for formulation stability testing protocols.
-
Competitive benchmarking — Business model, channel strategy, and capability assessments of the leading global suppliers, including strategic strengths and potential gaps.
-
Actionable market entry and growth playbooks — Step‑by‑step GTM pathways for incumbents and new entrants tailored to different capital and operational profiles.
Competitive landscape — what incumbents are doing
The market’s top players exhibit divergent but complementary competitive vectors. Major ingredient and nutrition companies are leveraging global scale, integrated production, and product platform breadth to protect margins and accelerate adoption of enhanced vitamin formats.
-
dsm‑firmenich: Maintains a broad portfolio across water‑soluble vitamins and premix solutions, with emphasis on stability and bioavailability that supports customers focused on performance and consistency.
-
BASF SE: Leverages its chemical and process expertise to deliver high‑purity water‑soluble vitamins and scalable manufacturing for feed applications.
-
Adisseo (Bluestar): Continues to push application guidance and technical support to drive higher inclusion precision through its Microvit® line; recent updates to its nutrition guides indicate an intensified focus on production‑stage optimization.
-
Nutreco (Trouw Nutrition), Alltech, ADM, Cargill: These vertically integrated players pair premix supply with farm‑level advisory or feed mill integration to drive uptake through bundled service offerings.
-
Evonik, Lonza, Kemin: Niche specialization in high‑purity additives, antioxidant protection, and specialty delivery systems positions these firms as strategic partners for formula innovation.
Market concentration is meaningful but leaves room for differentiation: the top tier captures a substantial portion of global demand while mid‑tier and specialist players continue to create value through technical service, local presence, and differentiated delivery forms.
Recent industry developments shaping 2026 decisions
-
Product guidance updates: Adisseo’s release of an updated Microvit® Nutrition Guide (late 2025) formalizes revised recommended inclusion levels across multiple species and production stages — a direct signal that precision dosing will be a commercial battleground.
-
Technology scaling: The sector has begun scaling microencapsulation and related nutrient protection techniques; the practical effect is longer shelf life, improved on‑farm stability, and reduced wastage from oxidation or heat exposure — factors that materially alter cost/benefit calculations for feed formulators.
-
Strategic alliances: The Akralos Animal Nutrition joint venture (ADM/Alltech) announced in early 2026 exemplifies consolidation aimed at combining feed operations and accelerating distribution of mineral‑ and vitamin‑fortified solutions across North America.
Risk dynamics — what to watch
-
Raw material volatility: Feed vitamin production remains sensitive to precursor availability and carrier inputs. Fluctuations in agricultural co‑products and fermentation feedstocks can compress margins rapidly if not covered through hedging or diversified procurement.
-
Regulatory flux: Ongoing reauthorizations and renewals — particularly in the EU — create timing risk for product formulations that rely on specific additives. Companies must maintain active regulatory intelligence to avoid market disruptions.
-
Geopolitical supply concentration: A high share of global feed vitamin sourcing is dependent on specific producing geographies. Buyers should model scenarios for supply shocks and adopt multi‑sourcing or inventory buffers where economically justified.
-
Organic and specialty standards: Standards for vitamins in organic production (notably in North America) continue to evolve; manufacturers targeting these segments require certification roadmaps and traceable sourcing chains.
Strategic recommendations for 2026
-
Prioritize protected formats for high‑value channels: Invest selectively in microencapsulated or antioxidant‑protected lines where shelf life and field stability unlock price premiums and reduce on‑farm waste.
-
Hedge and diversify feedstock procurement: Use scenario analyses from our commercial toolkit to determine optimal balance between just‑in‑time sourcing and strategic inventory for key precursors.
-
Embed regulatory and traceability capabilities into R&D timelines: Align product launches with known authorization cycles and build certification pathways for organic and specialty segments where appropriate.
-
Partner to scale distribution: Consider alliances or joint ventures in markets where feed mill networks and advisory services accelerate diffusion of technical formats.
-
Leverage advisory as a differentiation: Technical support, species‑specific inclusion guides, and farm‑level performance tracking can convert commodity supply into sticky, higher‑margin relationships.
How PW Consulting’s report supports execution
This is not a descriptive market snapshot — it is an execution manual. Clients receive a downloadable modelling package, a regulatory calendar aligned to product development milestones, supplier risk matrices, and a prioritized investment roadmap mapped to short‑ and medium‑term return profiles. Our scenario engine allows clients to stress‑test commercial plans under defined shocks (raw material price spikes, regulatory delays, or supply interruptions) and to quantify the expected P&L impact across alternative mitigation paths.
Next steps — what readers should do now
For executives responsible for portfolio strategy, supply chain, or commercial execution in 2026, the immediate actions are clear: validate your exposure to raw‑material supply concentrations, stress test new product economics with protected vitamin formats, and align business development with regulatory timelines documented in the report. PW Consulting’s full report contains the granular segment matrices, country‑level demand curves, and company scorecards required to convert these strategic imperatives into 90‑ to 180‑day action plans.
We have intentionally kept this briefing focused on strategic takeaways and omitted the granular regional and application‑level splits to preserve the preview nature of this release. For the full dataset, segmented forecasts, and the downloadable modelling toolkit, visit the PW Consulting report page (Water Soluble Vitamins & Minerals in Feed Market — Full Report) or contact our industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Water Soluble Vitamins Minerals In Feed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com