

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Diamond Anvil Cell Market Poised to Reach USD 98.03 Million by 2032, Growing at a 6.15% CAGR

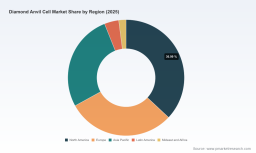
Worldwide Diamond Anvil Cell Market — Strategic Preview for 2026 Decisions
PW Consulting’s new market intelligence release on the Worldwide Diamond Anvil Cell (DAC) Market delivers an action-oriented lens for executives planning capital allocation, partnerships, and product strategy in 2026. Built on a 2025 base year with historical tracking across 2020–2025 and forward forecasts to 2032, the study quantifies a clear growth runway: the global market is estimated at USD 64.55 Million in 2025 and is modeled to reach USD 98.03 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.15% during the 2026–2032 forecast window. This preview explains why that trajectory matters for strategic choices next year, what competitive dynamics will shape winners and losers, and the practical, immediately actionable outputs included in the full report (note: granular sub-segment disclosures have been intentionally withheld here to encourage direct access to the source report for procurement-ready detail).
Worldwide Diamond Anvil Cell Market
High-level, data-driven takeaways
- Steady, research-driven expansion: The DAC market is not a one-off spike tied to a single technology — it is a structural growth story driven by sustained investments in high-pressure research across materials science, geophysics, and condensed-matter physics, plus expanding use of synchrotron and optical probes in industrial R&D laboratories.
- Moderate market concentration: Leading vendors account for a meaningful share of supplier revenue pools (CR3 ~42%, CR5 ~59%), creating advantages for established OEMs while leaving strategic openings for specialized product innovators and service providers.
- Technology differentiation is decisive: Membrane-driven cells, precision-engineered symmetric platforms, specialized piston and Merrill-Bassett designs, and advances in CVD diamond tooling are defining buyer choice. Instrument-level design innovations and consumable ecosystems (anvils, gaskets, micro-drillers) drive recurring revenue and lock-in.
- Supply chain and safety constraints are non-trivial: High-quality diamond anvils, tooling for hard gasket materials, and safe handling protocols (especially for historically used beryllium components) create procurement and operational risk that must be managed proactively.
- Commercial scope beyond hardware: Training, beamline integration services, custom sample environments, and aftermarket consumables are high-leverage revenue streams for OEMs seeking margin expansion.
What the full report contains — practical, actionable modules
- Market sizing and methodology: reproducible top-down and bottom-up models anchored to historical instrument shipments and laboratory capex patterns.
- Technology deep dives: comparative analyses of DAC architectures, materials choices, thermal/pressure operating envelopes, and optical/beamline compatibility constraints.
- Vendor benchmarking: competency matrices across engineering design, aftermarket consumables, service footprints, and certifications — including operational strengths and strategic gaps for the market’s most visible suppliers.
- Buy-side playbooks: procurement checklists, specification templates, total cost of ownership (TCO) calculators, and vendor selection frameworks tailored to research institutions and industrial labs.
- Scenario planning: demand sensitivity to funding cycles, synchrotron allocation, and disruptive technology adoption, with downside/upside revenue corridors and stress-test case studies.
- Commercial strategy templates: routes-to-market for OEMs, M&A screening criteria for strategic acquirers, and service-model blueprints for after-sales monetization.
Competitive landscape — who to watch and why
- Almax easyLab — A legacy innovator with broad product breadth and manufacturing capability, notable for a comprehensive piston- and lever-style product line and integrated diamond anvil offerings. Its dual-market footprint and product certification posture (ISO9001 / CE) make it a reference supplier for many national labs and beamline operators.
- DAC Tools LLC — A US-based engineering specialist focused on tailored DAC systems and sample environment tooling. Its increasing prominence in practitioner training and workshops strengthens its brand as a solutions-oriented partner for applied research teams.
- BETSA — Market leader in membrane-driven DACs, with recent catalog refreshes targeting ultra-high pressure and extended temperature envelopes. BETSA’s new compact MDAC variants are specifically designed to improve angular access and working distance — features that matter in optical and X-ray beamline integration.
- LOTO-eng — A focused innovator applying opto-mechanical and electronic approaches to DACs for extreme conditions. Firms like LOTO-eng exemplify how niche engineering skills create differentiation for specialized experimental setups.
- Core Laboratories (Core Lab) — Leveraging partnerships and adapted configurations for extreme-condition testing, Core Lab bridges academic-style DAC capability with industry-oriented sample handling and beamline efficiency methods.
- Technodiamant & IMAT CVD — Two suppliers that illustrate the critical role of upstream tooling and materials: precision-crafted anvils and high-performance CVD diamond substrates underpin instrument performance and reliability.
- PerkinElmer — An example of a larger instrumentation vendor integrating miniaturized DAC capabilities into analytical workflows, highlighting the adjacent opportunity to embed high-pressure functionality into broader spectroscopic product lines.
Recent vendor activity underlines the competitive dynamics: Almax’s scheduled trade show presence at EMPG in 2025, DAC Tools’ educational masterclass at APS SCCM25, BETSA’s product catalog updates for ultra-high-pressure MDAC variants, and ongoing design innovation published by independent researchers signal a healthy mix of market consolidation and continuous technical iteration.
Worldwide Diamond Anvil Cell Market
Strategic implications for 2026 decision-makers
- R&D investment prioritization — Allocate funds to interface technologies (gasket materials, anvils, and sample alignment systems) that multiply the utility of base DAC hardware. Incremental improvements in working distance, angular access, and thermal stability will unlock broader adoption across instrument platforms.
- Supplier risk mitigation — Diversify sourcing for critical consumables (anvils, gaskets, micro-drillers) and establish qualified-alternate lists. Avoid single-sourced dependence on hazardous materials by specifying non-beryllium gasket solutions where X‑ray transparency and operator safety are requirements.
- Service-led differentiation — For OEMs, bundle training, calibration, and beamline-integration services to build sticky, recurring revenue streams. For buyers, prioritize suppliers that offer verified lifecycle support and onsite commissioning for complex experiments.
- Certification and compliance as a commercial lever — Suppliers maintaining formal quality systems and safety certifications will capture larger institutional deals, particularly where laboratory safety and procurement policy impose strict vendor requirements.
- M&A and partnership focus — Acquisitions or exclusive agreements that add CVD diamond capability, precision anvil craftsmanship, or beamline integration expertise can accelerate entry into higher-margin, application-specific segments.
Operational playbook — immediate steps for 90/180/365 days
- 90 days: Conduct a supplier capability audit; prioritize top-2 vendor partnerships for quick-win consumables continuity; launch internal safety review on gasket machining and handling protocols.
- 180 days: Initiate a pilot evaluation with at least one membrane-derived DAC configuration on representative beamline or lab optics to validate working-distance and angular performance claims; negotiate longer-term consumable pricing with preferred suppliers.
- 365 days: Implement a staged procurement plan that sequences hardware acquisition with operational readiness (training, calibration, spare parts); evaluate strategic bolt-ons (materials supplier or service provider) for acquisition or JV to accelerate market entry and margin capture.
KPIs and metrics executives should track
- Time-to-first-experiment for new DAC deployments (operational readiness)
- Consumables attach rate and replacement cycle (recurring revenue indicator)
- Supplier qualification lead time and single-source dependency ratio (procurement risk)
- Beamline utilization or instrument booking rate (demand signal)
- R&D-to-sales conversion for new DAC-enabled applications (innovation ROI)
Why PW Consulting’s report matters for your 2026 roadmap
Our study synthesizes instrument-level engineering insight, supplier interviews, and buy-side procurement intelligence into a compact set of decision tools designed for 2026 planning cycles. Customers will receive reproducible market models, vendor-by-vendor capability assessments, procurement playbooks, and scenario analysis that converts the market’s medium-term growth (USD 64.55M in 2025 to USD 98.03M by 2032 at a 6.15% CAGR) into clear bets on product development, M&A, and service models. The full dataset includes granular segmentation, regional and application splits, and vendor financial profiling — information deliberately omitted from this preview to preserve the report’s role as a practical, purchase-ready asset.
Worldwide Diamond Anvil Cell Market
Executives preparing budgets or R&D roadmaps for 2026 should treat DAC market signals as both an opportunity and a constraint: the instrument base is expanding, but so are expectations on precision, safety, and integrated services. For a tailored briefing, procurement checklist templates, or to access the full report with comprehensive sub-segment tables and supplier scorecards, contact PW Consulting’s Industrial Instruments Practice — our advisory team will map the market intelligence directly to your strategic options and near‑term execution plan.
For detailed analysis of this topic, please visit the official page: Worldwide Diamond Anvil Cell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com