

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 4.15% CAGR for Industrial Combustion Air Blower Market in 2026–2032 Outlook

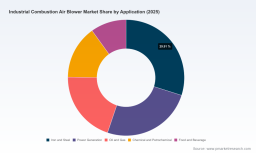
Industrial Combustion Air Blower Market: Strategic Imperatives for 2026 — PW Consulting Preview
Executive summary
PW Consulting’s latest market study on the Industrial Combustion Air Blower market establishes a fact base and decision framework tailored for executive teams setting capital allocation, product road‑mapping, and compliance strategies in 2026. The market has shown steady expansion through the first half of the decade — growing from USD 1,720.5 Million in 2020 to USD 2,085.49 Million in 2025 — and our base‑case projection anticipates continued growth to approximately USD 2,772.19 Million by 2032, reflecting a 4.15% compound annual growth rate over the 2026–2032 forecast window. Market concentration is meaningful but not prohibitive: the top three players account for roughly 32.4% of revenue while the top five approach 46.85%, indicating opportunities for scale players and specialists alike.
Industrial Combustion Air Blower Market
Why this matters for 2026 decision cycles
-
CapEx prioritization: With mid‑single digit CAGR and predictable demand from process heating segments, industrial OEMs and end users must sequence investments to balance lead‑time risk against efficiency retrofits and replacement cycles.
Industrial Combustion Air Blower Market -
Product compliance and design: Emerging and evolving energy and ecodesign rules in major markets are reshaping allowable performance envelopes and procurement criteria. Manufacturers and specifiers who integrate regulatory roadmaps into 2026 product planning will avoid costly re‑engineering downstream.
Industrial Combustion Air Blower Market -
Supply chain resilience: Volatility in core metals (steel, aluminum, cast iron) materially shifts BOM costs and lead times. Hedging, supplier diversification, and design for materially substitution are immediate levers to protect margins.
-
Service and aftermarket monetization: Given the installed base growth and durability of combustion blowers, services, spare parts, and digital monitoring provide high‑margin revenue lines that can be scaled fast relative to new equipment sales.
What the PW Consulting report delivers — practical, actionable content
This study is structured to support near‑term and medium‑term corporate decisions rather than produce only descriptive statistics. Key deliverables contained in the full report include:
-
Transparent market sizing and forecast model (2020–2032) with scenario analysis and sensitivity testing to fuel financial planning and risk assessment.
-
Regulatory impact matrix and compliance roadmap that aligns pending and enacted energy‑efficiency rules with product development timelines across major jurisdictions.
-
Cost‑to‑serve and BOM escalation models that quantify the profit impact of raw material price swings and transportation constraints, with recommended hedging and sourcing tactics.
-
Go‑to‑market playbooks for OEMs, distributors, and system integrators covering channel strategy, specification capture, and aftermarket service expansion.
-
Technology and product prioritization guide that evaluates efficiency upgrades, VFD integration, high‑temperature materials, and explosion‑proof designs against ROI thresholds.
-
Deal pipeline and M&A screen highlighting target archetypes and integration risks for private equity or corporate strategists seeking to consolidate share or acquire capability.
-
Competitor benchmarking toolkit with qualitative and quantitative KPIs to inform pricing, warranty, and lead‑time strategies.
Market dynamics shaping supplier and buyer strategy
Three converging dynamics are most determinative for 2026 planning:
-
Regulatory acceleration: Governments and regional regulators are tightening energy performance expectations for fans and blowers. Notably, the EU ratified an updated ecodesign framework that tightens efficiency requirements in mid‑2026; in the U.S., federal rulemaking has been active but unsettled, and some federal proposals were withdrawn, increasing the importance of state‑level requirements and customer‑driven specifications. Manufacturers must reconcile global product portfolios with locally‑binding standards to avoid geo‑blocking or costly last‑minute modifications.
-
Commodity pressure and manufacturing economics: The industry’s dependence on steel, aluminum, and cast parts creates exposure to cyclical price swings. Buyers and vendors should build flexible contracts, adopt modular designs that limit bespoke castings, and consider near‑shoring options where total landed cost becomes untenable.
-
End‑user demand characteristics: Stable airflow and constant pressure remain non‑negotiable for combustion applications across boilers, furnaces, kilns, and process heating. Demand is therefore sensitive to industrial activity, energy prices, and retrofit cycles. Equipment that couples efficiency with operational controls (e.g., VFDs, digital monitoring) is gaining preferential procurement status among large industrial consumers.
Competitive landscape — strategic implications
The combustion air blower space is a mix of global technology houses, long‑established regional fabricators, and specialized builders. Our vendor assessment focuses on capability, product breadth, aftermarket strength, and execution risk.
-
The New York Blower Company — A long‑standing U.S. OEM with rugged forced‑draft designs and customization expertise. Recent capacity expansion initiatives in early 2026 demonstrate a deliberate push to reduce lead times and capture incremental demand. Their active monitoring of federal and state regulatory developments makes them an informative partner for compliance‑first customers.
-
AirPro Fan & Blower Company — Differentiates through high‑temperature capability (up to ~2,000°F), full‑system integration, and long warranties. Their engineering focus positions them well for challenging combustion environments where material selection and thermal stability are selling points.
-
Howden (Chart Industries) — Known for high‑efficiency, heavy‑duty centrifugal and axial solutions with strong engineering pedigree serving power, mining, and process industries. Howden’s scale and R&D resources support rapid customization for large projects.
-
Honeywell brands (Maxon, Hauck, Eclipse) — These product lines span compact combustion blowers to high‑capacity turbo blowers and hermetic boosters, integrating seamlessly into burner systems. Honeywell’s system advantage—particularly in burner control and combustion optimization—creates bundling opportunities for buyers seeking turnkey combustion subsystems.
-
Regional and specialty players (Twin City Fan & Blower, Atlantic Blowers, Chicago Blower, Northern Blower) — These firms offer flexible manufacturing, short lead‑time value propositions, and localized service footprints. Leadership changes and strategic investments (for example, executive appointments and plant expansions reported in 2025–2026) reflect active repositioning to capture aftermarket and retrofit work.
Recent developments to watch (selected)
-
The New York Blower Company expanded axial fan production and added industrial duct fan manufacturing in early 2026 — a tactical response to lead‑time and delivery expectations for combustion‑related equipment.
-
Regulatory monitoring statements from key OEMs during late 2025 underscore uneven federal rulemaking and heightened state and regional compliance activity; firms that maintain regulatory intelligence will have a competitive advantage in product approvals and sales cycles.
-
Executive appointments in 2025 at major regional manufacturers signal a push to professionalize operations and chase global opportunities, especially in aftermarket services and system integration.
Strategic recommendations for 2026 planning
-
Embed regulatory scenario planning into product roadmaps: map product families to a 24–36 month regulatory horizon and prioritize updates that deliver the highest delta in lifecycle cost for buyers.
-
Adopt modular design to neutralize raw material volatility: reduce dependence on bespoke castings, standardize bearing and seal platforms, and accelerate configurable assemblies to shorten lead times.
-
Commercialize service and digitization aggressively: offer condition‑based maintenance, remote diagnostics, and parts subscription models to lift aftermarket revenue and improve installed‑base stickiness.
-
Target M&A and partnerships selectively: prioritize targets that add geographic service depth, specialized high‑temperature manufacturing, or control‑system integration rather than only capacity expansion.
-
Optimize channel and specification capture: deploy technical sales tools that quantify lifetime fuel and maintenance savings from efficiency upgrades, helping procurement teams justify CAPEX.
What we’re withholding in this preview—and why
To preserve the strategic utility of our analysis for subscribing clients, this preview intentionally omits granular regional, type, and application revenue splits — the exact segmentation, customer‑level pricing curves, and model‑level margin schedules are provided in the full PW Consulting report. These detailed matrices are frequently the basis for bid/no‑bid decisions, acquisition target valuation, and product‑line discontinuation debates; hence they are distributed through controlled client access.
How to use the full report in 90 days
-
Quarter‑one capital planning: align your capital expenditures with the PW Consulting scenario that matches your demand sensitivity to energy prices and regulatory timing.
-
R&D prioritization: use the technical scoring rubric in the report to prioritize VFD‑ready platforms and high‑temperature material investments that generate the fastest payback in regulated markets.
-
Commercial execution: deploy our specification win‑book and aftermarket playbook to accelerate sales cycles by demonstrating cost‑to‑operate benefits to end users.
Closing perspective
The combustion air blower market is neither a niche nor a commodity — it sits at the intersection of industrial process reliability, regulatory pressure, and materials economics. Growth is steady, margins are recoverable with disciplined design and sourcing, and strategic positioning in service and compliance sells at a premium. For companies preparing their 2026 strategies, the choice is clear: integrate the regulatory and raw material realities now, or concede margin and timing to competitors who do.
PW Consulting’s full Industrial Combustion Air Blower Market report contains the granular segmentation, vendor financials, and executable implementation kits necessary to operationalize these insights. For access to the complete dataset and client‑only scenario tools, please visit our website or contact PW Consulting’s industrial equipment practice.
For detailed analysis of this topic, please visit the official page: Industrial Combustion Air Blower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com