

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Renewable Silica Market Poised for 18.01% CAGR Through 2032 as Tires & Rubber Demand Fuels Growth

Renewable Silica Market — Strategic Preview for 2026 Decisions
Executive snapshot
PW Consulting’s new Renewable Silica Market report (base year 2025; historical 2020–2025; forecast 2026–2032) crystallizes why renewable silica will be a boardroom-level topic in 2026. The market has moved from an early commercial phase into a rapid growth trajectory: overall market value rose markedly through the first half of the decade and reached USD 366.4 Million (2025), with a projected compound annual growth rate (CAGR) of 18.01% across the 2026–2032 forecast window. By 2032 the addressable market is forecast to exceed USD 1.16 Billion (USD Million basis).
Renewable Silica Market
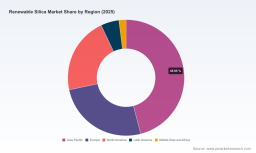
This preview outlines why that growth matters strategically, what decision-makers should prioritize in 2026, and what practical, executable content the full report delivers. We intentionally withhold the granular regional and application-level tables from this communiqué — consider this a high-fidelity trailer that demonstrates analytical depth while directing operational teams to the report portal for the full data pack and downloadable models.
Renewable Silica Market
Why 2026 is an inflection year
- Demand-side acceleration: End-markets (notably tires & rubber, specialty industrial applications, and personal/consumer segments) are increasingly valuing low-carbon, circular inputs. This is translating into accelerated procurement and specification cycles.
- Supply-side readiness: Incumbent chemical producers and a new generation of bio-focused manufacturers are scaling capacity and piloting circular production methods. Notable recent moves—both greenfield and site conversions—create options for offtake and partnership in 2026.
- Regulatory and commercial dynamics: Sustainability-linked purchasing, OEM decarbonization roadmaps, and certification frameworks (ISCC+ and similar) are maturing. These create a two-speed market between commoditized grades and premium, certified bio-circular products.
- Feedstock economics and processing: Rice husk ash has emerged as the dominant upstream feedstock in industry practice, but variability in ash quality is a material processing challenge that separates winners from also-rans.
What the report delivers — operationally relevant content
The PW Consulting report is built for decision-makers who need to act in 2026. It is not an academic exercise; it is a playbook with working tools and executable intelligence, including:
Renewable Silica Market
- Top-line market sizing and validated growth scenarios (base case, upside, downside) through 2032, with transparent methodology and sensitivity drivers.
- Dynamic cost curve models that simulate raw material, energy and conversion economics under multiple feedstock and plant-technology assumptions (financial model provided in downloadable Excel).
- Supply chain and sourcing playbooks: feedstock availability maps, preprocessing requirements, logistics stress tests and recommended contracting templates for long-term rice husk ash supply.
- Commercial go-to-market frameworks: value-based pricing guidance for premium certified grades, segmentation of commercial channels, and negotiation playbooks for OEM offtake and partnership agreements.
- Technical and product roadmaps: technology readiness assessments for precipitated and highly dispersible silica (HDS) from renewable feedstocks and recommended R&D investment allocation to achieve product parity with petro-silica.
- Competitive landscaping and M&A scorecards: profile dossiers, capability matrices, and a curated list of acquisition/prioritization targets by strategic intent (feedstock access, regional reach, technology augmentation).
- Risk matrix and mitigation templates: addressing raw material variability, regulatory shifts, logistics bottlenecks and price volatility with actionable contingency plans.
- Case studies and pilot frameworks: real-world examples demonstrating steps to reduce cradle-to-gate CO₂ footprints and ramp technical scale, plus measurement templates for sustainability KPIs.
Key market dynamics and inputs every 2026 strategy must account for
- Feedstock realities: Rice husk ash is the primary upstream feedstock in commercial renewable silica supply chains. High-purity ash commanding premium quality is available but at a differentiated cost profile; lower-grade ash presents an entry route for cost-competitive production but requires additional processing and quality control. Importantly, variability in rice husk composition is a persistent processing constraint that can erode margins unless addressed through standardized preprocessing.
- Certification and decarbonization premium: Bio-circular process claims (for example, recent producer disclosures that certain circular HDS methods can lower CO₂ emissions by roughly half compared to conventional routes) will underpin a pricing delta for certified products. Procurement teams should model this premium into TCO conversations with customers.
- Market concentration: The renewable silica industry exhibits measurable concentration among established chemical producers and a set of specialized bio-silica manufacturers. The top-three and top-five players together command a material share of the market, creating both stability in supply and strategic openings for regional challengers and integrators.
Competitive landscape — strategic read on leading players
The market is shaped by a mix of global chemical majors transitioning legacy platforms and smaller, feedstock-integrated specialists. Key strategic postures to watch in 2026 include:
- Solvay S.A.: A clear leader in turning circularity into industrial-scale product. Recent launches of bio-circular highly dispersible silica (HDS) in Europe and announced plans to extend ISCC+-certified circular production into Asia position Solvay as a commercialization- and certification-focused competitor. Strategic implication: Solvay will push the premium, certified segment and seek OEM partnerships where traceable sustainability matters most.
- Evonik Industries AG: Combining a strong precipitated silica portfolio with aggressive capacity expansion (notably a major capacity build in Charleston targeted for the green tire market), Evonik is optimizing incumbent asset footprints toward sustainability-led demand. Strategic implication: expect tight competition on product performance and scale-driven pricing in tire applications.
- Regional specialists (e.g., Blue Ocean Biotech, Brisil, Madhu Silica, and others): These players are delivering vertically integrated, feedstock-proximate solutions—often powered by green energy—and are scaling capacity quickly in rice-husk-rich geographies. Strategic implication: regional incumbents can undercut transport-dependent suppliers and are prime partners or targets for strategic alliances and consolidation.
- Emerging and niche providers: A cohort of smaller firms is developing differentiated chemistries and niche grades for personal care, food-grade and specialty coatings applications. Their value resides in product differentiation and faster innovation cycles rather than scale.
Strategic imperatives for 2026 decision-makers
For corporate leaders and business unit managers, 2026 is the year to convert market signals into concrete strategic moves. Our recommendations, grounded in the full report’s quantitative scenarios and case modeling, are:
- Secure feedstock optionality now. Negotiate staggered long-term feedstock contracts with built-in quality specifications and performance guarantees, and invest in preprocessing capacity to smooth variability in rice husk ash quality.
- Adopt a staged-capex approach. Prioritize modular, scalable plant designs that permit capacity add-ons tied to validated offtake volumes; this limits downside while capturing upside if demand ramps faster than base case.
- Differentiate via certification and product performance. Invest in ISCC+ and equivalent certification pathways, and build product-level CO₂ accounting into sales proposals to command decarbonization premiums.
- Pursue strategic partnerships over outright greenfield exposure. Joint ventures with regional feedstock owners, toll-manufacturing agreements with specialty producers, or equity stakes in high-purity ash processors are priority options to accelerate market entry with lower capital intensity.
- Build commercial flexibility. Develop a two-track commercial strategy: (a) price-competitive commoditized grades for broad industrial use, and (b) premium certified HDS/functional grades sold via long-term OEM contracts or sustainability-linked agreements.
- Institutionalize risk monitoring. Operationalize a risk dashboard that tracks feedstock quality, pricing spreads between high-purity and lower-grade ash, certification timelines, and competitor capacity announcements. Use scenario-based stress testing tied to the provided cost models.
Immediate next steps — action checklist for 2026 planning cycles
- Download the full report and Excel model to run your own cost and demand scenarios (the report contains the full regional and application-level forecast tables we withheld here).
- Run supplier due diligence on three types of counterparties: major chemical incumbents with certified offerings, regional feedstock-integrated producers, and technology licensors for HDS/precipitated silica processing.
- Initiate a pilot procurement or co-development agreement for certified product at customer scale (6–12 month pilot) with defined sustainability KPIs and offtake options.
- Plan a cross-functional 2026 workshop (procurement, R&D, manufacturing, sustainability, corporate development) to convert the scenario outputs into a prioritized investment roadmap.
Closing — why this matters and where to get the rest
The renewable silica market is maturing from pilot projects and small-scale commercialization into an investible, strategic segment with distinct winners and losers. For 2026, the decisions you make on feedstock sourcing, capacity phasing, certification investment and partner selection will determine whether your organization captures meaningful share of the premium sustainability segment or is relegated to low-margin commoditized supply.
PW Consulting’s full Renewable Silica Market report delivers the granular regional and application splits, downloadable financial models, supplier scorecards and M&A target lists that operational teams need to implement the strategies outlined above. This release is a preview: deep, actionable analysis is in the report and online data pack. Visit our report page to access the complete datasets, scenario models and execution templates.
For detailed analysis of this topic, please visit the official page: Renewable Silica Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com