

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Non‑Alcoholic Beverage Flavoring Systems Market Hits USD 5,241.15 Million in 2025, Poised for 5.82% CAGR Through 2032

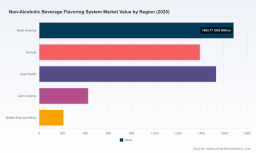
Non‑Alcoholic Beverage Flavoring System Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s latest market research report on the Non‑Alcoholic Beverage Flavoring System market delivers a pragmatic, decision‑grade toolkit for executives planning portfolios, investments, and supply‑chain moves in 2026. Built on a 2025 baseline and a 2026–2032 forecast window, the study quantifies a durable expansion trajectory (a 5.82% CAGR over the forecast period) and translates that macro momentum into operational priorities for beverage brands, ingredient suppliers, and private equity investors. This preview outlines the strategic value of the full report: the trends that will shape sourcing and innovation decisions in 2026, the competitive dynamics to monitor, and the practical playbooks included in the deliverable — while intentionally withholding the fine-grained segment figures that are available in the full report.
Non Alcoholic Beverage Flavoring System Market
Market context in a single read
The category has moved from a mid‑single‑billion‑dollar market in the early 2020s to a multi‑billion dollar industry by 2025, with continued growth expected through 2032. That expansion is not linear: it reflects a blend of product innovation, reformulation activity driven by health and labeling mandates, and shifts in consumer taste toward complex and botanical profiles. For executives, the headline takeaway is straightforward — demand and R&D investment are both accelerating in ways that favor companies with flexible formulation platforms, sustainable raw‑material access, and advanced delivery technologies.
Non Alcoholic Beverage Flavoring System Market
Why this report matters for 2026 strategy
- Translate growth into margin‑accretive moves: The aggregated market growth and forecasted trajectory provide the baseline, but the report’s proprietary scenario models show how product mix, channel shifts, and raw‑material volatility alter gross‑margin outcomes across typical beverage portfolios.
- Prioritize capex and capacity decisions: Manufacturing expansions and formulation complexity require different kinds of capital — the study maps where to invest in modular lines versus centralized concentration to balance responsiveness with scale.
- Derisk raw‑material exposure: We quantify the sensitivity of flavor‑system costs to commodity shifts (explicitly modelling citrus and botanical inputs), and provide procurement tactics that preserve clean‑label claims without eroding margin.
- Align innovation with regulatory pressure: With sugar‑reduction mandates and heightened labeling scrutiny, the report prescribes formulation pathways and validation frameworks that accelerate time‑to‑shelf while meeting compliance thresholds.
What the full report contains — practical, executable modules
The deliverable is structured as a working dossier for corporate strategy and commercial teams. Key components include:
Non Alcoholic Beverage Flavoring System Market
- Top‑line market sizing and validated forecasts (baseline 2025; forecast period 2026–2032) with scenario branching for high‑innovation and supply‑shock outcomes.
- Consumer demand maps that link sensory preferences (e.g., botanical, low‑sugar, functional) to formulation levers and price elasticity estimates.
- Technology and product playbook: encapsulation, emulsions, taste modulation, and delivery systems — when to use each, cost implications, and partner templates.
- Supplier and capability scorecards: objective evaluation criteria for sourcing discussions, including sustainability credentials, traceability, and co‑development track records.
- Manufacturing impact assessment: recommended floor plans, throughput models, and bottleneck mitigation for beverage formulators integrating complex flavor systems.
- Regulatory and labeling roadmap for major markets, with checklists for claim substantiation and evidence generation for health and natural claims.
- M&A and partnership playbook that identifies target profiles (capabilities, geographies, margin profiles) and provides valuation sensitivities linked to flavor‑system IP and formulation exclusivity.
- Interactive Excel model and downloadable data tables for internal scenario planning (note: detailed regional and application splits are available in the full report).
Drivers shaping supplier and brand strategy in 2026
- Clean‑label and naturalization: Continued consumer preference for botanical extracts and transparent sourcing is raising the bar for ingredient provenance and documentation. Natural flavoring systems now command strategic premium positioning in many portfolios.
- Functionalization and sugar reduction: Product claims tied to wellness — reduced sugar, added functionality — are prompting formulators to adopt taste modulation and alternative sweetening systems integrated with flavor delivery.
- Delivery technology as a differentiator: Encapsulation, emulsions, and other delivery innovations are shifting competitive advantage from purely aromatic expertise to system design that preserves flavor integrity across processing and shelf life.
- Raw‑material pressures: Certain core flavor inputs (for example, citrus derivatives) are part of larger commodity markets; strategic sourcing and sourcing diversification are essential to control cost and maintain product continuity.
- Consolidation vs. agility trade‑off: The market shows a mix of large, integrated suppliers and smaller, specialized houses; each archetype offers different access to scale, R&D, and customization speed.
Competitive landscape — capabilities and strategic postures
The competitive picture is characterized by a diverse mix of global flavor houses, ingredient specialists, and agile niche players. The market exhibits moderate concentration: the top three firms account for a meaningful portion of supply, while the top five extend that footprint substantially — a structure that creates both procurement leverage and opportunities for differentiated co‑development.
- Givaudan: Market leader with comprehensive flavor platforms and a strong emphasis on sustainable, clean‑label delivery systems. Best suited for large scale co‑innovation with global beverage brands.
- International Flavors & Fragrances (IFF): Strong in citrus and taste‑modulation technologies, with advanced encapsulation capabilities that address stability and sugar‑reduction use‑cases.
- Symrise: R&D‑intensive player focused on natural and functional flavor solutions; competitive where formulation complexity intersects with regulatory scrutiny.
- Kerry Group: Known for functional flavor and taste‑enhancement systems, with positioning that supports product nutrition optimization and clean‑label reformulation.
- Sensient Technologies: Specialist in delivering vivid natural profiles and flexible delivery systems, often favored by brands pursuing striking sensory differentiation.
- dsm‑firmenich: Emphasizes sustainable and performance‑driven flavor systems, attractive for brands seeking measurable environmental credentials.
- ADM and Cargill: Large ingredient integrators offering carriers, emulsions, and systems that bridge commodity supply with flavor system engineering.
- Tate & Lyle, Takasago, MANE, Döhler, Robertet: Each brings distinct advantages — from sweetening‑flavor integration to botanical expertise and manufacturing breadth. Recent examples include Döhler’s expanded capacity (facility expansion in early 2025) and Robertet’s ‘Futuring Naturals’ platform (launched 2024) — both moves that materially affect supply agility and innovation pipelines.
Strategic implications for 2026 decisions
- Procurement teams: Reframe supplier evaluation beyond unit cost — include traceability, co‑development speed, and delivery‑technology fit. Shortlist suppliers to cover both classic commodity resilience and high‑value botanical sourcing.
- R&D and NPD: Invest in taste‑modulation and encapsulation pilots to accelerate sugar‑reduced SKUs to market without compromising sensory quality. Reserve a portion of innovation budget for high‑margin botanical and functional launches aligned with consumer trends.
- Operations and capex: Prioritize modular production lines that support rapid flavor changeovers and shorter batch runs to capture premium small‑batch trends without sacrificing throughput efficiency.
- Investors and M&A teams: Look for targets that combine formulation IP with scalable delivery technology, and prioritize assets that mitigate raw‑material risk (e.g., vertically integrated botanical processors).
- Brand and marketing: Translate technical differentiators (encapsulation, clean‑label sourcing) into clear consumer narratives — playbooks in the report show how to substantiate claims while avoiding regulatory pitfalls.
Data highlights and methodological transparency
To support robust strategic choices, the study blends primary interviews, supplier audits, and bottom‑up demand modeling. Historical coverage spans 2020–2025 with a 2026 baseline and forecasts to 2032 under multiple scenarios. The report also models concentration and supplier bargaining power, enabling users to stress‑test procurement and go‑to‑market decisions. For example, the study quantifies the scale of the market in 2025 and provides forward paths under conservative, base, and accelerated innovation scenarios — details and downloadable models are included in the full package.
Actionable next steps — how to use this research in 2026
- Deploy the included Excel scenario model to simulate three product portfolio choices (premium botanical launch, reformulated mass market line, and functional water entry) and assess P&L sensitivity.
- Use the supplier scorecards as an RFP framework to compress sourcing cycles and negotiate joint development terms that align risk and reward.
- Run a 90‑day encapsulation pilot with at least two technology partners to validate shelf stability and flavor fidelity under your process conditions.
- Map your raw‑material exposure (citrus and botanical inputs) against the report’s commodity‑sensitivity model and set hedging or diversification triggers.
Closing — the hidden value
This preview surfaces the strategic vectors every executive should prioritize in 2026: naturalization, delivery‑technology, supply‑chain resilience, and portfolio bifurcation between mass and premium experiences. The full PW Consulting report contains the granular regional and application splits, supplier scorecards, scenario models, and the Excel tools that convert insight into action. For teams that must make procurement, product, or M&A decisions in 2026, the report is designed to be operational the day it’s delivered — serving both as a roadmap and as the tactical playbook you can put to work immediately.
For detailed analysis of this topic, please visit the official page: Non Alcoholic Beverage Flavoring System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com