

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Dual Band Omni Antenna Market to Grow at 7.92% CAGR Through 2032

Dual Band Omni Antenna Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
PW Consulting’s latest market study on Dual Band Omni Antennas delivers a concise, actionable bridge between radio-frequency engineering detail and boardroom strategy. Anchored on a 2025 base year and a six-year forecast horizon (2026–2032), the research quantifies the market’s expansion trajectory while translating technical trends, regulatory shifts and vendor dynamics into concrete decision levers for 2026 planning cycles. The report is presented in USD (Million) and uses a historical window from 2020–2025 to inform forward-looking scenarios.
Dual Band Omni Antenna Market
At a glance: market scale and trajectory
-
Size and momentum: The market reached USD 668.45 Million in 2025 and is projected to approach USD 1,139.68 Million by 2032, underpinned by a compound annual growth rate (CAGR) of 7.92% across the 2026–2032 forecast window.
Dual Band Omni Antenna Market -
Concentration: Aggregate market concentration is moderate — the three largest firms account for approximately 31.4% of sales, while the top five reach roughly 44.9% — signaling a market structured around several strong specialists with an active mid-tier ecosystem.
Dual Band Omni Antenna Market
Why this matters to executives in 2026
-
Investment timing: With an established growth runway and accelerating end-market adoption, 2026 is a critical inflection point. Firms that align R&D, supply chain resilience, and go-to-market specialization now will capture disproportionate share as demand expands through 2032.
-
Portfolio prioritization: Dual band omni antennas are increasingly central to Sub-6 5G densification, Wi‑Fi 6/7 indoor coverage, and M2M/IIoT connectivity strategies. Product roadmaps that address wideband MIMO performance, environmental sealing for outdoor deployments, and aesthetic in-building form-factors will be the principal differentiators.
-
Supplier and procurement strategy: Moderate market concentration suggests buyers can access differentiated technology while negotiating on lead times, warranties and integration services. Our report provides procurement playbooks and scorecards that support RF-spec compliance, vendor risk mitigation and total-cost-of-ownership modelling — essential inputs for 2026 CAPEX and vendor selection rounds.
Key market dynamics shaping decisions
-
Technology convergence: The confluence of 5G Sub-6 rollouts and Wi‑Fi 6/7 upgrades has expanded the technical requirements for dual-band omni designs — wider instantaneous bandwidth, multi-port MIMO support and lower-profile aesthetics for indoor fittings. Vendors are responding with broad frequency coverage and high-efficiency element designs that change placement and integration economics.
-
Regulatory shifts matter: Recent FCC actions on the 6 GHz band materially affect antenna and system-level planning. Rules enabling geofenced variable power (GVP) operations (effective April 2026) and expanded very-low-power (VLP) unlicensed device allowances recalibrate interference risk models for mid-band deployments and open new operational modes for enterprise-grade Wi‑Fi and private networks. Our scenario models quantify how these regulatory paths alter spectrum access, interference probability and required antenna isolation strategies.
-
Operational resilience and environmental constraints: Outdoor deployments, especially in harsh industrial and public safety contexts, are driving demand for robust, environmentally sealed omni solutions. Conversely, dense urban and in-building applications emphasize low-profile, aesthetically integrated ceiling and wall options — creating bifurcated technical specifications for system integrators and OEMs.
Competitive landscape — what to watch in 2026
-
Specialist Tactical and Rugged Players: Companies focused on defense and tactical communications continue to command premium positions where environmental sealing, frequency agility and ruggedized MIMO implementations are table stakes. Their depth in S/C-band and specialized military bands gives them a durable niche for government and unmanned systems contracts.
-
Infrastructure and Site Antenna Innovators: Vendors bringing wideband MIMO omni site antennas for 5G Sub-6 and Wi‑Fi 6/7 have accelerated roadmaps; recent product introductions underscore vendor intent to win infrastructure contracts at macro carriers and large enterprise campuses. Expect continued product cadence that blurs traditional distinctions between “site” and “in-building” omni designs.
-
Enterprise and Industrial Wi‑Fi Leaders: Firms offering integral-connector, high-performance dual-band Wi‑Fi models address the growing enterprise and industrial use cases where throughput, latency and manageability are prioritized over raw gain. Domestic manufacturing for signal-penetration-sensitive environments remains a competitive angle for some US-based suppliers.
-
Global multi-region OEMs and contract manufacturers: Asian and global OEMs supply broad product portfolios for DAS, cellular and broadband wireless. Their scale, manufacturing flexibility and cost engineering capabilities make them natural partners for large volume infrastructure programs, though differentiation will increasingly rest on integration services, testing credentials and compliance with new spectrum use cases.
Company-level insights (strategic reads)
-
Innovative product cadence: One notable supplier announced next‑generation LTM2900 Series and new MIMO omni models in March 2026, signaling aggressive moves into multi-network 5G Sub‑6 and Wi‑Fi 6E/7 segments. This kind of product cadence compresses competitive windows and raises switching costs for network operators.
-
In‑building high-capacity plays: Another firm pushed new MIMO/SISO ceiling and wall-mount models highlighted in its 2025 roadshow, demonstrating the importance of design aesthetics combined with high-frequency coverage to win enterprise retrofit projects and venue deployments.
-
Manufacturing and regional leadership: A mix of US-made manufacturers, Chinese OEMs and EU‑headquartered design firms creates a heterogeneous supplier base. Strategic buyers should weigh lead-time reliability, regulatory compliance expertise and localized service capabilities alongside unit pricing.
What the PW Consulting report delivers (practical, executable content)
-
Actionable strategy playbooks for OEMs, integrators and service providers — including R&D prioritization roadmaps, product bundling strategies for MIMO/Wi‑Fi/5G convergence, and commercial launch templates timed to regulatory milestones.
-
Procurement and integration toolkits — vendor scorecards, RF acceptance testing protocols, lifecycle cost models in USD (Million) and recommended SLA structures for 2026 sourcing cycles.
-
Regulatory impact modelling — sensitivity analyses reflecting recent FCC rulings (GVP and VLP frameworks in the 6 GHz band) and their influence on interference risk, deployment density and antenna isolation requirements.
-
Competitive benchmarking — qualitative and quantitative assessments of technology positioning, product cadence, manufacturing footprint and go‑to‑market approaches for the principal vendors active in the space.
-
Scenario-driven financial models — revenue and margin forecasts across multiple adoption curves to support strategic investments, M&A diligence and market-entry decisions through 2032.
Strategic recommendations for 2026 decision cycles
-
For product leaders: Prioritize wideband MIMO architectures that support both Sub‑6 5G and Wi‑Fi 6/7 operational modes; align upcoming releases with regulatory windows to maximize first-mover advantage for new spectrum-based features.
-
For procurement and operations: Adopt the report’s vendor scorecard and RF acceptance checklist to standardize procurement across projects — this reduces integration risk and accelerates field rollout timelines amid supply chain variability.
-
For investors and M&A teams: Target mid-tier specialists with deep domain expertise in ruggedized or in‑building omni solutions; their focused product sets and service margins are positioned to outperform as overall market volume scales.
-
For public sector and critical infrastructure planners: Incorporate FCC GVP/VLP scenario outputs into interference mitigation planning, and mandate compliance-driven antenna isolation testing in procurement specs for 6 GHz enabled systems.
Maintaining strategic optionality — the “teaser” on segmentation
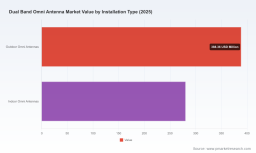
PW Consulting’s full report contains the granular segmentation, regional mixes, installation-type and application-level tables that operational teams use to size programs and prioritize field trials. Intentionally, this brief surfaces the strategic implications and macro trajectories while reserving the detailed segment-level figures, vendor scorecards and the full scenario model for the complete report. That structure ensures readers possess the strategic context needed for board-level decisions in 2026 and are motivated to obtain the complete dataset for execution planning.
Closing — action steps for 2026
As dual band omni antennas become central to multi-access edge networks, smart infrastructure and resilient industrial connectivity, 2026 will reward organizations that translate macro growth forecasts and regulatory inflection points into disciplined product roadmaps and procurement strategies. PW Consulting’s Dual Band Omni Antenna Market report—anchored by a 2025 base year, a 2026–2032 forecast and a detailed set of operational tools—equips executives to make those trade-offs with confidence. For procurement teams, product managers and investors preparing 2026 budgets and three‑year plans, the report is the operational companion to strategic intent.
To access the full set of models, vendor scorecards and segment-level tables, please refer to PW Consulting’s official market release.
For detailed analysis of this topic, please visit the official page: Dual Band Omni Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com