

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: EV DC Charge Controller Market Set to Soar from USD 520.4 Million in 2025 to USD 2,850.43 Million by 2032 at 27.5% CAGR

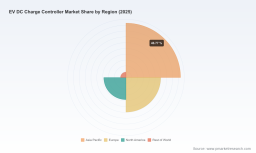
Ev DC Charge Controller Market: Strategic Imperatives for 2026 — PW Consulting Announces New Report
High-growth market, accelerating standards, and technology inflection points make DC charge controller strategy a board-level priority
PW Consulting today releases a new industry study on the Ev DC Charge Controller Market designed to equip executives with the decision-grade intelligence needed to act in 2026. Our analysis combines a detailed market sizing and forecast (base year 2025, historical series 2020–2025, outlook 2026–2032) with vendor benchmarking, scenario-driven roadmaps, and commercial playbooks that translate technical complexity into executable business choices.
Ev Dc Charge Controller Market
Why this market matters in 2026
-
Rapid expansion: After a period of exponential growth, the DC charge controller market is expected to continue expanding strongly through the forecast window. Our topline forecast shows the sector moving decisively into a scale phase as fast charging deployments and fleet electrification accelerate.
Ev Dc Charge Controller Market -
Standards-driven adoption: Regulatory mandates and standards (notably the EU AFIR timetable and ISO 15118 family, plus national implementations such as UK requirements and emerging megawatt charging specifications) are forcing product roadmaps and procurement decisions. For suppliers and buyers, compliance is now a near-term constraint and a differentiator.
Ev Dc Charge Controller Market -
Technology inflection: Power semiconductor evolution (notably silicon carbide MOSFETs) and integrated hardware-software architectures are reshaping controller design, delivering step-change efficiency and enabling new system-level propositions — from bidirectional charging to depot-grade megawatt charging.
Top-line metrics you can use now
PW Consulting’s report provides a transparent, audited market model (USD, revenue unit: Million) with historical series and a seven-year forecast horizon. Using 2025 as the analytical base, our model quantifies growth trajectories through 2032 and calculates a compound annual growth rate (CAGR) that captures the combined effect of vehicle electrification, infrastructure programs, and technology substitution. These high-level metrics are presented to help finance, product, and M&A teams stress-test scenarios and prioritize capital allocation.
What’s inside — practical deliverables
-
Actionable market sizing and forecast: validated topline and demand scenarios for 2026–2032, with sensitivity runs keyed to regulatory and supply-chain shocks.
-
Vendor playbooks and scorecards: comparative profiles, capability heatmaps, go-to-market motions, and gap analyses for leading controller suppliers and system integrators.
-
Technology adoption roadmaps: migration pathways for control architectures (integrated inlet controllers vs modular EVCC/SECC stacks), semiconductor roadmaps, and software-firmware dependency matrices.
-
Regulatory compliance checklists: stepwise requirements for ISO 15118, Plug & Charge, V2G readiness, and country-level deployment constraints so procurement and engineering teams can shorten certification timelines.
-
Commercial tools: TCO models, pricing sensitivity templates, scenarios for managed charging and energy services, and a supplier selection framework tailored to fleet, public, and depot use cases.
-
Supply-chain risk diagnostics: component concentration analysis, critical material watchlist, and mitigation levers that buyers and OEMs can action immediately.
Competitive landscape — signals, not secrets
The market sits at a middle degree of concentration: a cluster of established power-electronics and automation players leads, while specialist software and silicon-focused entrants push on system-level differentiation. Our concentration metrics highlight that leading suppliers control a meaningful share of market revenue, creating both barriers and acquisition opportunities for fast followers.
-
Phoenix Contact — Germany: Moving into systems integration with CHARX connect advanced, an approach that embeds a DC charge controller inside the CCS inlet to simplify wiring and speed vehicle integration for commercial applications. The product’s transition to series production in 2026 changes the competitive calculus for OEMs specifying integrated solutions for buses, trucks, and other heavy vehicles.
-
chargebyte — Germany: Focused on compliant communication modules (ISO 15118, DIN 70121) and compact SECC/EVCC implementations. Their strength is protocol depth and integration support for OEMs and EVSE manufacturers seeking certified stacks.
-
Vector Informatik — Germany: Offers compact controller appliances for single charge points and modular controllers for multi-point public stations; known for embedded communication stacks and engineering toolchains that accelerate product development.
-
Watt & Well — France: Emphasizes power-electronics expertise alongside SECC/EVCC controller modules, appealing to suppliers seeking high-efficiency AC/DC and DC/DC building blocks.
-
EcoG — Germany: Markets software-driven reference designs and scalable DC charge controllers that underpin many white-label charger series; their model is to enable charger OEMs with turnkey electronics and embedded firmware.
-
Delta Electronics, ABB, Siemens, Eaton, Kempower — Large incumbent OEMs with integrated chargers and mature control systems. These firms compete on scale, product breadth (from mid-power to high-power offerings), and installed service networks.
-
Tonhe Technology, PHYTEC Messtechnik — Regional and specialist suppliers focusing on modularity, embedded electronics, and developer-friendly components. Their agility matters in niche segments and rapid prototyping.
Taken together, these players represent distinct strategic archetypes: integrated system OEMs, protocol and middleware specialists, component reference designers, and nimble regional suppliers. Each archetype faces different pressures from commoditization, standards convergence, and semiconductor availability.
Key market dynamics shaping 2026 choices
-
Standards enforcement is accelerating procurement timelines. Policy moves are converting previously optional features (e.g., Plug & Charge, V2G-capable communications) into procurement checkboxes — meaning that product roadmaps delayed by a single quarter risk losing major tenders.
-
Power-semiconductor substitution is not just an efficiency story. Wide-bandgap devices enable higher power density, lower thermal budgets, and smaller cooling systems, which in turn change installation economics and lifetime service costs. Early adopters gain system-level advantage in both performance and TCO.
-
Modularity vs integration trade-offs are intensifying. Integrated inlet-controller concepts reduce installation complexity for vehicle OEMs and commercial fleets; modular controller architectures preserve serviceability and upgrade paths. The optimal choice depends on vertical (fleet vs public) and on licensing strategies for firmware and communication stacks.
-
Software and cybersecurity are moving from afterthought to profit center. Interoperability (OCPP, ISO communication layers) plus cybersecurity assurances are now differentiators in procurement scoring and in long-term service agreements.
-
M&A and partnership activity will accelerate as incumbents buy capability (protocol stacks, power-electronics IP, or regional footprint) and as investors seek to create vertically integrated charging platforms.
Executive recommendations for 2026
-
Prioritize standards-first roadmaps: Make ISO 15118/Plug & Charge and V2G compliance non-negotiable in product specs for any public or fleet-targeted equipment ordered in 2026.
-
Adopt a component-flexible architecture: Design controllers to accept next-generation power semiconductors so performance upgrades become a firmware/game-plan decision rather than a hardware rip-and-replace.
-
Build software ownership or secured partnerships: Control stacks and backend services will capture recurring revenue and be the primary means to defend installed base value.
-
Manage supply-chain concentration: Identify single-sourced risks (power modules, control SoCs) and create dual-sourcing strategies or safe-stock triggers tied to OEM production cycles.
-
Use procurement as a lever for service economics: Negotiate firmware lifecycle commitments and cybersecurity SLAs into initial purchase contracts to avoid downstream price erosion.
How PW Consulting helps
This study is intentionally operational. Beyond headline growth figures and a validated CAGR for the forecast period, the report contains procurement-ready checklists, RFP templates, and an M&A watchlist that link market intelligence to execution. If you lead product strategy, supply-chain, procurement, or corporate development, the report reduces the time from insight to contract.
For readers who want the complete dataset — detailed regional and application splits, vendor revenue mapping, and downloadable scenario models — PW Consulting invites you to review the full report and supporting data package on our website. We have designed that package to serve as the primary input to 2026 planning cycles and board-level investment debates.
Closing perspective
The DC charge controller market is no longer a niche enabler; it is a gatekeeper to broader e-mobility value chains. By 2026, decisions on standards compliance, semiconductor strategy, and software architecture will determine who captures recurring energy-management revenues and who competes on price. PW Consulting’s Ev DC Charge Controller Market report equips decision-makers to navigate these choices with confidence — combining macro clarity with operational depth, while preserving the granular datasets that underpin strategic moves.
For detailed analysis of this topic, please visit the official page: Ev Dc Charge Controller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com