

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Edge Computing Chips to Surge at 24.0% CAGR, Reaching USD 85.9B by 2032 as AI Accelerators Lead a $7.64B Segment

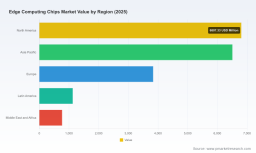
Edge Computing Chips Market 2026: Strategic Imperatives from PW Consulting’s New Market Study
As enterprises finalize strategic plans for 2026, the Edge Computing Chips market is emerging as a decisive battleground for competitive differentiation. PW Consulting’s latest market research — anchored on a 2025 base year and a 2026–2032 forecast horizon — underscores that edge compute silicon is no longer a niche adjunct to cloud AI: it is becoming a core architecture decision that shapes product roadmaps, supply chains, and regulatory compliance strategies. Our top-line model projects continued rapid expansion driven by on-device AI, industrial digitization, and the proliferation of real‑time, privacy-preserving inference. The market grows from an estimated USD 19,050 million in 2025 to a multi-fold larger opportunity by 2032, underpinned by a compound annual growth rate of 24.01% across the forecast window.
Edge Computing Chips Market
Why this report matters for 2026 decision-makers
- Strategic timing: 2026 is a year of inflection — next-generation edge processors, expanded product SKUs from established suppliers, and regulatory shifts will collectively determine who can supply global scale.
- Investment prioritization: Buyers and investors need frameworks to distinguish between application-driven silicon choices (ultra-low-power neuromorphic vs. high-throughput NPUs vs. general-purpose SoCs) and to quantify total cost of ownership across device lifecycles.
- Supply-risk mitigation: Advanced packaging and high-bandwidth memory capacity are key chokepoints; procurement and product teams must incorporate supplier and materials risk into 2026 sourcing strategies.
Top-line market context (high level)
Our historical analysis maps a pronounced acceleration between 2020 and 2025 as edge workloads shifted from experimental to mission-critical. Looking ahead to 2026 and beyond, the model anticipates continued double-digit expansion with material upside from new product families targeting vision, robotics, industrial control, and on-device generative AI inference. While the report provides a full time-series market build, strategic readers should note the magnitude of change from 2025 to 2032 — a trajectory that demands both technology bets and supply-chain hedging now.
Edge Computing Chips Market
Report scope and practical deliverables
This study is built to be operationally actionable for C-suite and product leaders. Key outputs include:
Edge Computing Chips Market
- Executive dashboards showing market size and growth scenarios (base, conservative, and upside) to support 2026 budgeting and M&A screening.
- Technology roadmaps that map edge chip architectures to specific use cases (vision pipelines, low-power always-on sensing, real-time control, large-model inference at the edge) and recommended selection criteria for each.
- Supplier due-diligence templates and a vendor capability matrix comparing NPU/accelerator performance, power envelopes, software ecosystems, and lifecycle support.
- Total cost of ownership (TCO) models that include silicon cost, integration, OTA/security update obligations, and expected field maintenance across multi-year deployments.
- Go-to-market playbooks for device OEMs and systems integrators: prototyping guidance, certification checkpoints, and partner selection checklists.
- Regulatory impact assessment focused on export-control regimes, data residency issues, and standards alignment (including implications of industrial digital-twin standards).
Competitive landscape — who matters and why
The market remains concentrated among a small set of platform players and a vibrant cohort of specialist startups. Our CR metrics indicate material concentration at the top, reflecting the emergence of integrated ecosystem plays that combine silicon, software stacks, and developer tools. Key strategic positions include:
- NVIDIA Corporation — A leader for high-throughput edge AI, offering compact, power-optimized systems that make it straightforward to deploy advanced inference in robotics and healthcare. NVIDIA’s edge platform approach continues to attract partners focused on accelerated vision and autonomous applications.
- Intel Corporation — Bringing a broad portfolio that targets both high-performance and long-lifecycle industrial use cases. Intel’s edge strategy leans on integrated NPUs in combination with CPU and GPU stacks to support mixed workloads and real-time control.
- Qualcomm Technologies, Inc. — Strong in low-power, connected edge devices, particularly where 5G integration and battery efficiency are critical. Qualcomm’s emphasis on secure, on-device inference keeps it central to IoT and mobile-adjacent edge markets.
- Advanced Micro Devices (AMD) — Competing where high-performance compute meets adaptable fabric and accelerator integration; well positioned for vision and embedded HPC at the edge.
- Specialists and innovators (Hailo, Ambarella, BrainChip, others) — These firms push architectural diversity — neuromorphic processing, dedicated vision SoCs, and ultra-efficient inference cores. Their innovations create differentiated options for OEMs seeking extreme power efficiency or unique on-device learning capabilities.
- Platform and OEM silicon (MediaTek, Samsung, Apple, Google) — Major SoC providers continue to embed robust NPUs and create vertically integrated products where AI experiences are tightly coupled with hardware and OS optimizations.
- Industrial-focused semiconductor vendors (STMicroelectronics, NXP, Texas Instruments) — Targeting low-power real-time control, safety criticality, and long product lifecycles required by industrial and automotive markets.
Recent vendor moves are already reshaping supplier selection dynamics: Ambarella’s CV7 family expands high-resolution multi-stream vision capabilities; BrainChip’s funding and public demos underscore commercial momentum for neuromorphic approaches; Qualcomm’s Dragonwing expansion reinforces its leadership in connected, power-efficient edge SoCs. Each of these developments alters procurement timelines and architectural trade-offs for 2026 deployments.
Regulation, standards, and supply bottlenecks — implications for strategy
- Export controls and licensing: New policy calibrations on advanced computing exports, including case-by-case review criteria introduced by regulatory authorities in early 2026, mean that global sourcing and design partnerships must be assessed against licensing risk and end‑use certification requirements. This impacts where and with whom companies can manufacture, integrate, and deploy certain high-performance components.
- Standards convergence: Industrial frameworks that incorporate edge compute — such as digital twin standards — are driving requirements for deterministic latency, data models, and interoperability, which influence chip selection and software stack investments.
- Materials and packaging constraints: Availability of advanced memory (HBM) and advanced packaging capacity remains a principal bottleneck for high-performance edge processors. Procurement strategies must therefore combine long-term supply agreements, phased roll-outs, and design flexibility to accommodate alternative memory and packaging options.
Actionable strategic recommendations for 2026
- Align chipset selection to the highest-value differentiator in your product: power efficiency, inference throughput, or integration with connectivity/sensors. Use our selection matrix to score alternatives on technical and commercial criteria.
- Stress-test supply chains against advanced packaging and memory scarcity scenarios; establish multi-sourced BOMs and prioritized production schedules for flagship SKUs.
- Integrate export-control compliance into vendor contracts and design-in flows, especially for products targeting cross-border deployments or geographies subject to tighter license regimes.
- Invest in software portability (abstraction layers, model quantization pipelines) to reduce lock-in and accelerate migration between architectures as supplier landscapes and prices evolve.
- Consider staged compute distribution: keep latency-sensitive layers at the edge while offloading training or heavy model refinement to the cloud, optimizing costs and compliance simultaneously.
How enterprises should use this research
PW Consulting designed this study to be both a strategic compass and a practical toolkit for 2026. Leadership teams will find the forecast scenarios, supplier assessments, and TCO models useful when making capital allocation decisions, constructing proof-of-concept roadmaps, and prioritizing partnerships. Product and engineering functions can use our implementation playbooks to accelerate MVP timelines while minimizing integration risk. And procurement and legal teams will benefit from our regulatory impact analysis and contracting templates to lock in supply while remaining compliant.
Methodology and credibility
Our market sizing blends bottom-up build models, primary supplier and OEM interviews, device-level BOM analysis, and demand-side adoption curves across industrial, automotive, consumer, healthcare, and infrastructure verticals. We overlay supply-chain capacity analysis and regulatory scenario stress tests to create three forward-looking demand pathways. Full methodological notes, interview lists, and a transparency matrix are included in the complete report so that internal teams can replicate assumptions for their bespoke business cases.
Final note — a “trailer” of depth
This briefing surfaces the strategic contours that will matter in 2026: rapid market expansion, concentration among platform leaders, meaningful opportunities for specialized architectures, and persistent supply and regulatory headwinds. PW Consulting’s full report contains the granular dashboards, supplier scorecards, downloadable datasets, and decision-ready templates that boards and product teams need to act. To preserve the competitive value of our proprietary segment-level intelligence, this release intentionally highlights high-level trends while directing practitioners to the report portal for the comprehensive, actionable detail required to inform 2026 capital and product decisions.
For access to the full Edge Computing Chips Market report, including executive summaries, downloadable datasets, and client advisory options, visit PW Consulting’s report page or contact our industry practice lead for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Edge Computing Chips Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com