

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts 6.04% CAGR for Fire Retardant Clothes Market Through 2032

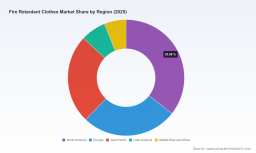
Fire Retardant Clothes Market — Strategic Preview for 2026 Corporate Decisions
PW Consulting’s latest market study on the Fire Retardant Clothes market (base year: 2025; forecast 2026–2032) distills the operational intelligence that senior leaders will need to navigate supplier disruption, regulatory shock, and product premiumization in 2026. The global market reached approximately USD 5.25 billion in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of about 6.0% in the coming seven years. Our analysis combines demand-side enforcement trends, raw-material dynamics, and competitor motion to produce a decision-ready playbook for procurement, product, and M&A teams.
Fire Retardant Clothes Market
Why 2026 is a Pivotal Year
Two pressures collide in 2026: tighter regulatory guardrails and an accelerating shift in buyer behavior from task-based to daily-wear flame-resistant (FR) garments. Standards-setting bodies updated testing and contamination controls in 2025, introducing restrictions on persistent substances and elevating ensemble-level performance tests. At the same time, enforcement across heavy-industry sectors is pushing organizations to specify FR garments as mandatory daily PPE rather than occasional protection. These forces increase the total addressable market and raise the bar on supplier selection, testing regimes, and lifecycle cost analysis.
Fire Retardant Clothes Market
From a market perspective, this shift shows up as steady, sustained growth rather than a short-term spike: after climbing from roughly USD 3.95 billion in 2020 to USD 5.25 billion in 2025, the market is projected to continue expanding throughout the 2026–2032 forecast window. Concentration remains moderate: the top three players do not control the market, and the top five account for less than half of total revenue—conditions that favor targeted consolidation, specialist partnerships, and vertical integration by established players.
Fire Retardant Clothes Market
Macro Dynamics Shaping Strategy
-
Regulatory tightening: Recent updates to firefighter and industrial PPE standards introduce PFAS-related restrictions and new ensemble testing requirements. Buyers will need evidence of compliance across aspects that extend beyond flame performance — including contaminant removal, breathability, and particulate management — making third-party testing and traceable supply chains a procurement imperative.
-
Material premiumization: Advanced aramid-based fibers remain the technical gold standard for high-heat, arc, and flash-fire exposure. Their performance advantages make them the preferred choice for high-risk industries, while treated-cotton and other lower-cost options retain share in lower-exposure use cases. Expect pricing dispersion and margin pressure for manufacturers who cannot substantiate performance with certified test data and lifecycle cost models.
-
Wear-model transition: Mandates and insurer expectations are driving organizations toward daily-wear FR programs. This changes procurement from a transactional, task-specific buy to a programmatic supplier relationship with service components—garment tracking, laundering standards, and replacement cadences become competitive differentiators.
-
Supply-chain resilience: Raw material sourcing (span from specialty aramids to treated textiles), capacity constraints at fiber producers, and regional compliance differences create friction that rewards multi-sourcing and nearshoring strategies for critical items.
What PW Consulting’s Report Delivers (Practical, Executable Content)
-
Actionable go-to-market playbooks for manufacturers and distributors: SKUs to prioritize, service bundles that drive stickiness, and channel strategies for industrial vs. municipal buyers.
-
Procurement levers and cost-to-serve models: A supplier scorecard calibrated for regulatory compliance, testing throughput, lead-time variability, and total lifecycle cost—designed for sourcing teams to reduce TCO without compromising safety.
-
Compliance roadmap templates: Year-by-year implementation plans that align product development, testing, and documentation with the updated PPE standards, including a checklist for PFAS reporting, ensemble testing, and traceable material declarations.
-
Product and materials decision matrix: Frameworks to decide when to specify inherent high-performance fibers versus treated substrates, balancing exposure profile, user acceptability, and unit economics.
-
Competitive battlegrounds and M&A checklist: Playbooks for bolt-on acquisitions, strategic partnerships, and divestitures—plus a rapid valuation checklist for targets in textile finishing, testing labs, and specialty-fiber distribution.
-
Scenario-driven forecasts and stress tests: Demand scenarios that model regulatory tightening, commodity-fiber shocks, and accelerated wear-pattern adoption to stress-test capital and inventory plans.
Competitive Landscape — What Leaders Are Doing Now
The market features a mix of material innovators, specialty apparel brands, and global PPE conglomerates. Several public and private players set distinct strategic templates that others can emulate or counter:
-
Material innovators: Firms with proprietary aramid and PBI fibers (historically led by legacy material firms) continue to command technical trust with end users in oil & gas, utilities, and emergency response. Their strategic asset is an R&D-to-certification pipeline that shortens time-to-acceptance for new chemistries and blends.
-
Specialist manufacturers and brands: Producers that translate high-performance fabrics into fit-for-purpose garments (coveralls, jackets, arc suits) are moving up the value chain by bundling testing data, certification documentation, and managed replenishment services.
-
Large PPE conglomerates: These players compete on scale, global distribution reach, and integrated offerings across gloves, eyewear, and apparel. Recent acquisitions in adjacent PPE categories demonstrate appetite for cross-selling and margin accretion through portfolio rationalization.
Notable corporate moves and implications:
-
Acquisitions by safety specialists to broaden product portfolios (most notably in 2024–2025) underscore a consolidation trend: buyers increasingly prefer suppliers who can deliver end-to-end PPE solutions and validated lifecycle services.
-
Standards updates that took effect in 2025 raise entry barriers for vendors without modern testing capability or transparent material declarations. Firms that invested early in lab throughput and traceability are converting compliance into a competitive moat.
Strategic Imperatives for Executive Teams in 2026
-
For manufacturers: Prioritize certification workflows and customer-facing data. Investing in in-house or dedicated third-party testing, establishing faster re-cert pipelines, and offering compliance-as-a-service will accelerate win rates with large industrial accounts.
-
For distributors and channel partners: Transition from SKU-led sales to solution-selling—bundle garments with laundering protocols, replacement guarantees, and digital asset management (e.g., garment lifecycle tracking) to increase account retention.
-
For buyers (large industrials and utilities): Adopt a programmatic sourcing model that emphasizes supplier redundancy for high-risk SKUs, clarity on lifecycle cost, and contractual clauses for regulatory change compliance. Build a prioritized list of certified suppliers and require documented supply continuity plans.
-
For investors and M&A teams: Target capability gaps—testing capacity, specialty finishing, and regional manufacturing nodes. The market’s moderate concentration means well-executed bolt-ons can yield rapid share gains without bidding wars for the market leaders.
How to Use This Preview — Where PW Consulting Adds Immediate Value
This executive preview surfaces the strategic inflection points: regulatory change, material economics, and wear-model transformation. The full PW Consulting report converts these points into tactical instruments: detailed supplier scorecards, procurement templates, SKU-level margin impact models, and prioritized action lists for compliance and product development teams.
We intentionally withhold granular segment-level figures and scenario tables in this preview to preserve the operational exclusivity clients rely on when making procurement, product, and M&A decisions. The full report contains the complete segmentation, unit economics by material class, pricing sensitivities, and regional demand scenarios that underpin the forecasts and recommended actions summarized here.
Conclusion — The Practical Decision Edge for 2026
Corporate leaders face a clear set of choices in 2026: invest to meet higher compliance standards and convert that investment into differentiated, higher-margin offerings; or compete on price in an environment where supply volatility and regulatory risk can quickly erode margins. PW Consulting’s report equips decision-makers with the models, supplier assessments, and execution roadmaps to tilt that choice toward sustainable advantage.
For stakeholders ready to translate these strategic insights into procurement actions, product investments, or M&A moves, PW Consulting’s full market study provides the necessary empirical backbone and playbooks. Visit our report portal to access the complete dataset, scenario models, and implementation templates that underpin this executive preview.
For detailed analysis of this topic, please visit the official page: Fire Retardant Clothes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com