

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Pimple Patches Market to Grow from USD 840.5 Million in 2025 to USD 1,487.79 Million by 2032 at an 8.5% CAGR

Pimple Patches Market — Strategic Outlook for 2026: Actionable Intelligence from PW Consulting
PW Consulting’s latest market study on the global pimple patches market delivers an evidence-based strategic playbook designed to inform boardroom-level decisions throughout 2026. Built on a robust historical series and a forward-looking forecast, the report quantifies the sector’s growth trajectory (CAGR 8.5% over the forecast horizon) and translates that trajectory into practical choices for product, manufacturing, channel and regulatory strategy. This press briefing highlights the report’s strategic value without divulging the granular segmentation tables reserved for subscribers and clients.
Pimple Patches Market
Why 2026 Is a Pivotal Year for Players and Investors
After several years of steady expansion, the pimple patches market has entered a phase where technology, channel dynamics, and regulatory clarity are converging to reshape competitive advantage. Innovation pipelines are producing differentiated patch technologies (from advanced hydrocolloid matrices to microneedle and dual-action designs), while consumer preferences increasingly reward clean-label formulations and sustainability. At the same time, regulatory regimes are tightening in major markets, creating both barriers and value-creation opportunities for manufacturers who can demonstrate compliant production and clear claims architecture.
Pimple Patches Market
For decision-makers, the headline market metrics matter: the market shows sustained mid-single-digit to high-single-digit growth through the next decade, supporting an investment thesis grounded in steady demand expansion rather than speculative hype. That steady expansion elevates the importance of strategic choices—what product platforms to back, where to localize manufacturing, how aggressively to pursue private label contracts, and which channel investments will compound returns most effectively.
Pimple Patches Market
Report at a Glance: What PW Consulting Provides
- Proven market-sizing methodology: A reconciled model covering historical performance and an explicit forecast period to 2032, enabling scenario analysis under multiple macroeconomic and channel-shift assumptions.
- Demand-driver diagnostics: Segmentation by product platform, distribution channel and region (high-level), identifying where premiumization and claim-led formulations are accelerating ARR and margin expansion.
- Competitive and supplier intelligence: Profiles and capability matrices for brand leaders, manufacturers, and OEM/ODM partners—plus an assessment of industry concentration and competitive defensibility.
- Regulatory and compliance playbook: Clear guidance on how different claim sets map to regulatory regimes and manufacturing requirements, with stepwise checklists for FDA-classified devices versus cosmetic claims.
- Commercial playbooks and go-to-market tools: Channel-entry frameworks, pricing benchmarks, private-label playbooks, partnership negotiation templates, and a ready-to-use financial model with sensitivity toggles.
- Actionable M&A & partnership scoring: A stratified target list and integration checklist focused on bolt-on technologies, regional manufacturing capacity and route-to-consumer capabilities.
Strategic Imperatives for 2026
- Prioritize platform differentiation: Companies should select 1–2 technology platforms (e.g., advanced hydrocolloids, microneedle arrays, or drug-eluting hybrids) to pursue from an R&D and IP-protection perspective. The most value-accretive opportunities sit at the intersection of demonstrable clinical benefit and consumer-friendly form factors.
- Design claims with regulatory clarity: The distinction between cosmetic positioning and medical device claims materially affects manufacturing requirements, labeling, and commercialization timelines. Teams should map intended claims to regulatory class early and budget for the facility registration, testing, and documentation that accompany device classifications.
- Embed supply-chain resilience: Hydrocolloid films and adhesives remain critical inputs; manufacturers should implement dual-sourcing strategies, inventory buffers and qualified local suppliers in priority markets to de-risk lead times and cost shocks.
- Operationalize sustainability: Sustainable materials and recyclable packaging are no longer optional for premium positioning. Brands that embed measurable environmental improvements into product roadmaps unlock both consumer preference and preferred retail placement.
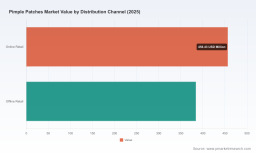
- Optimize channel allocation: Digital channels will continue to carry incremental volume and higher-margin DTC sales, but a blended channel strategy—balancing online discovery with offline availability and professional endorsements—creates the most defensible growth path.
- Evaluate portfolio M&A and partnerships: Given moderate industry concentration, targeted acquisitions (technology, regional manufacturing, or brand extension) can accelerate scale without lengthy organic build-outs.
Competitive Landscape: Who Matters and Why
The market comprises category specialists, established skincare brands, and technical manufacturers. PW Consulting’s competitive review highlights the different strategic plays available to entrants and incumbents:
- Hero Cosmetics (New York, NY, USA) — Offers a best-known hydrocolloid patch product focused on rapid blemish absorption and overnight results. ( https://www.herocosmetics.us)
- COSRX (Seoul, South Korea) — Brings dermatology-adjacent credibility and a multi-size hydrocolloid offering aimed at routine acne care. ( https://www.cosrx.com)
- Starface World Inc. (New York, NY, USA) — Positions pimple patches as visible, lifestyle-forward accessories, leveraging brand personality to drive viral adoption. ( https://starface.world)
- Rael (USA) — Focuses on invisible and medicated hydrocolloid solutions within a clean-beauty narrative. ( https://www.getrael.com)
- ZitSticka (USA) — Invests in microneedle and targeted-delivery platforms, pursuing a higher-ASP, tech-led segment. ( https://zitsticka.com)
- Peace Out Skincare (USA) — Emphasizes spot-treatment kits and bundled solutions for consumer convenience. ( https://peaceoutskincare.com)
- DERMATECH (South Korea) — OEM/ODM partner with custom hydrocolloid, hydrogel and microneedle manufacturing capabilities, key for private-label scale-ups. ( https://www.dermatech.life)
- Lessonia (France) — European manufacturer specialized in advanced absorbent matrices and transparent films, useful for local supply-chain strategies. ( https://www.lessonia.com)
- Peter Thomas Roth Labs LLC (USA) — Dermatologically-positioned brand leveraging clinical trust and skincare distribution. ( https://www.peterthomasroth.com)
Our competitive concentration analysis indicates a moderately consolidated market: the top three and top five firms together hold meaningful, but not overwhelming, shares—enough that scale matters, but niches remain accessible to well-capitalized challengers with technical differentiation.
Recent Industry Developments with Strategic Implications
- New microarray innovations (dual-phase antibacterial and anti-inflammatory self-locking designs) point to a near-term commercialization wave—early adopters who secure manufacturing partnerships will gain first-mover advantages in clinical efficacy claims.
- Localized manufacturing expansions (e.g., increased European output from regional manufacturers) reduce lead times and support “Made in” claims for premium positioning—important for retailers and regulators focused on supply provenance.
- Active participation by OEM/ODM partners at trade events signals that private-label demand and custom co-development pipelines are accelerating; brands should evaluate flexible production contracts to capture this trend while controlling CAPEX.
Regulatory and Operational Risk Matrix
Regulation is a central determinant of go-to-market strategy. In key markets, patches that make active acne treatment claims or contain drug ingredients fall under medical device classifications and require facility registration, device listing and associated quality systems. In contrast, hydrocolloid patches marketed solely for cosmetic purposes follow a different compliance path. This bifurcation affects timing, cost, and the nature of permissible claims in advertising—factors that directly influence expected ROI and launch sequencing.
Operational risks also cluster around raw materials and sustainability expectations. Hydrocolloid film and adhesive inputs are strategic bottlenecks; companies without qualified alternative suppliers face production interruptions and margin pressure. At the same time, consumers and retailers increasingly expect lifecycle disclosures and lower-plastic packaging, forcing product and cost trade-offs that must be modelled explicitly.
How to Use This Research in 2026 Decision-Making
- New product development: Use our platform prioritization matrix to select technology bets and to size R&D investment versus expected margin uplift.
- Manufacturing siting: Apply the PW Consulting supplier scorecard and CAPEX model to choose between building in-house, partnering with OEM/ODM firms, or leveraging contract manufacturing for speed-to-market.
- Commercial expansion: Leverage channel elasticity analyses to allocate marketing spend efficiently between DTC growth and retailer penetration.
- M&A and partnership diligence: Use our valuation sensitivity scenarios and operational fit criteria to evaluate acquisition targets and alliance candidates.
- Regulatory planning: Follow our step-by-step compliance checklist to align product claims with the required regulatory pathway and to plan clinical or analytical studies where necessary.
Next Steps and Access to the Full Intelligence
This briefing outlines the strategic contours of the pimple patches market and the tactical choices leaders must make in 2026. PW Consulting’s full report contains the granular segmentation, regional and channel breakdowns, pricing curves, supplier scorecards, and the downloadable financial model that are essential for transaction execution and operational planning. To access the complete dataset, competitive scorecards, and bespoke consulting options, please visit PW Consulting’s official report page or contact our market access team for a tailored executive briefing.
In an evolving category where product science, supply-chain resilience and regulatory positioning all interact, the right intelligence—translated into decisive action—separates sustainable winners from short-lived entrants. PW Consulting’s pimple patches market study is designed to provide that intelligence and to equip leadership teams with the tools needed to operationalize strategy throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Pimple Patches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com