

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Elevator & Elevator Control Market Valued at USD 105.42 Billion in 2025, Poised to Reach USD 153.35 Billion by 2032 at a 5.51% CAGR — Asia‑Pacific Leads with USD 51.51 Billion

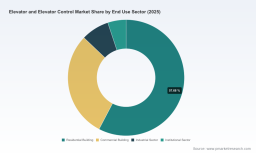
Elevator And Elevator Control Market — Strategic Outlook 2026: PW Consulting's Essential Brief for Decision Makers
Executive summary
The global elevator and elevator control market reached approximately USD 105,420 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of roughly 5.51% over the 2026–2032 forecast window, driven by modernization demand, rising high‑rise construction in emerging cities, and accelerating adoption of energy‑efficient, connected control systems. By 2032 the market is expected to surpass USD 150 Billion under our central forecast, while market concentration remains meaningful — the top three players account for a substantial share and the top five consolidate a clear majority — shaping competitive dynamics across new installs, modernization and services.
Elevator And Elevator Control Market
Why this report matters for 2026 decisions
-
CapEx and Portfolio Planning — our forecast and scenario models let CFOs and portfolio managers stress‑test capex allocations across new build vs. modernization and services, under multiple demand and raw‑material price trajectories.
Elevator And Elevator Control Market -
Product Roadmaps — R&D and product leaders can prioritize investments in controls, regenerative drives, and modular platforms by aligning feature roadmaps to projected adoption curves for smart controls and energy mandates.
Elevator And Elevator Control Market -
M&A and Partnerships — our competitive intelligence identifies high‑value acquisition archetypes (regional service networks, controls suppliers, niche modernization specialists) and quantifies the strategic upside under aggressive and conservative consolidation scenarios.
-
Supply‑chain & Procurement Strategy — procurement teams receive a practical toolkit to hedge raw‑material exposure, negotiate component contracts, and design dual‑sourcing strategies for key drive and motor components.
-
Regulatory Compliance & Risk — compliance leaders get a roadmap to implement ASME A17.1/CSA B44 2025 updates and to prepare for the transition toward new ISO 8100 standards, minimizing certification lag and deployment friction.
Key market dynamics shaping strategy in 2026
-
Standards and Certification Shock — 2025–2026 delivers a refresh in normative architecture: North America’s ASME A17.1/CSA B44 updates and the publication of ISO 8100‑1/2 are changing component, validation and documentation requirements. Organizations that pre‑emptively align product lifecycles and test protocols will avoid costly retrofit cycles during certification windows.
-
Technology Convergence — IoT, edge analytics and redundant safety controllers are shifting buyer preference from commodity lifts to intelligent, service‑backed platforms. Energy recovery, predictive maintenance and secure connectivity are increasingly baseline demands for commercial and institutional customers seeking lifecycle cost reductions.
-
Modernization as Margin Engine — aging installed bases in mature markets are unlocking a multi‑year retrofit opportunity. Firms that convert field service teams into consultative modernization specialists are realizing higher margins and stronger client retention than those selling replacement units alone.
-
Raw‑material and component volatility — upstream inputs remain a material driver of manufacturing cost. Steel and iron‑ore price movements, while moderating from 2025 highs, continue to influence tender dynamics and push OEMs toward design choices that reduce steel intensity and simplify assemblies.
-
Consolidation and Differentiation — concentration among leading OEMs gives scale advantages in global service networks, while regional and component suppliers retain pockets of specialization. The market rewards firms that combine product innovation with scalable service delivery.
Competitive landscape — what we analyzed
Our market view synthesizes public filings, product launches, facility investments and proprietary channel checks to map strategy across OEMs, component suppliers and regional champions. Major global OEMs continue to bifurcate along two strategic axes: platform innovation and service expansion.
-
Platform innovation leaders (example profiles): companies with broad product portfolios and heavy R&D investment are advancing energy‑efficient drives, dual‑channel safety controllers, and specialized models for mission‑critical environments. Recent product introductions targeted at data centers and energy‑efficient urban towers illustrate a push into higher‑value segments.
-
Service and modernization leaders: incumbents with dense service networks are bundling digital maintenance, predictive diagnostics and staged modernization offers to convert recurring revenue into predictable cash flows. New modular modernization packages are already shortening sales cycles in mature markets.
-
Component and control specialists: motor and drive suppliers remain pivotal to performance and reliability. A shift toward smart, software‑enabled control modules is opening opportunities for suppliers able to offer integrated hardware‑software stacks and scalable cybersecurity features.
-
Regional challengers: competitive pressure from regional manufacturers and low‑cost suppliers is intensifying for new installs, particularly in price‑sensitive segments. However, these players are also increasingly moving up the value chain by adding controls and service capabilities.
Notable corporate moves we tracked include launches of heavy‑duty and modular modernization product lines, facility expansion to accelerate next‑generation development, and new safety and energy innovations. These moves are consistent with the market’s twin focus on energy efficiency and lifecycle serviceability — two themes we expect to dominate boardroom agendas in 2026.
What the PW Consulting report delivers — practical, actionable content
-
Robust sizing & forecasting framework: historical baseline (2020–2025), base year 2025, and a transparent forecast (2026–2032) with scenario variants (baseline, upside, downside) and sensitivity levers for raw material prices and construction starts.
-
Segment playbooks: go‑to‑market strategies for new installs, modernization, and elevator control systems, including sales channel economics, pricing levers, retrofit bundling and service KPIs.
-
Technology & product roadmap guidance: decision frameworks to prioritize investments in IoT, redundancy safety architectures, regenerative drives and machine‑room‑less deployments.
-
Regulatory impact assessment: practical checklists to implement ASME and ISO transitions, test plan templates and compliance cost estimates to minimize time‑to‑market disruption.
-
Supply‑chain and cost modeling: component bill‑of‑materials analysis, steel and motor cost sensitivity models, and procurement strategies to mitigate price volatility and supplier concentration risk.
-
Competitive diagnostics: benchmarking of product portfolios, service coverage maps, and proprietary company scorecards that highlight strategic strengths and vulnerability vectors (product gaps, service density, tech bets).
-
M&A and alliance playbook: target archetypes, value creation roadmaps for tuck‑ins, and integration checklists to capture synergies in services, controls and regional presence.
Priority recommendations for 2026
-
Operationalize modernization as a distinct P&L: create dedicated product, sales and delivery teams for staged modernization packages; price to outcomes, not parts.
-
Make controls a strategic asset: invest in control‑software IP, cybersecurity and edge analytics to convert device telemetry into recurring subscription revenues.
-
Design for lower steel intensity: pursue structural and material engineering choices that reduce dependence on volatile steel inputs and shorten lead times.
-
Prepare for standards transitions today: accelerate validation and documentation processes to avoid bottlenecks when new ISO and regional codes come into force.
-
Hedge supply risk selectively: implement dual‑sourcing for motors and drives and explore nearshoring for critical components in high‑value markets.
-
Prioritize bolt‑on M&A for service density: acquire regional service networks and controls specialists to expand coverage and speed deployment of digital maintenance programs.
-
Pilot data‑monetization: run 2–3 scalable pilots that demonstrate predictive maintenance economics to key enterprise customers within 12 months.
How to use this research in 90 days
-
Decision sprint (0–30 days): align executive stakeholders on scenario outcomes and immediate cost exposures; run a procurement stress test against our raw‑material sensitivity model.
-
Implementation planning (30–60 days): prioritize product and service initiatives using our segment playbooks; allocate R&D and pilot budgets accordingly.
-
Execution & validation (60–90 days): launch one modernization pilot, finalize supplier contracts with hedges, and set a roadmap for compliance actions tied to the new ISO/ASME timelines.
Next steps
This briefing outlines the high‑value strategic takeaways from PW Consulting’s full Elevator And Elevator Control Market report. For the complete dataset — including segment‑level forecasts, market‑share matrices, company scorecards, and the detailed playbooks and templates referenced above — access the full report. The report is designed to be both a strategic compass and an operational manual for 2026 boardrooms seeking to convert market momentum into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Elevator And Elevator Control Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com