

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Web Conversational AI Platforms Set to Soar at a 22.98% CAGR Through 2032

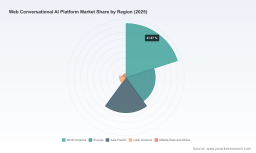
PW Consulting Releases 2026 Intelligence Brief: Web Conversational AI Platform Market — Strategic Roadmap for Enterprise Decision‑Making
Executive snapshot
PW Consulting today publishes its latest market intelligence brief on the Web Conversational AI Platform Market, delivering a focused, action‑oriented guide for C‑suite and technology leaders planning investments and transformations in 2026. Built on a five‑year historical lens and a seven‑year forecast horizon, the study uses 2025 as its base year and projects the market through 2032. Our analysis shows a sustained, high‑growth trajectory: the market has expanded rapidly since 2020 and is forecast to continue compounding at a robust 22.98% CAGR through the 2026–2032 period, reaching multi‑billion dollar scale by the end of the forecast.
Web Conversational Ai Platform Market
Why this report matters for 2026 decisions
-
Timing: 2026 is the inflection year for many enterprise pilots to transition to scale. Capital allocation, platform selection, and procurement cadence made now determine total cost of ownership and competitive advantage through 2032.
Web Conversational Ai Platform Market -
Risk and resilience: Energy, regulation, and data‑residency constraints are rapidly reshaping operational models for AI platforms—this report surfaces the practical controls and contractual clauses procurement teams must insist upon.
Web Conversational Ai Platform Market -
Vendor dynamics: The market exhibits a mix of large cloud incumbents, specialized platform vendors, and aggressive scale‑ups. Our research provides the decision frameworks to map vendor capabilities to your strategic outcomes, not just feature checklists.
What’s in the brief — practical, executable intelligence
-
Concise market sizing and forward drivers: A calibrated market model that tracks historical uptake (2020–2025) and forecasts through 2032, underpinned by scenario stress tests for infrastructure and regulatory shocks.
-
Outcome‑based vendor assessment: Actionable vendor profiles and decision matrices that align vendor strengths to buyer outcomes (automation rate, containment, conversion lift, sentiment recovery), including scorecards you can use in RFP and PoC selection.
-
Implementation playbooks: Step‑by‑step blueprints for pilot design, success metrics, escalation rules, and a recommended pilot‑to‑scale roadmap optimized for cost, security, and time‑to‑value.
-
TCO and ROI modeling: Financial templates and sensitivity analyses that factor in infrastructure energy exposure, labor displacement benefits, integration overheads, and expected maintenance/upgrade costs.
-
Compliance and operations toolkits: Data residency checklists, privacy impact assessment templates, and contractual language for negotiating operational responsibilities—especially critical where cross‑border interaction policies and net neutrality requirements apply.
-
M&A and partnership playbook: Profiles of strategic moves to watch, acquisition targets that can accelerate capability gaps, and partnership archetypes for combining platform strengths with enterprise domain knowledge.
Market dynamics shaping vendor and buyer strategy
-
Infrastructure cost dynamics: Our desk research and scenario modeling incorporate recent projections showing sharp increases in data center energy demand. These dynamics materially affect cloud economics for conversational platforms and will drive new commercial constructs—capacity guarantees, energy surcharges, and shared‑savings models.
-
Regulatory pressure: Policy moves to make platform operators bear a portion of data center electricity costs, and evolving data sovereignty regimes, will force buyers to insist on regional deployment options and more transparent energy and data‑flow disclosures from vendors.
-
Operational economics: Conversational platforms continue to displace routine contact center workload, improving unit economics where automation is paired with quality assurance loops. Buyers should model labour arbitrage conservatively and plan for reskilling investments.
-
Industry concentration: Market concentration metrics indicate that a minority of vendors control a meaningful share of current revenue—enough to set standards but not enough to foreclose competition. This creates windows for specialist entrants and vertically focused players to win enterprise pockets.
-
Technology shift: The rise of agentic models and large action models (LAMs) expands conversational platforms from routing and intent resolution to task execution. Early adopters will capture outsized workflow productivity gains, but must budget for governance and audit trails.
Competitive landscape — what our analysis reveals
We profile major cloud incumbents, established CX specialists, and emergent challengers, focusing on enterprise readiness, integration posture, scalability, and commercial flexibility.
-
Google (Dialogflow CX): Positioned for complex, multi‑turn web agents with strong natural language understanding and deep Google Cloud integration. Best for enterprises invested in Google Cloud infrastructure seeking scale and multimodal routing.
-
Microsoft (Copilot Studio / Azure Bot Service): Strength lies in ecosystem leverage—tight integration with Microsoft 365, Teams, and Azure infrastructure. Recommended for organizations prioritizing employee experience and internal productivity use cases alongside customer channels.
-
Amazon (Lex): A pragmatic option where AWS is the backbone; excels in operational scale and native integration with voice and eventing platforms. Strong choice for cloud‑first architectures with heavy backend automation needs.
-
IBM (watsonx Assistant): Emphasizes no‑code builder experiences combined with enterprise governance and LLM support. Attractive for regulated industries that require rigorous control and auditability.
-
Kore.ai and Cognigy (now part of NICE): Specialism in omnichannel deployment and regulated verticals. NICE’s acquisition of Cognigy signals consolidation and a push to combine workforce optimization with agentic automation.
-
Yellow.ai, LivePerson, Sprinklr: Focus on multilingual CX, personalization, and unified experience management. These vendors excel at complex customer journeys and messaging‑centric engagements.
-
OneReach.ai, Sierra, Decagon, Intercom (Fin), Rasa: A set of agile specialists and open‑framework providers—each offers unique value: workflow orchestration, outcome orientation, rapid enterprise adoption, verticalized offerings for finance, and open customization for sophisticated in‑house teams.
Recent market moves—such as large product launches leveraging agentic models, multi‑party partnerships between retailers and cloud providers, significant funding rounds for agent specialists, and targeted acquisitions—signal an acceleration from conversational prototypes to production workflows. Our brief unpacks which moves are tactical versus strategic and frames scenarios for vendor disruption.
Decision playbook — recommended boardroom and IT actions for 2026
-
Start with outcomes, not technology: Define the specific customer or operational outcomes you expect (containment, resolution time, revenue per conversation) and reverse‑engineer platform requirements.
-
Stress‑test for energy and regulatory exposure: Require vendors to disclose energy consumption profiles and data residency pathways. Use the report’s supplier interrogation checklist in RFPs.
-
Adopt hybrid deployment strategies: Where regulation or latency matters, plan for regional on‑prem or hybrid models; leverage cloud for scaleable NLU and analytics while keeping sensitive data localized.
-
Negotiate outcome‑based pricing where possible: Align commercial terms to business KPIs and reserve portions of payment for measured production outcomes after pilot acceptance.
-
Prepare the workforce for augmentation: Allocate a portion of projected FTE savings to retraining and quality assurance functions to sustain conversational effectiveness and compliance.
-
Use our vendor scorecards and PoC templates: Run parallel, short PoCs against a standardized set of customer journeys to de‑risk scale decisions and accelerate contracting.
How to access the full intelligence and data tables
This briefing intentionally previews strategic conclusions and frameworks while reserving the detailed segmentation tables, regional breakdowns, vendor rankings, and full financial models for the full PW Consulting report. The complete publication contains the granular data and executable templates necessary to operationalize a 2026‑era conversational AI program.
To obtain the full report, download supporting materials, or request a tailored briefing for your executive team, visit PW Consulting’s report page: https://www.pw-consulting.com/reports/web-conversational-ai-platform-market. For bespoke advisory engagements, contact PW Consulting’s advisory team to schedule a workshop that maps the report’s findings to your organization’s strategic priorities.
For detailed analysis of this topic, please visit the official page: Web Conversational Ai Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com