

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Bone Cutting Forcep Market to Expand at a 5.85% CAGR Through 2032 as Surgical Demand Surges

Bone Cutting Forcep Market 2026: Strategic Imperatives from PW Consulting
Executive summary
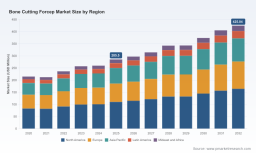
PW Consulting’s latest Bone Cutting Forcep Market report (base year: 2025; forecast period: 2026–2032) equips executives with the forward-looking, actionable intelligence required to make high-stakes decisions in 2026. The reusable bone cutting forcep market has demonstrated resilient expansion through the early 2020s and, based on our central scenario, is projected to grow at a compounded annual growth rate (CAGR) of 5.85% across the 2026–2032 forecast window. Measured on PW Consulting’s standardized revenue basis, the market reached roughly USD 285.5 Million in 2025 and is forecast to approach the mid-hundreds of millions by 2032 under current assumptions.
Bone Cutting Forcep Market
This communiqué is designed as a strategic preview: it synthesizes our most consequential insights and recommendations while intentionally withholding the segmented numerical tables and granular regional/application breakdowns that are contained in the full report. Those elements are preserved to drive readers to the detailed dataset and downloadable models on the PW Consulting portal.
Bone Cutting Forcep Market
Why this market matters for 2026 decision-makers
- Clinical demand tailwinds. Demographic trends, rising volumes of orthopedic and related surgeries, and continued focus on improved procedural ergonomics are sustaining demand for bone cutting forceps. These instruments remain core to many procedures where precise, repeatable bone manipulation is critical.
- Service and lifecycle economics. Because bone cutting forceps are reusable, sterilization regimes, repair/refurbishment services, and instrument lifecycle costs are strategic levers for both hospitals and manufacturers. Procurement decisions increasingly prioritize total cost of ownership (TCO), not just unit price.
- Regulatory and quality pressures. Reusables are subject to EU MDR and FDA regulatory frameworks (often Class I or II), and manufacturers typically operate under ISO 13485 systems. Compliance and process documentation are becoming de facto market entry barriers and differentiation points.
- Consolidation and capability aggregation. The competitive environment shows growing consolidation activity, creating opportunities and risks for incumbents and private equity alike. Market concentration metrics indicate a moderately consolidated supplier base, with room for further scale-driven advantages.
Key market dynamics shaping 2026 strategy
Operational and commercial leaders should prioritize four interlocking dynamics when shaping 2026 plans:
Bone Cutting Forcep Market
- Durability vs. disposability economics: High-quality instruments manufactured from surgical-grade materials (e.g., 420-equivalent stainless steels, as used across established lines) endure repeated autoclave cycles. Suppliers that can objectively demonstrate longer service life and lower refurbishment frequency capture procurement preference.
- Aftermarket services as margin engines: Repair, sharpening, and refurbishment services—offered either in-house or through certified partners—are becoming a primary differentiator in procurement negotiations and customer retention.
- Regulatory compliance as commercial advantage: CE marking, ISO 13485 certification, and FDA clearances not only mitigate legal risk but also shorten purchasing cycles with large hospital systems that maintain strict device lists.
- Strategic M&A activity: Recent transactions underscore acquisitive strategies by established players to broaden portfolios and capture service capabilities. Such deals can re-shape regional sales channels and aftersales footprints quickly.
Competitive landscape — practical implications
The market features a mix of premium instrument houses, regional specialists, and value suppliers. Notable players we track include:
- Stille AB — premium instrument manufacturer with a heritage in precision double-action forceps and disassembly-friendly designs (noteworthy for recent strategic expansion through acquisition activity).
- Integra LifeSciences (Miltex) — a broad surgical portfolio with multiple branded forcep patterns and sizes addressing the orthopedic spectrum.
- Surgical Holdings — a UK-based specialist known for stainless-steel manufacturing to local standards and for providing repair/refurbishment pathways.
- gSource — a supplier that sources high-grade stainless surgical instruments for the US market, emphasizing established pattern variants.
- GerMedUSA / GerVetUSA — multi-channel supplier covering both human and veterinary channels, offering familiar orthopedic patterns.
Strategic note: the market experienced a material consolidation move in late 2025 when a premium European instrument maker completed an acquisition to strengthen its surgical instruments portfolio and service coverage. That transaction illustrates two critical themes: (1) vertical augmentation of service & refurbishment capabilities, and (2) portfolio convergence as a route to lock-in with large hospital group customers.
Regulatory and material realities — what procurement must verify
- Classification and sterilization: Bone cutting forceps are typically regulated as reusable Class I or II devices under EU MDR and FDA rules; designs and labeling must reflect autoclave compatibility and validated reprocessing instructions.
- Quality systems: Manufacturers operating in this space are expected to hold ISO 13485 and maintain device master records that enable traceability through the device lifecycle.
- Material selection: Surgical-grade 420-equivalent stainless steel remains the dominant choice for corrosion resistance and repeat autoclave durability; alternative materials such as titanium and tungsten-carbide tipped components are used selectively for performance or weight objectives.
- Certifications and listings: CE and FDA clearances materially shorten procurement timelines with large institutional buyers; proof points on sterilization validation and service contracts reduce perceived purchasing risk.
What PW Consulting’s report contains (practical, implementable deliverables)
The full report goes beyond narrative and includes a suite of operational tools and primary-source datasets intended for immediate use by senior leadership and procurement teams. Key inclusions are:
- Market-sizing model (historical 2020–2025 and forward-looking 2026–2032) with scenario toggles for volume and price variables.
- Profitability benchmark and supplier scorecard templates covering manufacturing footprint, material mix, repair-service economics, and margin sensitivities.
- Regulatory compliance checklist and validated sterilization guidance tailored for device engineers and quality teams.
- Procurement playbook: TCO calculator, RFQ language for bundled instrument + service contracts, and best-practice SLA templates for refurbishment partners.
- M&A playbook: target screening criteria, integration risks (service networks, inventory, quality systems), and a short list of bolt-on attributes that create near-term synergies.
- Primary interviews and clinical adoption case studies that document hospital decision criteria and real-world reprocessing workflows.
- Interactive Excel model and raw datasets (segment breakdowns by region, type, and application available in the paid deliverable).
2026 strategic recommendations — executive checklist
- For manufacturers: Prioritize modular designs that ease sharpening and part replacement; build or partner for certified refurbishment to capture aftermarket margin; accelerate ISO 13485 and country-specific listings to shorten tender cycles.
- For hospital procurement: Shift from unit-price sourcing to bundled instrument-plus-service contracts that explicitly capture lifecycle costs and validated reprocessing protocols; insist on performance warranties tied to usable cycles.
- For distributors: Develop regional service hubs or certified partner programs to reduce turnaround times for refurbishment and to support just-in-time replacement kits.
- For private equity and strategics: Target acquisitions that combine manufacturing excellence with service networks; look for targets with documented quality systems and repeatable refurbishment margins.
- For product teams: Invest in traceability (batch and instrument-level) and digital reprocessing logs that can be integrated with hospital sterilization records—this is a near-term differentiator in tender evaluations.
Using the report in 90 days — a suggested roadmap
- Day 0–14: Download the model; run your existing supplier list through the supplier scorecard to establish a baseline TCO.
- Day 15–45: Execute targeted supplier diligence against certification and service-readiness; pilot a bundled instrument-service contract with a single surgical unit.
- Day 46–90: Roll out revised procurement terms across high-volume operating units; begin integration talks (M&A or JV) for service partners if consolidation is a strategic priority.
Conclusion — why PW Consulting’s insight matters for 2026
By 2026, market participants who treat bone cutting forceps as lifecycle-managed assets—rather than as one-off consumables—will capture disproportionate value. The market’s steady mid-single-digit CAGR and moderate supplier concentration create attractive conditions for disciplined consolidation and service-enabled differentiation. PW Consulting’s Bone Cutting Forcep Market report provides the quantitative backbone (including our market-size model, scenario tools, and supplier benchmarks) and the qualitative context (clinical use-cases, regulatory checklists, and procurement templates) that boards, C-suite teams, and PE sponsors require to move from contemplation to execution in 2026.
To access the full segmented datasets, downloadable models, and the supplier-by-supplier benchmarking matrix that power these recommendations, please visit the PW Consulting research portal or contact our team for an executive briefing and trial access. The full report contains the regional and application breakdowns and the proprietary scoring used to generate the market-concentration and scenario outputs summarized here.
For detailed analysis of this topic, please visit the official page: Bone Cutting Forcep Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com