

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fully Automatic Snow Blower Market Poised to Grow at a 16.22% CAGR

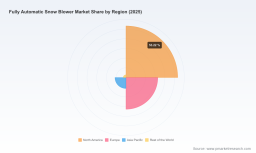
Strategic Outlook 2026: Fully Automatic Snow Blower Market — PW Consulting Industry Brief
Executive snapshot
The fully automatic snow blower market is transitioning from niche automation experiments to a commercially scalable industry opportunity. PW Consulting’s latest market model — built on a 2020–2025 historical foundation and forward-looking projections through 2032 — shows the sector expanding from a mid‑hundreds USD Million base in 2025 to well beyond the billion‑dollar threshold by the early 2030s. Our forecast period (2026–2032) uses a compound annual growth rate (CAGR) of 16.22%, reflecting accelerating adoption driven by labor scarcity, rising total cost of ownership pressures on manual clearing, and rapid advances in perception and localization technologies for outdoor autonomous systems.
Fully Automatic Snow Blower Market
Why this report matters for 2026 corporate decision‑making
2026 is a pivotal planning year for incumbent OEMs, new entrants, Tier‑1 suppliers and institutional buyers. Companies that treat this market as a traditional small‑equipment category risk being outflanked by firms that apply robotics engineering, software monetization, and service models to snow removal. The strategic value of our report for 2026 planning lies in three practical dimensions:
Fully Automatic Snow Blower Market
- Market sizing and trajectory: We quantify a clear, multi‑year growth path that converts seasonal demand into recurring revenue opportunities through subscription and managed‑services models.
- Decision‑grade scenario analysis: The report provides actionable scenarios that translate weather volatility, labor availability, and input cost shocks into near‑term revenue outcomes — enabling robust budgeting and capital allocation choices for 2026.
- Execution playbooks: We supply pragmatic go‑to‑market and operational checklists that accelerate pilots, minimize safety risk, and create defensible routes to scale.
Market trajectory: a data‑driven view
PW Consulting’s topline market series tracks steady acceleration: through 2025 the market reached a substantive mid‑hundreds USD Million level, and we model a significant step up in 2026 as field‑proven robotic products move from pilots into broader residential and commercial deployments. By the end of the forecast window, the market size exceeds USD Million levels indicative of a conversion from niche sales to mainstream procurement among property managers, municipalities, and large‑lot residential markets. The modeled CAGR of 16.22% across the 2026–2032 horizon captures both technology maturation and adoption curves for safety certification, dealer networks, and integrated service offerings.
Fully Automatic Snow Blower Market
Competitive landscape — who competes and how
The competitive set combines traditional snow‑equipment manufacturers, robotic yard specialists, and heavy‑duty industrial suppliers. Each group brings distinct advantages and strategic tradeoffs:
- Robotic yard and modular automation firms are first movers on purpose‑built, fully automatic consumer and small‑lot offerings. They emphasize software, RTK‑level localization, AI vision stacks, modular year‑round utility, and direct‑to‑consumer service models.
- Established OEMs in the snow equipment ecosystem retain distribution scale, dealer relationships, and brand trust for high‑performance two‑stage machines and battery platforms. Their path to autonomy is often incremental — integrating electronic controls, battery architecture, and perception modules into proven platforms.
- Industrial and airport‑grade suppliers deliver capacity and durability for municipal and airport operations. Their competitive focus is on throughput, reliability, and compliance with large fleet procurement cycles; autonomous upgrades here center on autonomy for repetitive, high‑demand routes.
Representative players in our competitive analysis include leading modular robotic specialists with RTK‑GPS, AI‑vision, and modular swap‑out payloads; legacy manufacturers with deep product engineering and dealer networks; and heavy‑duty OEMs focused on commercial throughput. Recent commercial milestones — notably live, high‑visibility demonstrations and viral proof points from robotic yard companies during major storms and trade events — have materially shifted perception, accelerating willingness among early‑adopter buyers to fund pilots and first‑generation deployments.
Notable recent developments and what they imply
- High‑profile live demos and pop‑ups that show autonomous clearing during actual storms have reduced buyer uncertainty around reliability and safety, shortening pilot timelines.
- CES previews and enhanced sensor packages (LiDAR/camera fusion, RTK GPS) indicate vendor prioritization of robust localization in cluttered residential settings — a direct response to safety and liability concerns.
- Viral performance videos have boosted brand awareness but also invite rapid competitive responses; incumbents with scale can counter by bundling autonomy into existing dealer service contracts.
Industry dynamics, input risks and operational levers
Several cross‑cutting dynamics will determine winners in 2026:
- Raw materials and component cost volatility: Steel and commodity pricing affect unit BOM cost and aftermarket structural durability decisions. Hedging strategies and design choices that minimize steel intensity without sacrificing robustness will be a 2026 operational priority.
- Labor shortages and seasonality: Contractors report significant seasonal labor gaps, creating a strong business case for automation. Vendors that can demonstrate fast ROI in reduced labor dependence will find receptive customers among large‑lot residential and municipal fleets.
- Regulatory and safety frameworks: Liability, public‑space operation rules, and certification requirements are evolving. Companies that invest in demonstrable safety engineering, redundant sensing, and transparent field‑test documentation shorten the approval runway for scaled deployments.
Market structure and concentration implications
Market concentration metrics indicate moderate—yet meaningful—leadership by a small group of firms, with the top players holding a sizeable share of industry revenue. This structure creates asymmetric advantages: incumbents with channel scale can enforce distribution discipline and lock in service revenues, while focused robotics specialists can rapidly iterate product‑market fit and captive software ecosystems. For 2026, strategic options split between defensive consolidation by legacy players and aggressive vertical integration by robotics entrants seeking to own the end‑to‑end customer experience.
How PW Consulting’s report converts insight into action
We intentionally designed the report as a toolkit for decision makers who need to move beyond generic forecasts to executable plans. Key deliverables include:
- Actionable investment theses for R&D, M&A, and pilot funding, with risk‑weighted payback ranges calibrated to 2026 capital budgets.
- Go‑to‑market playbooks for residential, commercial, and municipal segments — including channel incentive structures, pricing architecture, and service level agreements tailored to seasonal demand.
- Supply‑chain stress tests and procurement checklists that incorporate raw material scenarios and critical component lead‑time contingencies.
- Operational templates: pilot design, fleet onboarding protocols, safety validation checklists, and field‑trial metrics for uptime, throughput, and unit TCO modeling.
- Competitive benchmarking and strategic options maps that highlight where to partner, acquire, or compete — preserving confidentiality of detailed segment tables to encourage deeper engagement with the full dataset.
Recommendations for 2026 strategy
Based on our synthesis, companies should prioritize the following in their 2026 plans:
- Fund focused pilots tied to measurable ROI outcomes (e.g., labor substitution, service revenue per unit) rather than broad technology demonstrations.
- Design modular hardware roadmaps that allow a single platform to serve year‑round utility, improving capacity utilization and dealer profitability.
- Secure critical supply‑chain inputs through strategic vendor agreements or alternative materials sourcing to mitigate steel and component shocks.
- Develop safety and regulatory playbooks early — regulatory acceptance and insurance underwriting will be decisive for municipal and shared‑use deployments.
- Evaluate partnership structures with local contractors and property managers to blend autonomous equipment with managed‑service contracts, expediting adoption by reducing buyer friction.
What we withhold here — and why you should read the full report
This brief surfaces the strategic direction and operational priorities decision makers need for 2026. To preserve the "trailer" integrity and ensure an authoritative basis for contractual and investment work, we have intentionally omitted the detailed segment‑level breakdowns, regional allocations and discreet dollarized splits. The full PW Consulting report contains the complete datasets, scenario spreadsheets, and downloadable benchmarking matrices required to populate financial models, underwrite pilots, and structure M&A diligence.
Next steps
For executives preparing 2026 budgets, procurement officers evaluating pilots, or investors sizing market opportunities, PW Consulting’s full Fully Automatic Snow Blower Market report provides the data, frameworks, and execution templates necessary to move from strategy to operational delivery. Contact PW Consulting to access the complete report, underlying datasets, and bespoke advisory engagements that tailor our findings to your organization’s risk profile and strategic objectives.
For detailed analysis of this topic, please visit the official page: Fully Automatic Snow Blower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com