

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 6.22% CAGR for Global Silicone Resin Market Through 2032

Silicone Resin Market 2026: Strategic Imperatives for Corporate Decision-Makers
Executive Preview
As companies plan capital allocation, product roadmaps, and cross-border strategies for 2026, silicone resin markets are presenting a mix of steady demand growth, concentrated supplier dynamics, and rising regulatory and input-cost complexity. PW Consulting’s newest Silicone Resin Market report—anchored on a 2025 base year and projecting through 2032—translates macro trajectories into actionable options for executives, investors, and commercial teams. This press release offers a high-level synthesis of the report’s strategic value while intentionally withholding granular segment-level figures to encourage direct access to the full study for transaction- and operations-critical detail.
Silicone Resin Market
Market at a Glance (Macro View)
-
Growth trajectory: The silicone resin market has expanded from approximately USD 4.09 billion in 2020 to an estimated USD 5.52 billion in 2025 (USD Million base). Our forecast ensemble projects continued expansion into the forecast window, with the market surpassing USD 8.4 billion by 2032. The compound annual growth rate (CAGR) for the forecast period is calculated at roughly 6.22%—a rate that supports mid-single-digit strategic planning assumptions across capex, pricing, and R&D horizons.
Silicone Resin Market -
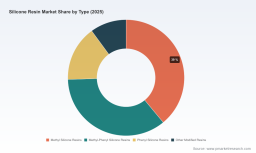
Industry structure: Market concentration is meaningful but not prohibitive to entrants. Top-three players account for a substantial share of global value, while the top five aggregate a majority of supply—creating both barriers and opportunities for niche specialists, regional producers, and integrated chemical players pursuing scale or differentiation.
Silicone Resin Market
Why This Report Matters to 2026 Decision Cycles
For boards, strategy teams, and business unit leaders, the 2026 planning cycle is a pivot point. Key decisions—capacity expansion, supply chain reconfiguration, portfolio pruning, and M&A—must be informed by reliable, scenario-tested market intelligence. The PW Consulting report converts raw market forecasts into practical decision-support instruments that answer “so what” and “what next”. The following priorities explain the report’s direct relevance.
-
CapEx and Capacity Optimization: The sustained mid-single-digit CAGR justifies selective capacity investments—particularly where technology or formulation complexity raises switching costs. Our modeling provides facility-level throughput break-even analysis, brownfield vs. greenfield scenarios, and region-specific utilization thresholds to guide 3–5 year investment approvals.
-
Supply-Chain Resilience and Input Cost Strategies: Volatile feedstock and energy costs materially affect margins. Our study integrates commodity sensitivity analyses (including metallic silicon price dynamics) and recommends hedging, vendor diversification and backward-integration options tailored to company scale.
-
Regulatory and Compliance Roadmap: Evolving rules—especially in Europe and North America—impact formulation choices and market access. The report’s regulatory playbook links specific restrictions and transport standards to reformulation timelines, compliance-cost estimates, and labeling obligations to support procurement and product teams.
-
Product and Application Prioritization: Demand drivers across coatings, electrical, adhesives and emerging specialty applications vary in growth, margin, and technical requirements. We provide decision frameworks to prioritize product development, licensing, or partnership investments without revealing proprietary segment-level revenues in this preview.
-
M&A and Partnership Targeting: The market concentration pattern favors bolt-on acquisitions for scale and capability buys for specialization. The report contains a prescriptive acquisition-screening matrix and stress-tested valuations that align with strategic scenarios from conservative to aggressive growth plays.
Competitive Landscape: Who Matters and Why
The silicone resin industry blends multinational chemical majors and regional specialists. Market power rests with producers that combine large-scale manufacturing, diversified end-use portfolios, and regulatory competence. Key players profiled in our analysis include:
-
Dow (Midland, Michigan, USA) — A global leader with a broad SILRES portfolio used across protective coatings, electrical insulation, and molded parts. Dow’s recent portfolio-level REACH compliance update signals investment in regulatory assurance and market continuity for European customers.
-
Wacker Chemie AG (Munich, Germany) — A major supplier focused on high-temperature coatings, release agents, and electronics encapsulation. Wacker’s capacity expansion at its Nunspeet facility underscores ongoing demand in coatings and the strategic importance of regional manufacturing footprint.
-
Shin-Etsu Chemical (Tokyo, Japan) — The world’s largest silicone producer, offering silicone resin grades for toners, paints, and sealants. Recent launches targeted at high-heat automotive electronics demonstrate how product innovation can capture premium niches.
-
Momentive Performance Materials (Waterford, NY, USA) — Specializes in specialty resins for industrial coatings and automotive clearcoats, with a product focus that supports differentiated value propositions.
-
Elkem ASA (Oslo, Norway) — Serves electrical insulation varnishes and high-performance coatings markets, leveraging materials expertise for industrial customers.
-
KCC Corporation (Siheung, South Korea) — A regional player producing resins for paints, inks, and electronic protection; represents the importance of local customer intimacy and application know-how.
Recent corporate moves—capacity additions, new high-heat grades, and regulatory compliance updates—are indicative of an industry investing in both scale and specialized performance. Our competitive chapter maps these initiatives to commercial outcomes and recommends strategic counters for incumbents and challengers alike.
Key Dynamics & Operational Noise to Monitor
Several non-market forces will shape outcomes in 2026 and should be factored into any strategic plan:
-
Feedstock volatility: Metallic silicon prices rose materially late in 2024, increasing feedstock cost pressure across resin producers and compressing gross margins for companies unable to pass costs through pricing mechanisms.
-
Regulatory constraints: Restrictions such as limits on certain cyclic siloxanes in wash-off products and evolving transport classifications necessitate reformulation and logistics adjustments. Compliance timelines and certification costs are quantified in the report’s regulatory impact tables.
-
Trade and tariff risks: Existing tariffs on imports from certain jurisdictions create regional arbitrage and supply re-routing opportunities—but also increase price dispersion and complicate global pricing strategies.
-
Logistics & classification changes: Recent amendments to international maritime dangerous goods codes affect labeling and handling for several resin grades, with direct implications for freight costs and lead time reliability.
-
Sustainability and certification exposure: Emerging scrutiny around fluorinated chemistries and certifications such as LEED means that certain specialty resin variants may encounter barriers in green construction and public-sector procurement.
What the PW Consulting Report Contains (Practical Deliverables)
Our full report is structured to support immediate and medium-term decisions. Highlights include:
-
A transparent, auditable market model (2020–2032) with scenario toggles for macroeconomic growth, raw material shocks, and regulatory outcomes.
-
Price and margin sensitivity matrices that convert feedstock and tariff moves into EBITDA impact by company type and product class.
-
Supplier scorecards and procurement playbooks designed to reduce supply risk and shorten qualification cycles for industrial customers.
-
Regulatory compliance timelines and cost-estimation worksheets tailored to EU REACH, IMDG transport amendments, and North American labeling regimes.
-
M&A screening tools, including an acquisition valuation template, synergy checklist, and integration risk heatmap.
-
Commercial go-to-market templates for penetrating high-growth application niches, plus recommended KPIs for tracking success in the first 24 months post-launch.
To preserve the report’s utility for transaction-grade planning, granular regional and application-level revenue breakdowns are not published in this press release. Subscribers and licensed purchasers receive the full segment-level datasets, benchmarking matrices, and proprietary supplier intelligence needed to execute deals and operational programs.
Recommended Actions for 2026 Planning
-
Initiate scenario-based capital planning: Use the report’s stress-tested capex templates to evaluate brownfield expansions and convert optionality into executable investment plans.
-
Lock in feedstock contracts selectively: Combine short-term hedges with strategic supplier partnerships to mitigate metallic silicon price risk.
-
Prioritize regulatory readiness: Allocate resources now for reformulation and transport compliance to avoid market disruption when new standards are enforced.
-
Explore targeted M&A: Pursue bolt-on assets that bring application expertise or regional proximity rather than broad-scale production facilities in tariff-disadvantaged regions.
-
Align sustainability claims to certification pathways: Carefully vet fluorinated and specialty chemistries against green-building standards and procurement policies before market positioning.
Conclusion & Next Steps
PWC Consulting’s Silicone Resin Market report converts a clear macro growth story—underpinned by a ~6.22% CAGR and a market expanding from roughly USD 4.1 billion (2020) to over USD 5.5 billion (2025), and projected to breach USD 8.4 billion by 2032—into practical, board-ready actions for 2026. The combination of concentration among leading suppliers, persistent feedstock volatility, tightening regulation, and application-specific growth creates a landscape where informed, timely moves will deliver disproportionate returns.
For access to the complete dataset, proprietary segmentation, supplier-level intelligence and executable playbooks, visit PW Consulting’s report page or contact our industry team to arrange a briefing and data license. The full report is the only source that couples market-scale forecasts with the operational tools necessary to convert insight into value in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Silicone Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com