

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
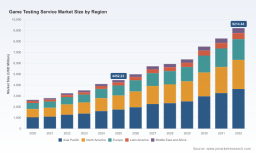
PW Consulting: Game Testing Services Market to Hit USD 9.21 Billion by 2032 at 10.95% CAGR — Mobile Gaming and Asia‑Pacific Lead Growth

Game Testing Service Market — Strategic Outlook for 2026: A PW Consulting Executive Brief
As global game development ramps into a new cycle of technological complexity and regulatory scrutiny, leaders face a pivotal decision window in 2026: restructure in-house QA to capture scale and speed, or selectively outsource to specialist partners that combine engineering depth, device coverage and compliance capabilities. PW Consulting’s latest Game Testing Service Market report distills a six-year historical view and a seven-year forecast, anchored on a robust macro trajectory (2020–2025 historical base, 2026–2032 forecast), to provide the decision-support executives need to act with conviction.
Game Testing Service Market
Why the market picture matters for 2026 planning
Our analysis traces rapid expansion in game testing services: total market value more than doubled from the early part of the decade to the 2025 base year and continues on a strong growth path through 2032. The market’s compound annual growth rate (CAGR) across the forecast window is 10.95%, reflecting accelerating demand driven by platform proliferation, live-service complexity, and higher certification/compliance burdens. For leaders planning 2026 investments—whether in device labs, automated testing, or strategic supplier partnerships—this is not a marginal trend: it defines the operating envelope for product quality, release cadence and player trust over the next three-to-five years.
Game Testing Service Market
What this means in practice
- CapEx and OpEx planning must reflect growing QA intensity. Studios that treat testing as a cost center risk release delays and reputational harm; those that invest strategically in automation and validated vendor capacity gain a durable time-to-market advantage.
- Regulatory and platform gatekeepers are increasingly determining launch feasibility. Certification, security and localization are no longer add-ons: they are integral to release planning and monetization timelines.
- Vendor selection should be evaluated through a composite lens of technical capability (automation & device coverage), compliance proficiency (privacy, consumer protection, loot-box and age-rating considerations), and commercial scale. Market concentration metrics show a mix of specialist boutiques and larger integrated providers; top-tier players hold significant share but the market remains sufficiently fragmented to allow targeted partnerships.
Report highlights — practical content you can act on
PW Consulting designed the report to be a playbook for executives, product leaders and procurement teams. Highlights include:
Game Testing Service Market
- Macro to micro forecasting: a validated market model from 2020 through 2032 with scenario stress tests for downside (regulatory tightening) and upside (rapid AI adoption) outcomes.
- Vendor scorecards and capability matrices: side-by-side assessments of leading providers across QA domains—functionality, compatibility, performance/security, localization and certification—calibrated to platform complexity and title scale.
- Cost and pricing benchmarks: practical ranges and cost drivers for common scopes (e.g., device matrix testing and regression cycles), enabling realistic budgeting and procurement negotiating levers.
- Operational playbooks: step-by-step guidance on implementing AI-assisted testing, building hybrid in-house/vendor device labs, and integrating compliance testing into continuous delivery pipelines.
- Go-to-market decision frameworks: when to insource vs. outsource, how to structure SLAs for live operations, and how to design vendor partnerships that protect IP while scaling QA throughput.
To preserve strategic value for decision-makers, the report deliberately refrains from publishing detailed sub-segment numerical splits in public summaries—those granular allocations and vendor-specific revenue breakdowns are available in the full report and online portal for subscribers.
Competitive landscape: who matters and why
The game testing market is defined by a mix of large integrated service providers and specialized boutiques. Larger players offer global capacity and end-to-end services, while smaller specialists provide deep technical or regional strengths. Our competitive analysis focuses on capability differentiation rather than headline revenues:
- Keywords Studios — Established as the largest dedicated provider with global studios and broad platform coverage; recent strategic moves include AI-assisted testing platform launches and targeted acquisitions to strengthen high-growth regional presence. Their strength: scale and an expanding automation portfolio that targets regression cycle reduction.
- Lionbridge Games — Deep in localization QA and compliance testing, with historic strength in linguistic QA across global releases. Their value proposition is integrated localization plus compliance for studios releasing to multiple regulated markets.
- Testronic Labs — Known for end-to-end functionality, compatibility and certification expertise, with a reputation for helping titles pass platform gatekeeping requirements efficiently.
- Pole To Win / Side — A broader co-development partner that bundles QA with art, audio and player support; suited to studios seeking integrated development and post-launch operations.
- GlobalStep, Quantic Lab, iXie Gaming (Indium), QATestLab and regional specialists (TestFort, QAble, KiwiQA, TestMatick, SnoopGame, LogiGear) — Collectively, these firms provide flexible capacity, strong technical teams and the ability to custom-tailor QA engagements, notably for mobile-first titles and emerging platform work (cloud, VR/AR).
Market concentration indicators show a clustered but not monopolistic landscape: the top three and top five firms together represent meaningful shares of the market, while numerous regional players and boutiques maintain relevance for specialized needs. For procurement teams this means competitive dynamics support both scale deals and strategic, skill-based engagements.
Technology and regulatory dynamics shaping 2026 choices
- AI and automation: Adoption of AI-assisted testing is accelerating. Major providers have moved from pilot projects to productized platforms—examples include new AI-driven regression tools released in early 2026—delivering measurable cycle-time reductions. However, governance questions around AI test coverage, reproducibility and data usage require governance frameworks before full-scale adoption.
- Device explosion and compatibility complexity: Mobile ecosystems and cross-platform play have increased the device matrix exponentially. Comprehensive compatibility testing for high-variation mobile portfolios remains a material line item for studios; typical full-device coverage projects carry significant but predictable costs that must be budgeted into pre-launch phases.
- Regulatory and compliance pressure: Regulators in key markets are actively scrutinizing privacy, monetization mechanics and child protection. Compliance and security testing are now mandatory checkpoints in many release pipelines; failure to build these capabilities into QA planning can derail launches or incur remediation costs.
- Cost arbitrage and operating models: Outsourcing to lower-cost regions remains a powerful lever—operational costs can decline substantially—yet risk-management (IP, data handling, regulatory alignment) must be structured into engagement contracts and technical architectures.
Strategic recommendations for 2026 decision-makers
- Adopt a hybrid sourcing model. Combine in-house strategic testing (security, live-ops regression, proprietary mechanics) with vendor-sourced scale testing (device compatibility matrices, large-scale functionality runs). This balances speed, cost and IP protection.
- Invest in validated AI tooling—but do so with guardrails. Prioritize tools that provide explainable test outcomes, clear training data lineage and a roadmap for continuous improvement. Pilot on low-risk titles before enterprise-wide deployment.
- Include regulatory testing early. Integrate privacy, monetization and age-classification scenarios into functional and certification test plans to avoid late-stage rework.
- Use procurement to buy outcomes, not hours. Structure SLAs around quality gates, time-to-resolution and launch readiness metrics rather than pure test-hour counts—this aligns incentives and improves predictability.
- Benchmark costs and capacity with an eye to device coverage. Use market pricing references to validate vendor quotes for complex compatibility matrices and regression packages.
How to use the full PW Consulting report
Leaders should use the full report in three phases:
- Strategy setting (Q1–Q2 2026): Use the macro forecasts and scenario planning to size QA investments and prioritize capability build vs. buy.
- Supplier selection and contracting (Q2–Q3 2026): Deploy the vendor scorecards and pricing benchmarks as the foundation for RFPs and commercial negotiations.
- Operationalization (Q3 2026 onward): Implement the operational playbooks and KPI templates to measure ROI from automation, vendor partnerships and compliance initiatives.
Closing perspective
The game testing services market is maturing into a strategic sector that intersects engineering, legal/regulatory, and player-experience outcomes. With market value growing at an industry-level CAGR of roughly 11% across our forecast window and continued technology-driven efficiency gains, 2026 is the year to move from reactive QA to proactive quality engineering. PW Consulting’s Game Testing Service Market report provides the scenario-tested framework, vendor intelligence and executable roadmaps to convert market growth into competitive advantage—without exposing the granular segmentation that is the core value of our primary research. For the granular splits, supplier-level financials and downloadable procurement artifacts, please consult the full report and subscriber portal.
For detailed analysis of this topic, please visit the official page: Game Testing Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com