

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Portable Package Leak Detector Market to Rise from USD 692.48 Million in 2025 to USD 1.09 Billion by 2032 at a 6.68% CAGR — Asia Pacific, Bubble Emission Tech and Food & Beverage Demand Drive Growth as Top 5 Firms Capture 52.3%

Portable Package Leak Detector Market — Strategic Imperatives for 2026 Decision-Makers
As organizations in food, pharmaceutical, medical device and consumer-packaged goods industries finalize budgets and technology roadmaps for 2026, the portable package leak detector market presents both a growth runway and a complex risk landscape. PW Consulting’s latest market study (base year 2025) synthesizes seven years of market evolution and projects the market trajectory through 2032. Our analysis shows the market expanded from USD 512.14 Million in 2020 to USD 692.48 Million in 2025 and is forecast to reach USD 1,089.31 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.68% across the 2026–2032 forecast window. This briefing highlights how that growth translates into practical choices in procurement, product development, and regulatory compliance — while preserving the report’s proprietary segment-level intelligence to encourage deeper engagement with the full study.
Portable Package Leak Detector Market
Why 2026 Is a Pivotal Year
-
Regulatory inflection points are compressing investment cycles. Key packaging regulations — most notably recent European directives that move recyclability and recycled-content mandates into enforceable timelines — accelerate change across packaging formats, materials and inspection requirements. Firms must reassess test method selection and validation strategies now to avoid late-stage redesign costs in 2027–2028.
Portable Package Leak Detector Market -
Material cost volatility is reshaping supplier economics. Recent upward movement in resin pricing (including polyethylene and polypropylene series) is increasing the cost sensitivity of flexible and thermoformed packaging suppliers; this drives increased interest in non-destructive and in-line leak-detection approaches that minimize scrap and rework.
Portable Package Leak Detector Market -
Market structure and consolidation dynamics favor focused investments. The market is moderately concentrated at the top: the three largest vendors capture a meaningful share of revenue, and the top five amplify that presence — a structure that influences OEM negotiation power, distribution strategies and aftermarket service models.
Technology and Testing Trends You Can’t Ignore
-
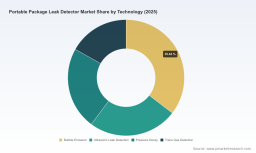
Diversification of inspection modalities. Buyers increasingly select from a toolkit that includes bubble-emission, ultrasonic, pressure-decay and trace-gas techniques. Choice depends on product fragility, packaging geometry, production speed and tolerance for destructive testing. Emerging low-intrusion, gasless approaches are gaining traction where contamination risk and test throughput are critical.
-
Portability plus data. The market is evolving from standalone hand-held testers toward portable instruments that offer real-time analytics, standardized data lakes, and simple OEM integration. This evolution reduces time-to-root-cause and enables statistical process control across multiple production sites.
-
Service and life-cycle economics. With capital discipline in procurement, total cost of ownership (TCO) is displacing headline price. Vendors that can offer certified calibration, rapid-service SLAs, and modular upgrades command a pricing premium and reduce client operating risk.
Strategic Implications for Manufacturers, OEMs and Buyers
-
Procurement strategies should be differentiated by product risk profile. For high-margin, safety-critical SKUs (e.g., sterile pharmaceuticals, single-use medical devices), allocate budget to higher-resolution, non-destructive portable systems and recurring verification programs. For commodity-oriented SKUs, consider rugged, lower-cost instruments supplemented by statistically representative lab verification.
-
Design-for-testability matters. Packaging engineers must embed test access and traceability features early in the design cycle to avoid retrofitted inspection solutions that add cost and complexity during pilot and scale-up phases.
-
Compliance and sustainability need to be reconciled. Extended producer responsibility (EPR) frameworks and recyclability mandates are not only material issues; they affect acceptable testing environments, permissible trace gases and acceptable failure rates. Testing strategies that minimize contamination and enable rapid sorting for recyclate streams will be increasingly valuable.
-
MRO and aftermarket services are competitive differentiators. Expect vendor selection to weigh spare-parts availability, field-calibration networks and digital service platforms almost as heavily as instrument precision.
Competitive Landscape — Who to Watch
The market is served by a mix of specialized niche manufacturers and large instrument houses. Key players include legacy European engineering firms and transatlantic manufacturers with deep installed bases, as well as emerging providers that emphasize software-enabled, non-destructive testing.
-
WITT-Gasetechnik (Germany): Known for the LEAK-MASTER® line and strong roots in gas-engineering solutions for seal integrity across packaging types. Their strength lies in tried-and-tested product lines and channel relationships in industrial manufacturing.
-
AMETEK MOCON / Dansensor (USA): Offers portable and benchtop tools tailored for modified-atmosphere packaging inspection — a common requirement in food and pharma. Their instruments are typically integrated into broader gas analysis and barrier-testing portfolios.
-
Oxipack (Netherlands): Focused on non-destructive, portable solutions with real-time insight for food and pharmaceutical packaging. Their value proposition emphasizes low-impact testing workflows and digital traceability.
-
FlexPak (Canada) and Haug Quality Equipment (USA): Both emphasize ASTM compliance and US manufacturing strengths for food-packaging QA with portable leak detection and field-ready systems.
-
INFICON (Switzerland): Differentiates with gasless, non-destructive detection methods suited to vacuum and sensitive packaging applications, reducing contamination risk and test-gas logistical complexity.
-
DVACI (USA) and Sepha (UK): Provide chamber-based and CCIT-style solutions respectively, fitting niches where destructive tests are impractical or where regulatory validation must meet specific pharmacopeial standards.
-
InterTech Development Company, Labthink Instruments, ATEQ, and Vacuum Instruments Corporation: These vendors offer complementary strengths in high-resolution testing, product breadth, and tracer-gas capabilities across regional markets.
Recent vendor developments are instructive. Late-2024 product-line updates from a chamber-based supplier introduced more configurable CDV methods for high-standard compliance testing; similarly, 2025 milestones from a US-made systems specialist highlighted a push to expand its installed base in packaging applications. These events reiterate two themes: vendors are investing in platform flexibility, and “made-in-region” value propositions remain important for customers with strict supply-chain or regulatory preferences.
What PW Consulting’s Full Report Contains (Practical, Actionable Deliverables)
-
Decision-ready vendor scorecards: multi-criteria supplier evaluations tuned to throughput, sensitivity, lifecycle costs and service coverage.
-
Procurement playbook and TCO templates: prescriptive checklists and financial models for capital approval cycles.
-
Technology selection matrix: guided pathways that match test modality to product risk, production-line speed and validation needs.
-
Regulatory impact maps: overlays of major EPR and recyclability rules against inspection approaches and acceptable test agents.
-
Implementation roadmaps and pilot plans: step-by-step guidance for endpoints, site pilots, and scaling across multi-site operations.
-
Scenario and sensitivity analyses: market and cost scenarios that quantify the downside of delayed modernization vs. the upside of proactive deployment.
-
Competitive profiles and go-to-market insights: capability matrices for leading vendors with suggested partnership frameworks and negotiation levers.
Note: the full study also contains granular regional, technology and end-use segmentation and forecasts. In keeping with our “trailer” approach, we summarise directional insights here while holding proprietary segment detail for report subscribers.
How to Translate Insight into 2026 Action
-
Prioritise pilot investments now, not later. Use a 9–12 month pilot cycle to validate instrument selection against daily production realities and analytics integration requirements. Our models show that early pilots materially reduce scale-up rework.
-
Negotiate performance-based contracts. Where feasible, structure vendor agreements to include uptime SLAs, calibration schedules and outcome-linked service credits to manage operational risk.
-
Integrate regulatory-readiness into procurement specs. If your products enter markets with aggressive recyclability or EPR mandates, include test-agent restrictions and documentation requirements in RFPs to avoid non-compliant instrument acquisitions.
-
Plan for data interoperability. Require open APIs or standardized exports so inspection data can feed into SPC and traceability systems; obsolescence risk is highest for closed, proprietary test units.
-
Build multi-vendor resilience. Given mid-market consolidation and regional vendor strengths, consider a dual-sourcing strategy that balances performance with supply security and service proximity.
Conclusion — Why This Matters for 2026
The portable package leak detector market is growing steadily and is increasingly strategic for firms where product integrity, regulatory compliance and recyclability intersect. The 6.68% CAGR and the trajectory toward over USD 1 billion by 2032 create both investment opportunities and exposure to supply, regulatory and material-cost shifts. For executives and technical leaders planning 2026 budgets, the choice is not simply which instrument to buy — it is how inspection strategy becomes a lever for risk mitigation, differentiation and lifecycle cost control.
PW Consulting’s full report equips decision-makers with the vendor intelligence, procurement tools, and regulatory mappings required to make those choices with confidence. To access the full dataset, detailed segmentation, and our actionable playbooks, visit PW Consulting’s Portable Package Leak Detector Market portal or contact our industrial instrumentation practice for a briefing.
For detailed analysis of this topic, please visit the official page: Portable Package Leak Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com