

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fixed Wing Aircraft Rivets Market to Reach USD 1,435.25 Million by 2032, Driven by a 5.26% CAGR

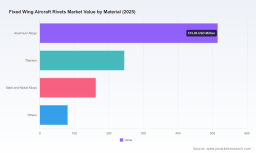
Fixed Wing Aircraft Rivets Market: Strategic Imperatives for 2026 — Preview of PW Consulting’s In-Depth Market Study
As fixed-wing airframe programs move past pandemic-era shocks and into a phase of disciplined modernization and sustainability-driven redesign, rivet supply and fastening strategies are quietly re-emerging as a critical vector for cost, performance and regulatory compliance. PW Consulting’s latest Fixed Wing Aircraft Rivets Market report — built on a 2020–2025 historical base and projecting across 2026–2032 — synthesizes market sizing, supplier economics, technology inflection points and regulatory triggers that procurement, program management and engineering leaders must factor into their 2026 decision calendars.
Fixed Wing Aircraft Rivets Market
Market pulse: the headline numbers that shape near-term choices
After steady recovery and modest expansion through 2020–2025, the global fixed wing aircraft rivets market reached roughly USD 1,002.5 Million in 2025. Our base-case outlook positions the market at about USD 1,076.3 Million in 2026, and growing at a compound annual growth rate (CAGR) of 5.26% across the 2026–2032 forecast window. By 2032 the market is projected to exceed USD 1.4 billion under the baseline scenario, reflecting a steady combination of fleet renewals, rising production rates for narrow- and wide-body platforms, and incremental demand from military modernization and general aviation segments.
Fixed Wing Aircraft Rivets Market
Those macro figures mask important structural shifts. The rivets market is neither a pure commodity nor fully consolidated: our concentration analysis shows a mid-range supplier consolidation dynamic, with the top three and top five firms collectively holding meaningful but not overwhelming shares of market value. That balance creates both procurement risk — single-source exposure for certain classes of rivets and materials — and opportunity: niche specialists can still command premium positions where technical certification and process control matter most.
Fixed Wing Aircraft Rivets Market
Why this study matters to executive teams in 2026
- Procurement & supplier strategy: With a market trajectory that is unambiguous but nuanced, buyers need to move from transactional sourcing towards multi-tiered supplier strategies that combine long-term agreements for standard parts with flexible, certified suppliers for specialty alloys and blind-fastening technologies.
- Product engineering: Design teams must internalize changing standards for composite-to-metal joints and electrical bonding — decisions made now will drive fastener specification and inspection regimes across new-build and retrofit programs.
- Operations & cost control: Production planners should incorporate rivet lead times, certification queues and supplier capacity into critical-path modeling; small shifts in rivet availability can produce outsized impacts on final assembly takt times.
- Regulatory compliance & safety: New and evolving standards introduce testing, traceability and sometimes redesign costs. Our research helps risk-manage certification timelines and prioritize investment in compliance-driven fasteners.
What the PW Consulting report delivers — practical, actionable content
This study was built to be immediately usable by strategy, procurement, engineering and M&A teams. Highlights include:
- Robust market sizing and scenario-based forecasts (base, upside, downside), including sensitivity to production-rate uplifts and raw material price shocks.
- Supplier scorecards and capability matrices mapping manufacturing footprints, AS/EN/AS9100 certifications, DFARS and traceability posture, and in‑house quality control processes.
- Technology and product taxonomy that clarifies where blind rivets, solid rivets and specialty fasteners are advancing — and where they remain legacy cost centers.
- Regulatory impact analysis that translates recent certification updates into decision pathways for design verification, bonding strategies and inspection plans.
- Procurement playbooks with negotiation levers, dual-sourcing templates, and inventory hedging tactics tuned to rivet-specific supplier constraints.
- Risk register and contingency planning for supply shocks, including practical mitigation steps for raw material volatility and single-sourced alloy dependencies.
- Deal pipeline and M&A opportunity mapping highlighting where scale, vertical integration and technical IP provide defensible advantage.
To preserve the strategic utility of this executive preview, detailed segment-level splits, proprietary pricing models and supplier-level revenue figures are reserved for the full report. Those datasets are the core intelligence that procurement and corporate development teams will use to make binding 2026 commitments.
Competitive landscape — who matters and why
The rivet space for fixed wing aircraft blends global fastener groups, regional specialists and vertically integrated manufacturers focused on aerospace-grade specifications. Our competitive analysis profiles leaders whose product portfolios and certification footprints materially affect program risk and supplier selection.
- National Rivet & Manufacturing Co. (Waupun, WI) — A vertically integrated solid-rivet manufacturer with deep airframe experience. Their in-house quality control, DFARS-compliant materials and multiple aluminum alloy offerings make them a go-to for assemblies that demand traceability and certified tensile properties.
- Howmet Fastening Systems (Howmet Aerospace) — A portfolio leader in blind rivet technology engineered for limited-access aerospace structures. Their high-performance product lines are designed to meet stringent NAS and MIL specifications, and are particularly relevant where one-sided installation and hole-filling performance reduce assembly risk.
- Cherry Aerospace (SPS Technologies) — A specialist in locked-spindle and hole-filling blind rivet systems. Their solutions are widely used on composites and critical leading/trailing edge structures where controlled installation and fatigue performance matter.
- LISI AEROSPACE — A global fasteners integrator that pairs high-tech rivet systems with structural fastening systems, supporting OEMs that pursue standardized global sourcing and engineering-to-manufacture coordination.
- Hanson Rivet & Supply Co. and RISCO Fasteners — Regional and custom print-compliant suppliers who remain strategically important for maintenance, repair & overhaul (MRO) and bespoke airframe requirements where MS/NAS prints or tailored alloys are specified.
The market’s current concentration landscape — where a moderate share is held by the largest players while significant value remains with specialists — creates a procurement frontier where strategic supplier segmentation pays off. Large OEMs will balance long-term commitments with targeted partnerships for specialty alloys and high-integrity blind fastening solutions.
Regulation, materials and technology: the dynamics shaping 2026 choices
- Certification updates and electrical bonding: Recent updates to certification expectations for blind fastening systems — particularly in composite-to-metal joints — impose new electrical bonding standards that intersect directly with fuel tank safety and lightning protection strategies. Program teams should expect extended validation cycles for affected fastener classes.
- Material evolution: Titanium and aluminum alloys will continue to dominate design conversations as teams trade strength for weight. At the same time, advanced nickel alloys and engineered blind rivet systems are emerging where thermal or extreme-environment performance is required.
- Smart fasteners & testing regimes: National testing protocols and sustainable metals strategies are accelerating development of sensor-enabled blind rivets and novel inspection requirements. These introduce opportunities to leapfrog traditional NDT cycles but also demand early investment in testbeds and certification pathways.
- Manufacturing sustainability: OEM initiatives to cut energy use and waste on assembly lines — including recent equipment releases targeting lower-impact riveting processes — will factor into supplier selection and capital allocation decisions at prime contractors.
- Advanced programs: High-temperature and hypersonic airframe projects are driving R&D for nickel-alloy blind rivets and other specialty solutions; initial funding and SBIR awards indicate longer-term market niches with elevated barriers to entry.
Strategic playbook for 2026 — five priority actions
- Segment suppliers by risk and strategic value: Classify rivet families into strategic, tactical and commoditized pools. Lock long-term agreements for strategic alloys and methods while driving cost competition for commoditized lines.
- Prioritize certification lead indicators: Build certification roadmaps into procurement timelines. Where EASA/NIST changes apply, require supplier validation plans and integrate certification milestones into program gates.
- Invest selectively in testbeds and partnerships: Co-fund supplier pilot programs for smart blind rivets and advanced blind-fastening tooling to gain early access to performance data and preferential supply terms.
- Hedge raw material and capacity risk: Adopt inventory and contract hedges for critical alloys; evaluate near-shore or dual-source strategies for high-risk components to reduce single-point-of-failure exposure in final assembly.
- Embed fastener economics into systems engineering: Ensure fastener choice and installation method are part of weight, fatigue and lifecycle cost analysis from concept through to sustainment planning.
Next steps — how to use this preview
This preview outlines the strategic contours we expect to drive rivet sourcing, specification and design decisions in 2026. For teams preparing contract awards, engineering specifications, MRO sourcing strategies, or M&A diligence, the full PW Consulting Fixed Wing Aircraft Rivets Market report contains the granular intelligence — supplier financial benchmarks, certified material mappings, price curves, and proprietary scenario models — necessary to move from high-level strategy to executable plans.
For access to the complete dataset and bespoke consulting support tailored to program-specific requirements, please refer to the PW Consulting publications page or contact our aerospace practice. The full report is intentionally data-rich: proprietary segment breakdowns and supplier-level metrics are available only through the primary report package to preserve the strategic value of the analysis and to support rigorous decision-making in 2026.
Author
PW Consulting — Aerospace Practice. Lead analyst: Senior Strategy Consultant & Chief Industry Analyst.
For detailed analysis of this topic, please visit the official page: Fixed Wing Aircraft Rivets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com