

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Desktop Industrial Robot Market Poised to Reach USD 1,992.14 Million by 2032, Fueled by 13.52% CAGR

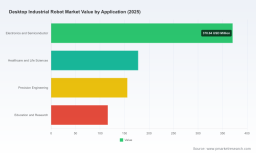
Desktop Industrial Robot Market — 2026 Strategic Outlook (PW Consulting)
PW Consulting's latest Desktop Industrial Robot Market study—anchored on a 2025 base year and projecting through 2032—translates a high-growth technology wave into executable strategy for 2026 decisions. The market has recorded strong expansion since 2020 and, driven by Industry 4.0 adoption, rising labor costs, and compact automation demand, is forecast to sustain a compound annual growth rate of approximately 13.52% through 2032. By our central scenario the addressable market moves from a mid‑single‑digit‑hundreds million USD base in 2025 into the vicinity of USD 2 billion by 2032. This report is written for executives who must convert that growth trajectory into low‑risk, high‑velocity deployment plans in the coming 12–18 months.
Desktop Industrial Robot Market
Why this report matters to 2026 corporate decision-makers
-
Timing and scale: The desktop robot category is no longer experimental. The quantitative momentum—backed by five years of historical data and a robust mid‑teens CAGR—creates a practical imperative for procurement, operations, and engineering functions to move from pilot to production-readiness in 2026.
Desktop Industrial Robot Market -
Risk management: Supply‑chain volatility in primary metals (steel and precision aluminum alloys), evolving safety standards (ISO 10218 and ISO/TS 15066), and fast‑moving product innovation all alter deployment risk profiles. Our report maps these risks to mitigation playbooks that can be applied immediately.
Desktop Industrial Robot Market -
Competitive positioning: Desktop robots are being used to increase throughput and quality in small‑lot manufacturing and benchtop production. Companies that define and operationalize clear automation roadmaps in 2026 will capture first‑mover efficiency gains in high‑mix, precision segments.
What you will find in the report — practical, deployment‑centric deliverables
-
Executive dashboard: concise market sizing, validated growth drivers, and scenario matrices to stress test capital vs. service‑led investment paths.
-
ROI and TCO engines: ready‑to‑use financial models calibrated for desktop robot economics—covering acquisition, integration, programming, maintenance, and operator‑retraining costs, with sensitivity to utilization and labor‑substitution rates.
-
Use‑case playbooks: prioritized templates for common benchtop applications (precision assembly, electronic handling, life‑science sample processing, lab automation), including floorplan footprints, safety envelopes, and cycle‑time heuristics.
-
Integration checklist: electrical, mechanical, controls, and IT/Cybersecurity requirements; examples of adapter architectures for common end‑effectors and vision systems.
-
Vendor selection toolkit: decision criteria and scorecards aligned to buyer archetypes (volume OEM, contract manufacturer, R&D lab, university/teaching) and service models.
-
Procurement playbook: sourcing strategies (direct purchase, bundled systems, managed services), warranty and spare‑parts terms to prioritize, and pilot‑to‑scale contracting roadmaps.
-
Workforce transition module: role maps for resilient automation teams, competency frameworks, and a 12‑month training syllabus for operators and line engineers.
-
Scenario forecasting: three forward scenarios (conservative, base, accelerated) that translate the base CAGR into operational capacity planning and capital phasing guides.
Competitive landscape — vendor archetypes and strategic implications
The desktop robot market is characterized by a mix of specialized incumbents, precision‑engineering niche players, and fast‑moving Chinese OEMs. Market concentration metrics indicate a moderate level of consolidation at the top; the three largest players do not yet dominate the category outright, leaving room for differentiated propositions and services.
-
Janome (Japan) — Strong in desktop Cartesian systems for precision dispensing, screwing and small‑footprint assembly. Ideal for buyers prioritizing tried‑and‑tested mechanical reliability in high‑repeatability tasks.
-
Dobot / Shenzhen Yuejiang Technology (China) — Fast product cadence and cost‑competitive 4‑axis and collaborative desktop models; attractive for benchtop production and lightweight pick‑and‑place deployments where time‑to‑value is critical.
-
DENSO Robotics (DENSO WAVE) (Japan) — A reputation for compact SCARA and small assembly robots; a sensible option for mature OEMs seeking vendor longevity and broad application support.
-
Mecademic (Canada) — Provider of extremely compact, precise 6‑DoF arms; differentiation by precision and speed makes it a fit for micro‑assembly and laboratory automation use cases.
-
TOYO Robotics, TM Robotics, NITTOSEIKO (Japan & UK) — Specialists and channel partners offering Cartesian and electric‑actuator based systems suited for highly engineered desktop tasks and retrofitting into existing jigs.
-
Elephant Robotics (China) — Focused on collaborative 6‑DoF arms for education and light industrial use, with a platform approach that supports third‑party tooling.
-
USABotics (USA) — North American manufacturing and supply chain proximity; strategic for buyers with domestic sourcing or regulatory/IT constraints.
Recent industry activity underscores the pace of product and channel evolution: major collaborative arm launches have pushed payload and speed envelopes, vendors showcased expanded desktop portfolios at global trade shows, and ecosystem events highlighted practical integration of small‑format robots into smart‑factory cells. These developments compress technical risk for standardized tasks and raise the bar on service and integration as points of differentiation.
Deployment patterns and common adoption archetypes
-
High‑mix/low‑volume manufacturers are using desktop robots to sustain high quality across small batches without large capital commitments to full‑size automation.
-
Electronics and precision engineering shops deploy desktop units for repetitive subassembly and testing operations, where cycle time and footprint are critical.
-
Life‑sciences and lab environments pair compact robots with sample‑handling tooling to increase throughput while meeting strict safety and traceability requirements.
-
Education and R&D contexts leverage collaborative desktop arms for training and rapid prototyping, feeding a talent pipeline for industrial automation.
Each archetype implies different procurement and lifecycle considerations: plug‑and‑play systems favor OEMs with standardized software stacks and cloud‑enabled monitoring, while high‑precision applications demand longer‑term service contracts, calibration plans, and spare‑parts strategies.
Top strategic moves for 2026
-
Run modular pilots tied to clear economic thresholds. Define a 6–9 month pilot with success metrics (throughput, yield delta, mean time to integrate) that convert into a go/no‑go decision to scale.
-
Adopt a staged procurement strategy. Combine purchase and pay‑per‑use models to balance cashflow and accelerate learning while retaining flexibility against rapid product improvements.
-
Prioritize integration partners. Select vendors or system integrators with proven device‑level APIs, local service coverage, and a clear roadmap for vision and force‑feedback tooling.
-
Embed safety and cybersecurity early. Map ISO requirements to cell design and insist on patch‑management and network segmentation for collaborative deployments.
-
Invest in workforce transition. Protect productivity during automation rollout by cross‑training technicians and creating operator certification pathways.
-
Use data to govern scale decisions. Leverage real‑time telemetry to validate utilization assumptions in TCO models before committing to fleet purchases.
How PW Consulting lowers execution risk
This report is engineered as an execution tool, not just a market narrative. Beyond the headline market trajectory (13.52% CAGR to 2032), our outputs include decision matrices, contract templates, and calibrated financial models that let procurement leads convert abstract growth into staged investments and measurable operational KPIs. Scenario models let you stress test strategic choices—what happens to payback when utilization is 10% lower than plan, or when spare‑parts lead times double because of metal market shocks? Our playbooks convert those answers into immediate next steps.
For senior leaders preparing 2026 capital plans, the strategic value is clear: this is the point to move desktop robotics from pilots into rigorous, scalable programs that are economically defensible and operationally resilient. PW Consulting’s Desktop Industrial Robot Market report provides the tactical scaffolding—vendor scorecards, ROI templates, and integration checklists—to help you do exactly that with less ambiguity and faster time to value.
To access the full intelligence suite—detailed scenario spreadsheets, vendor scorecards, integration templates, and the comprehensive appendix of standards and supply‑chain considerations—request the report from PW Consulting. The executive summary provides the strategic narrative; the report body supplies the operational playbooks you will use in 2026.
For detailed analysis of this topic, please visit the official page: Desktop Industrial Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com