

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Oil & Gas Drones Market Poised to Soar at a 19.12% CAGR, Revolutionizing Inspection and Monitoring

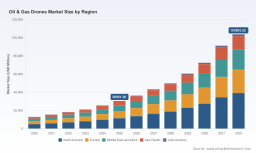
Oil & Gas Drones Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting today releases a strategic preview of our forthcoming Oil & Gas Drones Market report (base year 2025, historical coverage 2020–2025, forecast 2026–2032). The industry is entering a phase of disciplined scale-up: PW’s macro model projects a sustained compound annual growth rate (CAGR) of 19.12% across the forecast window, lifting total industry revenues from the mid‑tens of billions in 2025 into the low‑hundreds of billions by 2032 (USD, revenue unit: Million). For executives planning capital allocations, vendor strategy, or regulatory engagement in 2026, these macro dynamics demand immediate strategic response.
Oil Gas Drones Market
Why this report matters for 2026 decisions
- Acceleration from experiment to enterprise: After a multi‑year phase of pilots, operators are moving toward structured deployments where drone programs must generate measurable productivity, safety and ESG outcomes. The market trajectory reflected in our forecast signals that 2026 will be a pivotal year for converting pilots into governed, repeatable operations.
- Risk and regulatory inflection points: Recent regulatory actions — notably PHMSA’s integration of UAS into pipeline right‑of‑way patrol frameworks and FAA/PHMSA guidance on risk‑based transport of hazardous materials by commercial UAS — are lowering barriers to expanded operational use while introducing compliance complexity that requires specialised policy playbooks.
- Technology divergence: Hardware commoditisation on some fronts sits alongside rapid differentiation in autonomy, sensor fusion (LiDAR, thermal, methane sensing), and analytic platforms. Investment choices made in 2026 will determine whether an operator secures long‑term operational advantage or incurs costly rip‑and‑replace cycles.
What the PW Consulting report delivers (practical, operational intelligence)
- Market sizing and trajectory aligned to commercial planning horizons: historical 2020–2025 baselines, 2026–2032 scenarios, and sensitivity testing under alternative adoption curves.
- Technology maturity and application mapping: where multirotor, fixed‑wing, hybrid and specialist platforms are most operationally appropriate, and what performance thresholds matter to different asset classes (onshore pipelines, offshore platforms, confined spaces).
- Procurement and vendor evaluation frameworks: scorecards for hardware, analytics, and managed‑service partners that translate technical features into procurement criteria and SLA language.
- Operational playbooks: pilot-to-scale roadmaps, flight operations centres (FOC) design, BVLOS risk matrices, data governance and integration checklists for SCADA and asset integrity systems.
- Regulatory and compliance toolkit: a regionally aware matrix of current constraints, practical mitigations, and stakeholder engagement scripts to manage permissions, hazardous‑materials transport guidance, and restrictions impacting contractors.
- Financial models and TCO templates: CAPEX vs OPEX trade-offs, leasing vs purchase scenarios, cost per inspection models and ROI thresholds mapped to different use cases.
- Vendor landscape and M&A readiness: competitive positioning, partnership archetypes, and integration risk assessments to support carve‑outs and alliances.
- Field case studies and quantitative performance benchmarks drawn from operator deployments and third‑party service engagements.
Strategic takeaways for 2026
- Design for coexistence, not replacement. Drones are becoming part of the asset monitoring ecosystem rather than a stand‑alone solution. Successful programs deploy drones as sensors that feed established integrity and incident response workflows.
- Prioritise vendor sovereignty and supplier diversity. Regulatory developments have introduced procurement exposure for some buyers. A pragmatic mitigation is a diversified supplier mix and contractual clauses that preserve continuity should hardware and software substitution become necessary.
- Move from proof‑of‑value to repeatable KPIs. Establish inspection‑cycle KPIs, data quality SLAs, and incident‑avoidance metrics that allow clear commercialization of drone programs within 18 months.
- Invest in data orchestration. The real value lies in integrating aerial data into asset management systems and predictive maintenance models; analytics partnerships and shared data standards should be prioritised.
- Create a regulatory playbook. With PHMSA and FAA guidance evolving, operators should maintain a live compliance register, pre‑approved operational profiles and an engagement plan for state and federal authorities.
Competitive landscape — who matters and what they bring
The vendor ecosystem is diverse, combining specialised hardware OEMs, autonomous software providers, and full‑service inspection firms. Market concentration remains moderate — the top vendors together account for a meaningful share but not a dominant lock‑in — which keeps opportunity open for new entrants and service integrators.
Oil Gas Drones Market
- DJI Enterprise (China) — Offers industrial multirotor platforms with a broad accessory ecosystem (thermal, gas detection, LiDAR). Its scale and payload flexibility make it a default choice for many inspection workflows; procurement teams must, however, weigh geopolitical and compliance considerations where jurisdictional restrictions apply.
- Flyability (Switzerland) — Specialises in collision‑tolerant indoor systems, uniquely positioned for confined‑space and tank interior inspections. Their technology materially reduces shutdown risk for internal inspections, creating value in environments where access is limited.
- Terra Drone (Japan) — A service‑led player combining hardware agnosticism with global operations. Their offering is tailored to turn‑key deployments, attractive to operators seeking rapid scale without developing internal flight capabilities.
- Cyberhawk Innovations (UK) — Focuses on inspection services plus analytics, anchoring its value in the integration of aerial capture with asset integrity workflows for complex offshore assets.
- AeroVironment & Insitu (United States) — Providers of tactical, long‑endurance UAS suited to remote and rugged onshore/offshore scenarios where range and persistence matter.
- Delair & Microdrones (Europe) — Fixed‑wing and LiDAR‑centric providers tailored for long‑range corridor surveying and volumetric mapping across pipeline networks.
- Skydio & Acecore Technologies (United States / Netherlands) — Emphasise autonomy and modular payload platforms respectively; both are advancing the case for reduced operator workload and higher‑fidelity sensing in complex operational environments.
- ZIYAN UAS & PrecisionHawk — Combine platform capabilities with AI recognition and analytics stacks to support automated fault detection and enterprise data ingestion.
For procurement leaders, the strategic question is not only which vendor to select today but how to architect a vendor ecosystem that supports continuous capability upgrades, data portability and regulatory resilience.
Oil Gas Drones Market
Regulatory and policy dynamics shaping 2026 strategy
- Operational authorisation is expanding, but conditional. PHMSA’s recent integration of UAS into pipeline right‑of‑way patrol frameworks and FAA/PHMSA guidance on hazardous materials transport enable broader operational use, yet they also require operators to demonstrate risk‑based controls and traceable compliance.
- Jurisdictional and contractor restrictions are real procurement risks. Policies adopted in late 2025 that restrict certain suppliers on federally funded projects, alongside state‑level constraints on operations near critical infrastructure, mean that sourcing strategies must include legal and geopolitical risk screening.
- Standards and interoperability will drive adoption. As regulators and industry bodies converge on data and operational standards, early alignment will lower marginal compliance costs and speed approvals for BVLOS and hazardous‑materials applications.
Methodology and what to expect in the full report
PW Consulting’s forecast combines bottom‑up deployment modelling with top‑down market indicators, scenario testing and primary interviews with operators, vendors and regulators. The report’s base year is 2025, with historical data across 2020–2025 and projections through 2026–2032. Core macro outputs include the market trajectory and a 19.12% CAGR for the forecast period (USD, revenue unit: Million). Detailed appendices cover methodology, assumptions and sensitivity analyses.
How senior leaders should use this intelligence in 2026
- Immediate (next 90 days): Initiate a supplier risk review and a two‑track pilot plan (safety‑critical use cases + revenue‑generating services), and establish a compliance watchlist aligned to PHMSA/FAA guidance.
- Near term (6–12 months): Operationalise an analytics ingestion pipeline, finalise an SLA framework for data quality, and structure procurement agreements to include upgrade and substitution clauses.
- Medium term (12–24 months): Scale successful pilots into routine inspection programs, pursue partnerships for methane detection and emission quantification, and evaluate in‑house vs managed‑service tradeoffs using PW’s TCO templates.
Next steps
This preview outlines the strategic contours that will define winners and laggards as the Oil & Gas Drones Market transitions from fragmented innovation to industrialised deployment. PW Consulting’s full report offers the granular segment data, vendor scorecards and deployment toolkits required to make procurement, operational and investment decisions with confidence. To obtain the full dataset, vendor matrices and executable playbooks that accompany this strategic analysis, please visit the PW Consulting report portal.
For detailed analysis of this topic, please visit the official page: Oil Gas Drones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com