

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Chip Encapsulation Resin Market Tops USD 3,892.6 Million in 2025 — Strong Outlook for 2026–2032

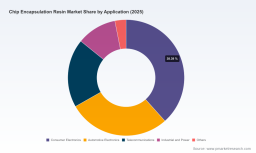
Chip Encapsulation Resin Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
As semiconductor packaging evolves to meet the throughput and thermal demands of AI accelerators, automotive power electronics, and next‑generation consumer devices, the chip encapsulation resin market is entering a structurally higher‑value phase. Our PW Consulting forecast (base year 2025) shows the global market expanding from an estimated USD 3,892.6 Million in 2025 to roughly USD 6,169.3 Million by 2032 at a compound annual growth rate (CAGR) of 6.81% over the 2026–2032 forecast window. For senior executives and investment committees planning priorities in 2026, this is not a niche materials play — it is a critical input market whose dynamics will shape supplier selection, qualification timelines, and capital allocation across semiconductor supply chains.
Chip Encapsulation Resin Market
Why this matters in 2026
- Technology-led demand acceleration: Advanced packaging formats and power-dense modules increase technical requirements for encapsulants (thermal conductivity, high glass transition temperature (Tg), low ionic contamination and ultra‑low alpha emission). These performance vectors create premium segments with longer qualification cycles and higher switching costs.
- Supply-side consolidation and concentration: The top suppliers command a material share that creates both stability and strategic risk. Our analysis indicates a concentrated supplier landscape among the leading three and five players, making strategic sourcing and dual‑sourcing policies essential for OEMs and OSATs alike.
- Input-price and policy sensitivity: Volatility in epoxy feedstocks and regional trade measures materially affects landed costs and supplier competitiveness, directly influencing near‑term margin profiles for both materials suppliers and packagers.
What PW Consulting’s report delivers — practical content for decision-makers
This report is designed as an operational playbook for executives, procurement heads, and R&D leaders making 2026 decisions. It combines rigorous quantitative forecasting with executable tools:
Chip Encapsulation Resin Market
- Validated market sizing and seven‑year forecasts at the global level (2026–2032), including scenario stress tests for lower/higher demand and feedstock‑price shock inputs.
- Segment‑level demand drivers mapped to technical performance attributes (e.g., thermal conductivity, Tg, moisture resistance, low alpha), and an aligned qualification timeline estimate for each packaging class.
- Supply‑chain risk matrix covering capacity expansions, geopolitical exposure, logistics choke points, and single‑source dependencies — with remediation playbooks including near‑term contracting strategies and medium‑term localization options.
- Raw material watch: a dynamic model linking bisphenol‑A, epichlorohydrin and other precursor costs to finished resin pricing, including sensitivity analyses that quantify margin impact under different feedstock scenarios.
- Competitive intelligence dossiers with supplier scorecards, production footprints, recent capex and JV activity, product positioning, and product roadmaps — enabling faster supplier selection and partnership diligence.
- Commercial templates and procurement tools: RFP language tuned to packaging qualification needs, a supplier evaluation checklist for encapsulant performance and reliability, and a capex prioritization framework for converters and compounders.
Competitive landscape — who matters and why
The chip encapsulation resin ecosystem is populated by vertically integrated chemical majors, specialized resin manufacturers, and diversified materials businesses. Key players we profile in depth include:
Chip Encapsulation Resin Market
- Sumitomo Bakelite Co., Ltd. (Tokyo) — a market leader in epoxy molding compounds (EMC) with recent capacity expansions and new plant commissioning to address demand from AI packaging and automotive power modules. Their investments indicate an aggressive push to capture higher‑value EMC mix.
- Shin‑Etsu Chemical Co., Ltd. (Tokyo) — leveraging deep silicon‑chemistry integration to supply low‑alpha, moisture‑resistant grades favored in advanced logic and memory packaging.
- Henkel AG & Co. KGaA (Düsseldorf) — diversified adhesives and encapsulants portfolio, recently launching thermally conductive EMC grades aimed at EV power electronics (announced March 2025), positioning Henkel at the intersection of thermal management and encapsulation chemistry.
- Resonac Holdings Corporation (Tokyo) — focused on heat‑resistant EMC (e.g., CEL‑400 series) engineered for high‑Tg performance in power semiconductor packages.
- Nitto Denko, Mitsubishi Chemical, Kyocera, Samsung SDI, LG Chem, Huntsman, Evonik, Chang Chun Group (including Chang Wah), and Panasonic — each brings complementary capabilities from ultra‑low alpha formulations to application‑specific flowability and thermal performance.
Recent activity underscores two strategic themes: targeted capacity additions (notably by Sumitomo Bakelite across Japan and China) and product innovation toward thermally conductive and high‑Tg formulations (Henkel’s March 2025 launch). These moves are shaping market access for OEMs and creating near‑term qualification bottlenecks for challengers.
Macro inputs and risk signals to watch in 2026
- Feedstock prices: Epoxy resin prices in Northeast Asia have shown downward pressure (e.g., reported at ~USD 1.96/kg in December 2025), reflecting softer electronic encapsulation demand and easing upstream feedstock costs. Simultaneously, bisphenol‑A prices in China fell significantly through 2025 — a factor that can compress manufacturer margins but also enable competitive pricing strategies for aggressive converters.
- Trade and regulatory friction: European import volumes of epoxy resins declined during 2025 amid anti‑dumping actions and regional oversupply. Regulatory compliance (REACH and SVHC) continues to influence formulary choices; many mainstream encapsulant products already comply, but evolving substances of concern can create reformulation costs and product‑requalification needs.
- Concentration and qualification timelines: With the market exhibiting significant CR3 and CR5 concentration, single‑supplier disruptions can create outsized supply shocks. Qualification cycles for new encapsulant chemistries typically span multiple quarters, so procurement actions taken in 2026 will influence supply stability into 2027–2028.
Strategic recommendations for 2026
PW Consulting’s analysis yields five near‑term imperatives for firms operating across the value chain.
- Embed material strategy into product roadmaps: Semiconductor OEMs and OSATs should align encapsulant specifications with packaging roadmaps now. Early alignment reduces rework and shortens qualification time-to-revenue for new package types.
- Adopt a tiered sourcing model with technical dual‑sourcing: For critical, high‑thermal or ultra‑low alpha grades, require primary/secondary supplier commitments and prioritize suppliers that demonstrate local capacity or JV footprints aligned with your production sites.
- Hedge feedstock exposure operationally: Use blended procurement (long‑term contracts + indexed spot buys), maintain safety stocks for critical precursor chemicals, and evaluate backward integration or strategic equity stakes in resin producers where volume and margins justify.
- Prioritize supplier validation for thermal and reliability metrics: Include accelerated life testing and field simulation early in the procurement process; prefer suppliers with demonstrated high‑Tg and thermally conductive product lines and published compliance with REACH/SVHC where applicable.
- Monitor M&A and JV activity for access: Capacity expansions and joint ventures — especially in Asia — can create opportunities for off‑take agreements or co‑development partnerships that secure differentiated material supply and shorten logistics legs.
How to use the full PW Consulting report
This article is a strategic preview highlighting the most consequential trends and choices for 2026. The full PW Consulting Chip Encapsulation Resin Market report contains the comprehensive data sets, regional and application microforecasts, supplier scorecards, price‑sensitivity models, and procurement contract templates required to operationalize the recommendations above. To preserve the strategic advantage of subscribers and partners, detailed segment tables and granular revenue splits are available exclusively in the report’s download package and interactive dashboard on our website.
Closing perspective
The chip encapsulation resin market in 2026 is not simply about volume growth; it is about capability differentiation. As packaging complexity rises, the premium attached to advanced resin chemistries will grow faster than the market average, and the cost of getting material strategy wrong will become measurable in lost production throughput, failed qualifications, and higher lifecycle costs. PW Consulting’s preview is intended to help leaders convert market forecasts into concrete procurement, R&D, and capital priorities for 2026. For teams preparing budgets, negotiating supplier agreements, or planning capacity investments, the next 12 months are a turning point — and the right data and playbooks will determine who captures the upside.
Access the full intelligence
For the complete market model, supplier dossiers, and actionable templates referenced in this preview, please visit PW Consulting’s Chip Encapsulation Resin Market report page to download the full study and request a briefing with our lead analysts.
For detailed analysis of this topic, please visit the official page: Chip Encapsulation Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com