

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Polyacrylate Rubber (ACM) Market to Top USD 1,306.65 Million by 2032 on 5.1% CAGR, Led by Asia‑Pacific

Polyacrylate Rubber (ACM) Market 2026 Outlook: Strategic Imperatives for Decision‑Makers
PW Consulting’s latest Polyacrylate Rubber (ACM) Market report offers executive leaders and strategy teams a forward‑looking roadmap to navigate a market that is entering a new phase of consolidation, raw‑material sensitivity, and product differentiation. The global ACM market, which expanded from an estimated USD 735.25 Million in 2020 to USD 922.45 Million in our base year of 2025, is forecast to grow at a 5.1% CAGR through our 2026–2032 forecast window. By 2032, modeled topline scenarios show the market approaching roughly USD 1.31 Billion under our central-case projection. These headline numbers frame the strategic choices companies will need to make in 2026 to protect margins, secure supply, and capture premium applications.
Polyacrylate Rubber Acm Market
Core market intelligence — what this release delivers
-
Verified macro baseline: multi‑year historical sizing (2020–2025) and bottom‑up revenue modeling to support scenario testing for 2026–2032 planning cycles.
Polyacrylate Rubber Acm Market -
Industry concentration insight: our analysis identifies a high degree of market concentration at the top, with the three largest producers accounting for the majority share of production and the five largest approaching an even larger cumulative presence—dynamics that favor coordinated pricing power in tight upstream conditions.
Polyacrylate Rubber Acm Market -
Supply‑chain risk heatmap: near‑term supply shocks tied to regional environmental inspections, utility load controls, and monomer pricing volatility are quantified and mapped to producer and downstream exposure.
-
Practical playbooks: procurement playbooks, price‑index hedging templates, product‑roadmap decision matrices, and M&A checklists designed to be directly executable by commercial and strategy teams.
-
Competitive benchmarking: qualitative and quantitative profiles of leading ACM suppliers, with capability matrices covering grade portfolios, manufacturing footprint characteristics, and go‑to‑market models.
Why 2026 is a strategic inflection point
Three converging forces make 2026 a pivotal year for ACM players and their customers. First, raw‑material cost dynamics remain a central margin driver. Our market surveillance observed a notable step‑up in upstream pricing in early 2026—large producers announced list price increases on key acrylic monomers, and regional monomer markets displayed constrained availability due to regulatory inspections and power management measures. Second, downstream demand is being reshaped by higher performance requirements from automotive powertrain and industrial sealing applications, driving interest in specialty ACM grades (high‑temperature, oil‑resistant, and low‑temperature hybrids). Third, market structure is tilting toward higher concentration: the top players already control a material share of capacity, which magnifies the impact of strategic moves by a handful of large suppliers.
For corporate leaders, these dynamics translate into three immediate strategic needs for 2026: protect margin through disciplined cost management and selective pass‑through pricing; secure flexible access to monomer and intermediate supplies; and selectively invest in product differentiation or downstream integration to capture value beyond commoditized rubber grades.
Recent industry events and implications
-
Upstream price actions: Major chemical manufacturers announced list price increases on acrylic monomers in early 2026. These moves are not transitory—our benchmarking shows that even modest per‑unit increases materially change ACM conversion economics and justify both procurement hedging and formula adjustments for certain compound grades.
-
Regional supply tightness: regulatory inspections and utility load control measures in key production regions temporarily constrained spot availability, tightening local supply/demand balances and amplifying spot price swings. Procurement teams should expect episodic regional stress events and incorporate contingency sourcing into their 2026 supply plans.
-
Capacity and capability shifts: selective capacity additions in elastomer processing and promoter production among major players are easing certain bottlenecks but also raise the bar on quality and grade breadth required to compete in premium OEM supply chains.
Competitive landscape — players to watch
Our competitive mapping focuses on companies with distinct ACM capabilities and relevant strategic footprints. The market is anchored by established specialty chemical and compounders that combine proprietary grades with deep automotive qualifications. Notable firms profiled in the report include:
-
ZEON Corporation (Tokyo) — recognized for a broad ACM portfolio with high heat and oil resistance grades and engineered low‑temperature variants for molded parts.
-
NOK Corporation (Tokyo) — a major supplier of ACM compounds and components, particularly in oil seals and gaskets, with strong downstream OEM relationships.
-
HEXPOL Rubber Compounding (Malmö) — focused on automotive and transportation sectors, with emphasis on ATF and engine oil resistance for transmission and engine sealing applications.
-
RADO Gummi GmbH (Germany) — produces acrylic rubbers using varied acrylate monomers for specialized elastomer needs.
-
Sundow Polymers (China) — notable for polyacrylate grades emphasizing aging, oil, and ozone resistance for both automotive and industrial segments.
-
Clwyd Compounders (UK) — serves high‑performance and safety‑critical Tier‑1 applications with tailored ACM compounds.
-
Mitsui Plastics (distribution presence in the U.S.) — markets engineered ACM lines for performance automotive and industrial uses.
Each firm’s strategic posture—whether focused on upstream monomer integration, downstream OEM qualification, geographical diversification, or proprietary grade development—carries different implications for customers and investors. In a concentrated market, moves by any of these players (new grade launches, capacity expansions, or commercial repricings) can ripple across pricing and supply availability.
Actionable guidance for 2026 planning
-
Procurement and sourcing: adopt a two‑tier sourcing strategy combining long‑term agreements with flexible spot allocations. Include clause templates for pass‑through inflation on monomer costs and pre‑negotiated escalation triggers linked to published monomer indices.
-
Product strategy: prioritize development of differentiated ACM grades that command premium pricing (e.g., enhanced heat resistance or hybrid low‑temperature performance) to insulate from commoditization and input cost pressure.
-
Manufacturing and capex: defer large greenfield investments unless anchored by multi‑year offtake commitments. Instead, favor modular upgrades and compounding line optimization that improve throughput and reduce per‑unit energy intensity.
-
Commercial tactics: sharpen OEM qualification roadmaps to reduce time‑to‑market for new grades; align warranty and performance testing protocols to capture aftermarket and Tier‑1 opportunities.
-
M&A and partnerships: pursue bolt‑on acquisitions to accelerate entry into specialty segments or to secure upstream monomer access. Form strategic supply alliances with chemical producers where price exposure is most acute.
-
Risk management: implement monitoring triggers for regional regulatory actions and power permissions, and model stress scenarios where a temporary 10–20% contraction in local spot availability could raise replacement costs significantly.
Report composition — what executives will find inside
-
Top‑down and bottom‑up sizing models with sensitivity tables and downloadable model files to test alternate price and demand scenarios.
-
Supplier scorecards and gap analyses that benchmark product portfolios, technical support capabilities, and qualification timelines against leading OEM requirements.
-
Segment playbooks for commercialization, including price positioning, channel optimization, and maintenance vs. replacement market strategies.
-
Cost‑build templates showing the pass‑through impact of monomer price movements and energy cost shifts on finished ACM compound margins.
-
A curated appendix of primary interviews, regulatory timelines, and raw‑material price series to support procurement negotiations and executive risk briefings.
What we intentionally withhold from this preview
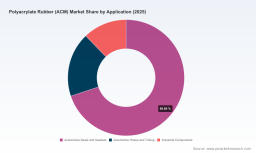
To preserve the integrity and commercial value of the full study (and to adhere to our “trailer” principle), this public release summarizes strategic findings and high‑level numeric baselines but does not reproduce our complete segmentation tables and granular regional/application revenue splits. The full report includes detailed breakdowns by region, type, and application—plus interactive dashboards and factory‑level supply maps—available on PW Consulting’s report page. Organizations that require immediate access to the complete segmentation and downloadable models should contact our sales team for licensing and custom briefings.
Closing perspective
As the ACM market navigates raw‑material inflationary pressure, episodic supply constraints, and a trend toward higher concentration among incumbent producers, 2026 presents both risk and opportunity. Companies that lock in disciplined procurement terms, invest selectively in differentiated grades, and align commercial strategies with the shifting competitive footprint will be best positioned to convert short‑term disruption into sustainable margin expansion. PW Consulting’s full Polyacrylate Rubber (ACM) Market report equips decision‑makers with the scenario tools, supplier intelligence, and tactical playbooks necessary to make those choices with confidence.
For the full dataset, segmentation tables, supplier scorecards, and our downloadable scenario model, please visit the PW Consulting report page for Polyacrylate Rubber (ACM) Market 2026 (full report access and licensing information are available there).
For detailed analysis of this topic, please visit the official page: Polyacrylate Rubber Acm Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com