

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Fertility ELISA Test Kit Market to Rise Through 2026–2032, Backed by a 6.12% CAGR

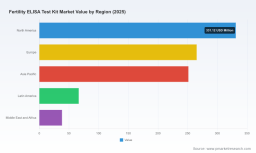
Fertility ELISA Test Kit Market 2026: Strategic Imperatives for Decision Makers
Executive summary
PW Consulting’s latest market research on the Fertility ELISA Test Kit Market (base year 2025, historical 2020–2025, forecast 2026–2032) delivers a pragmatic intelligence package for commercial leaders, product strategists, and investors preparing decisions in 2026. The market has demonstrated steady expansion through the pandemic recovery and consequent fertility-care rebound, and our forecast models project a clear growth trajectory across the 2026–2032 horizon at a compound annual growth rate (CAGR) of 6.12%. This briefing highlights the structural drivers, regulatory inflection points, competitive positioning, and operational playbooks that will determine who wins in the next phase — while intentionally withholding the detailed segment-level tables to encourage direct access to our full report for transaction-grade data.
Fertility Elisa Test Kit Market
Why this market matters in 2026
- Demographic and clinical demand: Continued global demand for assisted reproductive services, coupled with increased clinical adoption of hormone profiling, keeps fertility-focused immunoassays central to diagnostic workflows.
- Technology and differentiation: ELISA remains a validated, cost-effective methodology for a number of fertility analytes even as automated chemiluminescent and POCT platforms advance — creating differentiated opportunities for niche, high-specificity ELISA products.
- Policy and reimbursement complexity: Regulatory clearance strategies and reimbursement coding continue to shape product design, time-to-market and commercial access.
Market trajectory and concentration
Our top-line sizing shows a market that has recovered and expanded since 2020, with 2025 serving as the strategic baseline for fiscal planning. Through the forecast window to 2032, the market is expected to grow at a mid-single-digit CAGR (6.12%), reflecting a mix of steady clinical demand, incremental test adoption in emerging care settings, and selective product upgrades. Competitive dynamics are moderately concentrated: the three largest suppliers account for a material portion of the market, and the five largest firms control more than half of market activity — a structure that favors both scale players and highly specialized niche vendors depending on their go-to-market execution.
Fertility Elisa Test Kit Market
Dynamics shaping the market
Our Dynamics chapter synthesizes regulatory, quality, reimbursement and technology trends that executives must model into 2026 plans.
Fertility Elisa Test Kit Market
- Regulatory pathways: Fertility-related ELISA kits, particularly assays such as AMH that inform ovarian reserve and fertility planning, face differentiated regulatory expectations. In key markets, product positioning (e.g., clinical claims for menopausal status vs. general research use) materially changes the pathway — from notified CE marking to potential FDA clearance or de novo authorization for defined intended uses. Strategic regulatory planning early in development is a non-negotiable commercial lever.
- Quality and manufacturing: ISO 13485-compliant manufacturing and robust quality systems are table stakes. Buyers and distribution partners increasingly require visible GMP/ISO13485 certification as a condition of commercial supply agreements, and audit-readiness impacts both time-to-market and margin profiles.
- Reimbursement and coding: Fertility hormone assays are billed within broader endocrine and reproductive CPT/HCPCS structures rather than by a single dedicated fertility ELISA code in many jurisdictions. Commercial teams need to model payer landscapes at the country and provider level to avoid pricing surprises during launch.
- Technological competition: While ELISA maintains advantages for many fertility analytes (sensitivity, established validation pathways), automation, immunochemiluminescence, and point-of-care formats are eroding certain use cases. Successful ELISA manufacturers will lean into assay specificity, multiplexing where appropriate, and value-driven workflows for clinics and centralized labs.
Competitive landscape — what the leading players signal
Our strategic review of leading suppliers reveals differentiated plays around assay specificity, portfolio breadth, regulatory footprint, and distribution reach. Below we summarize the positioning cues you should weigh in 2026 planning.
- Ansh Labs (Webster, TX) — Specialization in reproductive immunoassays. Their AMH ELISA products, including research-use and CE-marked variants, illustrate a focused technical play: high-specificity monoclonal antibody reagents tailored for ovarian reserve and IVF outcome assessment. For rivals, Ansh highlights the advantage of clinically targeted assay claims and differentiated reagent chemistry that supports both clinical and research credibility.
- DRG International, Inc. (Springfield, NJ) — A broad ELISA manufacturer with established hormone assays (e.g., estradiol, 17-OH progesterone, DHEA-S). DRG’s bench-strength is in product breadth and legacy clinical laboratory relationships. Competitors must anticipate pricing pressure on commoditized hormone panels but can find white spaces in high-value niche analytes and workflow-enabled products.
- Monobind Inc. (Lake Forest, CA) — Brings a broad IVD menu to endocrine and reproductive testing under the AccuBind ELISA family. The company’s scale and distribution infrastructure exemplify the “menu play” — supply a wide range of routine assays to clinical labs. New entrants should evaluate whether to compete horizontally across a broad menu or to specialize deeply where clinical need and margin profiles permit.
- Sure Bio‑Tech (USA) Co., Ltd. (Burlingame/Escondido, CA; operations in Greater China) — Export-oriented supplier with GMP/ISO13485/CE compliance and an emphasis on basic fertility analytes. Their model underscores the viability of cross-border manufacturing and distribution to serve price-sensitive markets while meeting key quality standards. For multinational strategies, Sure Bio‑Tech is an example of how regulatory and manufacturing footprints are leveraged to scale exports.
Strategic implications for 2026
For executive teams preparing 2026 strategies, the following action imperatives emerge from our modeling and primary research:
- Prioritize regulatory route mapping as a component of product economics. Decide early whether target claims warrant a full clinical IVD pathway (with the attendant time and cost) or whether initial commercialization via research-use or limited-claim CE-marked IVDs is more pragmatic.
- Design portfolio plays: either breadth to serve central labs and clinic menus, or narrow specialization (e.g., high-specificity AMH assays) that commands premium positioning. Both models can succeed — the choice should align with distribution strength and capital availability.
- Invest in validated manufacturing and supply-chain redundancy. Buyers and hospital systems increasingly require ISO 13485 adherence and supply-chain transparency; these are gating items for large purchasing contracts.
- Model reimbursement at the country and provider level. With fertility assays often embedded within broader endocrine coding, pricing strategy must be built on granular reimbursement and billing practice research to ensure commercial sustainability.
- Consider M&A selectively. Given the market’s moderate concentration, bolt-on acquisitions can accelerate access to niche assays or regional registration dossiers; conversely, partnerships with established kit manufacturers offer lower-capex routes to market.
Operational playbook — what to execute in the next 12 months
We translate strategy into a six-step short-term playbook for product and commercial teams:
- Regulatory audit and claim optimization workshop to define the minimum viable IVD claim and related evidence generation plan.
- Technical de-risking through targeted validation studies focusing on clinical endpoints that buyers prioritize (e.g., ovarian reserve, IVF outcome correlations).
- Quality systems reinforcement — ISO 13485 gap assessment, supplier audits, and traceability upgrades to support tender participation.
- Channel segmentation — pilot partnerships with fertility clinics and reference labs to generate real-world evidence and early adoption testimonials.
- Pricing and reimbursement simulations across priority markets to stress-test launch economics under multiple billing scenarios.
- Commercial readiness: sales training, lab service bundles, and lab-onboarding materials to shorten adoption cycles.
What the full PW Consulting report contains (practical deliverables)
The full document provides the end-to-end intelligence executives need to operationalize the 2026 plays summarized above — including: validated market-size models (historical through 2032), scenario-based forecasts, primary-source regulatory mapping for key geographies, a reimbursement matrix, a proprietary competitive scorecard with capability and channel assessments, supplier and raw-material risk mapping, and a prioritized M&A target list based on strategic fit. Importantly, the detailed segment-level tables and country-by-country breakdowns are intentionally held for the full report, which contains the transaction-grade data that finance, corporate development, and commercial teams require.
Risk scenarios and contingency planning
Our scenario analysis highlights three plausible outcomes that should be stress-tested in 2026 plans:
- Conservative scenario: slower reimbursement absorption and more pronounced shift to automated platforms reduce ELISA volume growth — prioritize margin preservation and niche differentiation.
- Base case: steady demand growth aligned with our 6.12% CAGR forecast — execute the regulatory-to-commercial playbook to capture share.
- Upside scenario: fast-track regulatory approvals for differentiated assays combined with new clinic networks accelerate adoption — scale manufacturing and distribution to capture the opportunity.
Why PW Consulting — methodology and credibility
Our conclusions are built on blended-method research: primary interviews with lab directors, fertility clinic procurement officers and regulatory specialists; proprietary shipment and production data trending; review of public regulatory filings and quality certifications; and scenario-based financial modeling. The result is pragmatic, actionable guidance designed to be implemented within fiscal planning cycles for 2026.
Next steps — accessing the data you need
The briefing above is a strategic primer. For commercial due diligence, launch preparations, or M&A evaluation in 2026, teams should review the full report to access the underlying segment and country-level tables, competitive scorecards, and deal pipeline worksheets that are intentionally omitted here. Contact PW Consulting to obtain the comprehensive dataset and tailored advisory support that turns the high-level plays summarized in this release into executable plans.
For detailed analysis of this topic, please visit the official page: Fertility Elisa Test Kit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com