

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Climbing Equipment Market to Scale New Heights with a 6.8% CAGR Through 2032

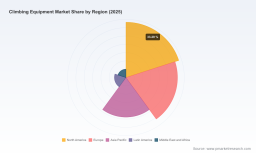
Climbing Equipment Market — 2026 Strategic Outlook and Action Guide
PW Consulting’s latest market research positions the global climbing equipment industry at a decisive juncture. Using a base year of 2025 and a historical window spanning 2020–2025, our models show the market valued at USD 1,850.5 Million in 2025 and projected to grow at a compound annual growth rate (CAGR) of 6.8% through the 2026–2032 forecast period, reaching an estimated USD 2,932.83 Million by 2032. For C-suite leaders preparing budgets, product roadmaps, or M&A pipelines for 2026, this report translates those headline figures into executable strategic choices — while preserving the proprietary granular segment intelligence behind our conclusions for readers who access the full dossier.
Climbing Equipment Market
Why 2026 is a strategic inflection point
The climbing equipment market’s steady expansion masks a complex set of near-term disruptors and structural opportunities. Participation growth, the maturation of indoor climbing facilities, and premiumization of technical apparel and footwear continue to fuel demand. Simultaneously, 2024–2026 developments have recalibrated risk and cost equations across the value chain:
Climbing Equipment Market
- Regulatory tightening: Revisions to multiple UIAA safety standards in 2025 (including helmets and energy-absorbing devices) raise compliance requirements for product testing, documentation, and labeling — impacting time-to-market and engineering budgets.
- Recall risk and brand liability: High-profile recalls in 2025 (notably harness and rope batches) have amplified reputational and warranty exposures, pressuring quality assurance and traceability systems.
- Raw material and trade shocks: Metal tariffs and tightened supply on key inputs (notably steel and aluminum duties implemented or expanded in 2025 in certain markets) and material-price inflation observed between 2022–2024 have pushed component costs higher, reinforcing incentives to redesign for alloy efficiency or alternative sourcing.
- Product innovation cadence: A wave of new product releases across the industry in late 2025 and early 2026 highlights a competitive pivot toward lighter, more sustainable materials, and integrated digital training tools for indoor gyms.
Those dynamics mean 2026 will reward organizations that can balance compliance, cost control, and product differentiation while preserving speed to market.
Climbing Equipment Market
What PW Consulting’s report delivers — practical, operational, and financial
We designed the study as a hands-on playbook for decision-makers. Highlights of the deliverables include:
- Top-down and bottom-up market sizing (USD Million) using verified shipment, retail and channel demand inputs across 2020–2025, with forward-looking forecasts through 2032 and sensitivity ranges around the 6.8% CAGR baseline.
- Segment-level frameworks and decision matrices that link product development, pricing levers, and channel tactics to commercial outcomes — enabling rapid scenario testing without re-running the core model.
- Supply‑chain heatmaps identifying concentrations of risk (single-source components, tariff exposure, and long-lead subassemblies), plus recommended mitigations and cost/benefit timelines for near-term reshoring, dual sourcing, or alloy substitutions.
- Regulatory and quality-compliance playbook: step-by-step templates for implementing the latest UIAA standard requirements, add-on testing protocols, and recall containment procedures to reduce liability and accelerate recovery.
- Commercial go-to-market playbooks for distinct channel archetypes — specialty retail, direct-to-consumer, gym partnerships and rental ecosystems — with margin ladders and promotional cadences calibrated to realistic conversion benchmarks.
- M&A screening tool and valuations framework tuned to market concentration realities and synergies (product, channel, manufacturing) that buyers and PE funds can use to prioritize targets and model accretion scenarios.
Competitive landscape — who matters and what they signal
The market remains fragmented, with leading players capturing a meaningful but not overwhelming share of industry revenue; the top-three and top-five concentration ratios indicate room for both consolidation and niche leadership. Our report provides company-level diagnostics; summarized here are the strategic profiles that will influence competitive dynamics in 2026.
- Black Diamond Equipment — Strength in comprehensive hardware portfolios and channel relationships. The 2025 harness recall underscores the reputational downside of legacy manufacturing exposures and highlights the need for traceability and material lifecycle audits.
- Petzl — A reference for safety-driven innovation and technical differentiation, especially in belay and headlamp systems. Its R&D posture makes it an archetype for companies seeking to monetize enhanced safety features and premiumization.
- Mammut Sports Group — Known for performance ropes and integrated apparel systems; Mammut exemplifies multi-category premiumization and vertical brand coherence, useful as a blueprint for cross-sell strategies.
- Arc’teryx — Premium, performance-focused apparel and lightweight systems. Its pricing power and brand cachet indicate consumer elasticity at higher tiers and the marketing investments required to sustain that position.
- Edelrid, Beal, Sterling Rope — Rope and hardware specialists where safety certification and manufacturing process control differentiate value. Recent recalls and UIAA revisions elevate the commercial reward for immaculate QA systems.
- CAMP, DMM, Grivel — Heritage alpine manufacturers that are leaders in metal hardware innovation; their supply footprints and material expertise position them as targets for collaboration on lighter-alloy components.
- La Sportiva, Scarpa, Mad Rock — Footwear leaders illustrating how product specialization (shoes, approach footwear) can deliver margin upside through brand loyalists, while requiring consistent design investment to chase performance gains.
- Trango, Metolius, Singing Rock — Niche and regional players demonstrating that focused channel partnerships (gyms, training schools, rescue services) can be defensible revenue streams even in a consolidating market.
Taken together, the competitor set demonstrates three strategic archetypes that PW Consulting uses in scenario analysis: (1) Full-line integrators aiming for cross-category capture; (2) Component specialists where engineering and certification are the moat; and (3) Channel specialists whose advantage is distribution intimacy.
Operational and commercial implications for 2026 decision-makers
Our modeling shows that companies that prioritize the following actions will be materially better positioned to capture upside from the projected market expansion:
- Accelerate compliance-led product redesigns: Implement UIAA-driven test protocols into product development sprints to reduce rework and limit time-to-market penalties.
- Invest in supply-chain transparency: Deploy traceability platforms for high-risk components (metal hardware, dynamic ropes) and pursue dual-sourcing for critical alloys to blunt tariff volatility.
- Revise pricing & promotion playbooks: Build tiered pricing with clear feature differentiation for rental-friendly products vs. premium ownership goods; stress-test margins in the face of commodity-driven cost increases.
- Operationalize recall readiness: Establish cross-functional recall playbooks (logistics, legal, PR) and ensure serial-traceability of affected product families to reduce containment time and cost.
- Partner with indoor-gym ecosystems: Design rental-optimized, durable SKUs and service agreements that monetize recurring usage and strengthen brand visibility among next-generation climbers.
- Prioritize sustainability as differentiation: Accelerate adoption of recycled fibers and low-impact coatings, which drive both regulatory goodwill and new consumer willingness to pay among premium segments.
Scenario outlook and a 90-day executive checklist
Our forecast baseline assumes a continuation of current participation and product-refresh cycles producing a 6.8% CAGR from 2026 through 2032. PW Consulting models alternate scenarios — faster growth driven by a boom in indoor facilities and accelerated product adoption; and downside risk driven by new regulatory constraints, fresh large-scale recalls, or sustained commodity inflation. For leaders who need to act now, a compact 90-day checklist derived from the report’s playbooks can materially reduce downside while positioning to capture upside:
- Audit product compliance status against the latest UIAA revisions and commission any missing third-party tests.
- Map tariff and supplier exposure across the BOM and secure alternative quotations for at least two critical components.
- Run pricing-sensitivity simulations for core SKUs, including rental and subscription models for gym partnerships.
- Validate recall response capabilities with a live tabletop exercise involving supply chain, legal, and communications teams.
- Initiate targeted R&D sprints to launch one “sustainability-forward” SKU and one “rental-optimized” SKU within 12 months.
How to apply this research to 2026 planning
PW Consulting’s Climbing Equipment Market Report is built to be operational: beyond forecasts and historic sizing, it delivers the playbooks, models, and prioritized checklists that executive teams can implement in quarter-to-quarter roadmaps. It translates the macro picture — USD 1,850.5 Million market in 2025 and a path to USD 2,932.83 Million by 2032 at a 6.8% CAGR — into decisions about where to invest R&D, how to harden supply chains, and which M&A targets or partnerships offer the most immediate leverage.
For readers who require the full set of proprietary segment models, regional and channel forecasts, and company-level financial implications (the detailed intelligence we intentionally withhold here to preserve our data assets), the report package includes downloadable models, scenario dashboards, supplier heatmaps, and an executable M&A screening tool tailored to the climbing equipment value chain.
PW Consulting stands ready to brief executive teams on the analysis and to run bespoke workshops that convert insights into 2026 operating plans. The market is expanding, but the winners will be those who treat compliance, supply resilience, and channel innovation not as separate functions, but as integrated pillars of strategy.
For detailed analysis of this topic, please visit the official page: Climbing Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com