

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Rative Dentistry Market to Reach USD 32,421.78 Million by 2032

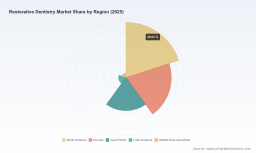
Rative Dentistry Market: Strategic Insights for 2026 Decision-Makers
As PW Consulting's Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused preview of our Rative Dentistry Market report — an evidence-based playbook designed to steer corporate strategy through 2026 and beyond. This briefing highlights the macro trajectory, strategic inflection points, competitive dynamics, and the operational levers that matter most to executives planning product investment, M&A, and commercial execution in the restorative dentistry ecosystem.
Rative Dentistry Market
Market trajectory — what the numbers tell us
The restorative dentistry market has demonstrated steady expansion through the first half of the decade, rising from approximately USD 14,520 million in 2020 to about USD 20,850 million in 2025. Our base-year calibration (2025) sets the stage for a forecast period (2026–2032) in which the market is projected to grow at a compound annual growth rate (CAGR) of 6.51%, reaching roughly USD 32,422 million by 2032.
Rative Dentistry Market
Two observations are important for 2026 planning. First, the market’s mid-single-digit CAGR masks sharper pockets of disruption: digital restorative workflows, next‑generation bioactive materials, and implant/prosthetic innovations are creating higher-growth corridors inside an otherwise steady market. Second, market structure remains moderately concentrated — the top three players account for roughly 34% of value, and the top five for about 49% — a configuration that favors scale-driven innovation while leaving space for focused challengers to capture specialty niches.
Rative Dentistry Market
Key demand and supply dynamics shaping near-term strategy
- Clinical and demographic tailwinds: Aging populations, higher utilization of implant and prosthetic solutions, and broader screening incentives are lifting long-term demand for restorative interventions and allied consumables.
- Technology adoption inflection: CAD/CAM systems, same‑day restorative platforms, and integrated digital workflows are moving from early adoption to mainstream procurement in many dental clinics and labs — an environment that advantages vendors with hardware-software-service bundles.
- Material science advances: The industry is rapidly commercializing bioactive and ion‑releasing composites that promise improved remineralization and lower secondary-caries rates. These advances are catalytic for premiumization strategies and differential pricing.
- Regulatory and reimbursement evolution: Quality systems such as ISO 13485 remain mandatory gatekeepers for market access in major jurisdictions, while regulatory guidance and environmental mandates (e.g., amalgam separator standards) are reshaping practice infrastructure investments. Notably, the recent addition of an oral health incentive to CMS’s Merit-based Incentive Payment System (effective January 2026) establishes a new lever that can increase restorative treatment touchpoints via provider payment alignment.
- Cost volatility in raw inputs: Synthetic monomer and filler price swings are elevating manufacturing cost risk for composites and related consumables; this requires supply‑chain hedging and sourcing strategies to protect margins.
Competitive landscape — who matters and why
The restorative dentistry competitive field is populated by multi‑national platform players, specialized material innovators, and regional champions. Below are strategic characterizations of core competitors we profile extensively in the full report.
- Dentsply Sirona: A leader in integrated restorative solutions — combining consumables with CAD/CAM hardware (including same‑day restoration systems) and digital workflows. Recent financials demonstrate continued revenue growth and a sustained emphasis on restorative innovations and consumables in its go‑to‑market mix.
- 3M (Dental Division): Positioned as the advanced materials specialist with durable, aesthetic direct restorative products and system‑level bonding solutions. Strong route-to-market and brand recognition in clinical practice are core strengths.
- Straumann Group: Known for tooth-replacement systems and digital prosthetic workflows; Straumann’s recent reporting signals continued investment in digital integration and regenerative applications.
- Ivoclar Vivadent & GC Corporation: These companies compete strongly in high‑aesthetic restorative materials and formulations, with Ivoclar emphasizing premium ceramics and GC advancing bioactive, fluoride‑releasing chemistries.
- Envista (Kerr, Nobel Biocare) & Zimmer Biomet: These players bring combined strengths in implant systems, prosthetics, and restorative consumables, addressing both surgical and restorative value chains.
- Coltene, Septodont, VOCO, Shofu, Ultradent, Mitsui Chemicals: Regional and product-focused competitors that drive innovation in niche consumables, polishing systems, and specialty materials; they are important acquisition targets or strategic partners for broader platform players.
Recent product and industry developments reinforce these positions: major product launches of bioactive composites, corporate financial results highlighting restorative portfolios, and sector reviews underscoring material advances. These signals suggest a competitive race not just on materials, but on digital integration, lifecycle service offerings, and bundled economics for clinics and labs.
What the report delivers — operationally relevant content
Our full Rative Dentistry Market report goes beyond high-level forecasts to deliver actionable intelligence for commercial and R&D leaders. Core deliverables include:
- Granular market sizing and validated demand models for 2020–2032 (base year 2025), with scenario-based forecasts and sensitivity testing around pricing, raw‑material inflation, and adoption curves.
- Competitive positioning maps that evaluate product portfolios, channel footprints, and digital capabilities for over a dozen manufacturers — including disclosed strategic moves and M&A rationale.
- Regulatory and reimbursement playbooks: ISO 13485 compliance checkpoints, environmental/device disposal impacts, and a practical assessment of how the CMS oral health incentive could reroute clinical workflows and payer dynamics.
- Supply‑chain stress tests: supplier concentration risk matrices, procurement levers for monomers and fillers, and near‑term mitigation strategies for input cost volatility.
- Commercial execution tools: targeting frameworks to prioritize accounts (clinics, hospitals, labs), price-pack architecture recommendations, and channel incentives to accelerate digital and premium material uptake.
- M&A and partnership thesis: identification of capability gaps best closed by acquisition versus alliance, and a prioritized list of candidate profiles with rationale and valuation yardsticks.
Note: In line with our “teaser-first” approach, this public briefing is intentionally selective. Detailed subsegment share tables, proprietary pricing curves, and granular region/application breakdowns are reserved for the paid report and client workshops.
Strategic priorities for 2026 — a practical roadmap
For executives preparing 2026 plans, focus on three parallel motions that align near-term wins with sustainable competitive advantage.
- Defend and extend core consumables: Optimize margin through supply‑chain hedging, targeted SKU rationalization, and selective price increases accompanied by demonstrable clinical value (e.g., bioactivity or durability claims supported by in-market evidence).
- Invest in digital and service differentiation: Bundle software-enabled workflows, training, and chairside service agreements to lock in clinic economics. Prioritize interoperability with leading CAD/CAM platforms to speed adoption.
- Pursue focused inorganic growth: Acquire or partner with material innovators (bioactive composites, advanced ceramics) or regionally dominant distributors to gain local access quickly and cost-effectively.
90‑day to 36‑month tactical milestones
- 0–90 days: Run a portfolio heat‑map to reallocate R&D spend toward bioactive materials and digital integration; initiate supplier hedging for key monomers/fillers; update ISO 13485 audit schedules.
- 3–12 months: Pilot bundled digital-restorative programs with reference clinics; pursue at least one strategic alliance for digital workflow connectivity; refine pricing tiers to capture premiumization without ceding volume.
- 12–36 months: Execute targeted acquisitions to secure clinical materials advantage or channel access; scale service contracts and digital subscriptions to create recurring revenue streams; pursue regulatory filings to broaden market access.
Why PW Consulting’s report is strategically valuable in 2026
Decisions made in 2026 will determine market share trajectories for the next half-decade. Our report synthesizes a unique combination of validated market sizing (2020–2032), scenario stress-testing, competitive benchmarks, and practical go‑to‑market playbooks — all calibrated to the realities of regulatory change, material science advances, and payment incentives. For executive teams, this is not academic insight; it’s a prioritized list of actions, investments, and acquisition targets aligned to measurable commercial outcomes.
Next steps
To access the full set of proprietary models, company revenue share analysis, and the granular segment-level forecasts necessary for board-level decisioning, visit our Rative Dentistry Market report page or contact PW Consulting’s healthcare strategy desk to schedule a strategy review. Our bespoke client workshops translate these insights into executable roadmaps tailored to your organization’s risk profile and growth ambitions.
PW Consulting will continue monitoring regulatory shifts (including environmental standards and ISO requirements), reimbursement adjustments, and emergent material science breakthroughs — and will issue targeted updates as those events meaningfully alter forecasts or competitive positioning.
For detailed analysis of this topic, please visit the official page: Rative Dentistry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com