

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Macrocell Baseband Unit Market to Reach USD 13,900 Million by 2032, Growing at a 5.23% CAGR

Macrocell Baseband Unit Market 2026 Outlook: Strategic Imperatives for Capex, Architecture, and Vendor Selection
PW Consulting’s latest Macrocell Baseband Unit Market report (base year 2025) delivers a concise, decision-ready synthesis for executives planning network investments in 2026. Anchored in a detailed historical review (2020–2025) and a forward-looking forecast (2026–2032), the study quantifies market momentum—with the global market standing at roughly USD 9,720 Million in 2025 and expected to grow at a compound annual growth rate (CAGR) of 5.23% through our 2026–2032 forecast horizon, reaching approximately USD 13,900 Million by 2032.
Macrocell Baseband Unit Market
Why this report matters for 2026 decision cycles
-
Budget alignment: Operators and infrastructure investors looking to finalize 2026 capex plans need a clear view of aggregate market size and growth trajectory to set realistic procurement envelopes and ROI expectations. Our modeling provides that topline context while mapping the timing of technology inflection points.
Macrocell Baseband Unit Market -
Architecture trade-offs: With 3GPP Release 18 formalizing enhanced baseband processing for 5G-Advanced, the window to adopt cloud-native and virtualized baseband architectures is now strategic rather than optional. We translate standards roadmaps into practical adoption timelines and cost/benefit heuristics for macrocell rollouts.
Macrocell Baseband Unit Market -
Concentration and competitive dynamics: The macrocell baseband market is highly concentrated—our concentration analysis points to a market where the three largest suppliers control a substantial share, and the top five are dominant—information critical for negotiating supply terms and assessing single-vendor versus multi-vendor risk.
Executive summary — what the numbers are telling us
The industry returned to growth after a period of volatility during 2020–2025, reflecting waves of 5G deployments, spectrum reallocations, and macroeconomic headwinds. Our baseline scenario shows steady demand for macrocell baseband units driven by densification of mid-band deployments, migration to 5G-Advanced features, and operator refresh cycles. The projected CAGR of 5.23% reflects a balance between ongoing legacy phase-outs and the gradual but persistent shift toward cloud-native and virtualized RAN topologies.
Report contents — operationally useful, not just descriptive
-
Market sizing and trend analysis: Annual revenue series (2020–2032) with scenario-based projections and sensitivity testing against commodity pricing, spectrum availability, and macro demand shocks.
-
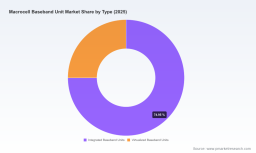
Segmentation framework: A pragmatic taxonomy by technology type, deployment profile, and macrocell application — designed to support procurement decision trees and vendor shortlists. (Note: detailed segment tables and regional/app share breakdowns are reserved for the full report.)
-
Vendor benchmarking: Qualitative and quantitative assessment criteria that drive RFPs — including interoperability, cloud-native maturity, Open RAN readiness, upgrade pathways for 5G-A features, and support footprint.
-
Cost modelling templates: Capex and opex templates that allow network planners to compare integrated versus virtualized baseband economics across three migration timelines.
-
Regulatory and supply-risk matrix: Scenario playbooks that map export controls, spectrum policy shifts, and standards releases to operational responses, supplier diversification strategies, and compliance checkpoints.
-
Implementation playbooks: Step-by-step guidance for macrocell refresh programs — procurement cadence, trial-to-scale milestones, integration checkpoints (fronthaul, RRU, and OSS/BSS alignment), and KPIs for proof-of-value.
Competitive landscape — who matters and why
The macrocell baseband arena is characterized by a small set of incumbent and scale-capable vendors that combine global service footprints with deep R&D pipelines. Our report provides head-to-head assessments of these vendors on technology, deployment references, and strategic posture. Highlights include:
-
Nokia (Espoo, Finland) — Known for AirScale baseband units that support massive MIMO and cloud-native RAN options; strong emphasis on hybrid cloud deployments and integration services.
-
Ericsson (Stockholm, Sweden) — Offers high-capacity baseband series geared to standalone 5G and spectrum sharing; active in Open RAN trials and macrocell coverage projects.
-
Huawei (Shenzhen, China) — Provides all-IP architecture basebands and AAU-integrated solutions with broad 5G macrocell references, particularly in Asia; faces export-policy headwinds in certain markets.
-
ZTE (Shenzhen, China) — Focused on virtualized RAN solutions that are evolving toward 5G-Advanced functionality; competing on cost and software-driven features.
-
Samsung Networks (Suwon, South Korea) — Offers vCore and distributed baseband solutions with an emphasis on Open RAN compatibility and cloud-native integration.
Recent vendor milestones that materially affect procurement timing include Nokia’s launch of a cloud baseband tailored for 5G-Advanced deployments, Ericsson’s Open RAN macrocell trial deployments with major North American operators, and Huawei’s hardware refreshes supporting massive MIMO in large-scale domestic macro sites. These developments shift the competitive calculus around technology lock-in, migration costs, and service-level commitments.
Market dynamics and risk factors
-
Standards-driven timing: 3GPP Release 18 codifies enhancements that elevate baseband processing requirements. Network planners must align procurement windows with software maturity to avoid early-adopter rework or delayed feature support.
-
Spectrum and deployment economics: Recent mid-band allocations in key markets are catalyzing macrocell upgrades, but spectrum availability and national licensing timelines create asymmetric demand peaks across geographies.
-
Supply-chain and export controls: Entity-list restrictions and trade policy create bifurcated vendor accessibility in some markets. Our risk matrix quantifies exposure by procurement geography and vendor dependence, and suggests mitigation levers such as split sourcing and staged rollouts.
-
Cost-to-deploy realism: Fronthaul and RRU integration remain non-trivial cost contributors. Operators that underestimate per-site integration and fronthaul provisioning risk pushing TCO beyond forecasted thresholds.
-
Legacy product phase-out: Major operators have accelerated phasing out 4G-only baseband units in macrocell refreshes; transition planning must include interoperability and traffic migration strategies to avoid coverage gaps.
Actionable recommendations for 2026 planning
-
Adopt a staged virtualization roadmap: For operators evaluating virtualized baseband architectures, adopt a hybrid-staged approach—start with new greenfield and targeted urban macro sites for virtualization pilots before nationwide scale-up. Use vendor-agnostic orchestration layers to reduce lock-in.
-
Negotiate flexibility in SLAs and upgrade paths: Given the rapid cadence of 5G-Advanced features, include contractual clauses for software feature roadmaps, interoperability testing, and staged performance acceptance criteria tied to macrocell service KPIs.
-
Stress-test supplier concentration: With a highly concentrated supplier market, perform scenario analysis on single-source disruptions and identify second-source suppliers with proven interoperability to reduce deployment risk.
-
Synchronize spectrum and procurement timelines: Align RAN procurement cycles with national spectrum auctions and expected allocation windows to avoid mismatches between equipment capability and licensed spectrum bands.
-
Quantify true per-site integration costs: Expand capex models to include fronthaul provisioning and RRU integration, and factor in uplift for massive MIMO retrofits and fiber provisioning delays.
What executives will find in the full PW Consulting report
The full report contains detailed tables, vendor scorecards, negotiated price benchmarks, procurement templates, and a downloadable capex/opex model calibrated for regional variations. It also includes a confidential appendix with modeled scenarios showing the impact of accelerated 5G-Advanced adoption and supply-chain shocks on mid-term spend profiles. To preserve the strategic value of our primary datasets for subscribers, we present the most actionable, proprietary segmentation tables and regional breakdowns only in the paid release.
Next steps and how to use this intelligence
-
For C-suite and procurement leads: Use our vendor benchmarking and concentration analysis to finalize shortlists and to structure multi-year contracts that balance cost with upgrade flexibility.
-
For network planners and architects: Leverage the implementation playbooks and cost-model templates to construct pilot-to-scale migration roadmaps that align with 3GPP Release 18 feature rollouts.
-
For regulators and policy advisors: The report’s spectrum-timing scenarios provide objective inputs for auction and allocation planning to maximize macrocell utility.
PW Consulting’s Macrocell Baseband Unit Market report is designed as a practical tool for 2026 decision cycles—providing market context, vendor insights, and actionable templates without overwhelming teams with raw segment minutiae in this briefing. For the full dataset, granular segment shares, and downloadable financial templates that underpin our recommendations, please consult the complete report on our website or contact your PW Consulting analyst for a briefing.
For detailed analysis of this topic, please visit the official page: Macrocell Baseband Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com