

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sintered Steel Market Forecast to Reach USD 41,084.51 Million by 2032, Expanding at a 5.39% CAGR (2026–2032)

PW Consulting Releases Strategic Preview: Sintered Steel Market — The 2026 Decision Playbook
As PW Consulting’s lead industry analyst, I am pleased to present a strategic preview of our forthcoming in-depth Sintered Steel Market report. This release is designed as a “trailer”: it surfaces the priority implications, decision levers, and scenario dynamics senior leaders must incorporate into 2026 planning cycles — while directing readers to the full report for the granular, actionable tables and models that underpin each recommendation.
Sintered Steel Market
Macro snapshot: trajectory and what it means for 2026
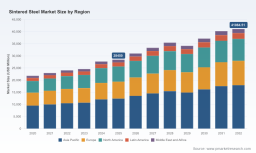
The sintered steel market has moved from recovery into a steady expansion phase. Using 2025 as the base year, our modeling shows the market reached USD 28,450 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.39% across the 2026–2032 forecast window, reaching an approximate market value of USD 41,085 Million by 2032. The near-term step-change between 2025 and 2026 represents an inflection driven by electrification investments and a rebound in industrial capex, but the multi-year path contains uneven segments where demand reallocation and cost pressures introduce tactical risk.
Sintered Steel Market
Two macro facts shape 2026 decision-making. First, concentration metrics indicate moderate market fragmentation — the top three players hold roughly one-third of the market while the top five account for just under half — creating simultaneous pressures for scale and opportunity for mid-market consolidation plays. Second, technological shifts (notably soft magnetic composites and additive binder-jet powders) are re-writing the product roadmap for multiple OEM-facing supply chains, changing the economics of parts production and aftermarket positioning.
Sintered Steel Market
Executive strategic takeaways for 2026 planners
-
Prioritize supply-chain resilience and input-cost hedging: raw material volatility has reappeared as a structural theme. Upstream iron-powder pricing spikes and localized tariffs alter landed costs materially; buyers and producers should adopt flexible sourcing strategies, indexed supply contracts, and strategic inventory buffers to stabilize margins through 2026.
-
Localize selectively in tariff-sensitive corridors: trade measures and tariffs persist as a differentiator. For companies supplying to markets exposed to import duties, targeted regional manufacturing or toll-sinter partnerships can neutralize tariff leakage while preserving margin capture.
-
Architect product portfolios around electrification vectors: EV drivetrains, soft magnetic composites for high-efficiency motors, and high-strength powders for lighter, fatigue-resistant components will command premium pricing and strategic investment. R&D and manufacturing roadmaps should allocate clear capacity and capex for these prioritized product types in 2026.
-
Invest in additive manufacturing readiness — but discriminate: binder-jetting and other AM powder technologies are maturing into production-capable routes for complex geometries. However, they require distinct powder specifications, process controls, and post-processing flows. Run pilot production lines to quantify TCO tradeoffs before broad roll-outs.
-
Use regulatory impact as a market-entry screening tool: updated chemical and impurity thresholds in major jurisdictions are raising compliance costs for nickel-containing powders and other alloys. Incorporate regulatory cost models into product costing and GTM planning to avoid margin surprises.
-
Target M&A to bridge either upstream materials or downstream systems: with mid-market fragmentation and growing technology complexity, acquisitions that combine powder capability, sintering know-how, and proximity to key OEMs will accelerate growth capture in 2026.
What the full report delivers — practical, decision-grade assets
Our full Sintered Steel Market report is constructed for senior commercial, operations, and corporate development teams who require executable intelligence. Highlights include:
-
Scenario-driven demand models (base, accelerated electrification, and constrained-cost scenarios) with downloadable Excel workbooks that allow you to re-run forecasts with your inputs.
-
Price and cost-vulnerability maps that quantify the P&L impact of raw-material and tariff shocks at the plant and SKU level, enabling rapid hedging and sourcing decisions.
-
Supplier and facility scorecards across technology capability, geographic footprint, quality credentials, and delivery reliability — a due-diligence ready matrix for procurement and M&A teams.
-
Technology readiness timelines for additive routes, soft magnetic composite adoption, and next‑generation high-strength powders, tied to investment sizing and expected ROI windows.
-
Regulatory impact assessment and a compliance playbook addressing the practical steps to meet tightened impurity limits and registration requirements in the EU and other major markets.
-
Commercial and pricing playbooks: segment-specific go-to-market strategies, channel models for OEM vs. aftermarket, and negotiation levers to sustain margins under price competition.
Note: This preview intentionally omits the full, granular regional and application splits and product-level financials included in the paid report; those tables and downloadable models are accessible on our report page and are provided to subscribers and licensees.
Competitive landscape: profiles and strategic implications
The market features a mix of long-established powder suppliers, sintered-component specialists, and emerging additive entrants. Our analysis highlights several archetypes and recent strategic moves:
-
Integrated system leaders: companies with end-to-end powder metallurgy capabilities — from alloy and powder production to sintering and finished components — retain advantaged margin capture and closer collaboration with OEMs. Recent capacity extensions in North America by a global powder metallurgy firm illustrate this playbook: they are positioning to capture EV drivetrain volumes.
-
Specialized powder manufacturers: leading iron and alloy powder producers continue to dominate specification leadership. New high-strength grades launched in mid-2024 show sustained R&D prioritization towards fatigue-resistant powders for critical automotive and industrial parts.
-
Materials innovators: suppliers launching soft magnetic composite series are accelerating motor-efficiency gains and opening new design possibilities for electric machines. Such product introductions are a wake-up call for component makers that must either partner or invest in parallel technology to stay relevant.
-
Additive entrants and binder-jet specialists: smaller, agile firms developing AM-optimized powders are creating a new supplier tier — one that is attractive for small-batch, high-complexity components and for OEMs seeking rapid design iteration.
Across these archetypes, the most consequential 2026 moves will be (a) capacity rebalancing by incumbent manufacturers to match EV-related geometries, (b) strategic partnerships between powder producers and AM equipment vendors, and (c) selective M&A that pairs material know-how with application engineering capabilities.
Regulatory and input-cost dynamics that will shape strategy in 2026
Four operational realities will require concrete actions in 2026 planning:
-
Raw material volatility: iron powder price upticks in late 2024 have already translated into stronger input-cost pressure. Procurement teams should model indexed contracts and strategic stocking for critical alloys.
-
Regulatory tightening: updated impurity limits and registration obligations for certain alloy powders increase the cost of bringing some product grades to market in regulated jurisdictions. Technical teams must evaluate reformulation, testing regimes, and documentation pipelines now, not later.
-
Trade measures: persistent tariffs in key countries are reshaping near-shore manufacturing economics. Production footprint decisions should be stress-tested against tariff scenarios to determine the optimal blend of centralized vs. localized capacity.
-
Labor-cost inflation in advanced manufacturing regions: rising metalworking wages impact cost competitiveness for certain fabrication routes; this accelerates automation and process-intensification investments.
Implications for investment, M&A and operations
Given the market’s moderate level of concentration and accelerating technology shifts, 2026 is a pivotal year for capital allocation. We recommend three concurrent tracks for value capture:
-
Defensive investment: secure raw-material continuity and compliance by investing in upstream partnerships or long-term supply agreements.
-
Offensive scale and capability plays: pursue bolt-on acquisitions that add high-performance powder grades, AM powder portfolios, or motor-grade magnetic composite capabilities to accelerate entry into high-growth subsegments.
-
Operational modernization: redirect capital toward selective automation, in-line quality controls, and pilot binder-jet cells to reduce per-part costs and compress time-to-market.
How to use this preview — and the practical next step
This preview is intended to prioritize the strategic questions you should be answering during 2026 planning: where to position product portfolios, how to hedge commodity and regulatory risk, which capability gaps to close through investment or M&A, and how to shape commercial models for OEMs transitioning to electric powertrains.
For procurement teams, our downloadable cost-sensitivity models will be immediately actionable. For corporate development teams, the supplier scorecards and M&A playbook distill target criteria and valuation sweet spots. And for R&D and operations leaders, the technology readiness timelines and benchmarked productivity metrics provide a pragmatic basis for capex allocation in 2026.
Requesting full access
The full PW Consulting Sintered Steel Market report contains the granular regional and application breakdowns, plant-level benchmarking, and downloadable financial models that underpin the strategies summarized here. To receive the complete dataset, scenario models, and a tailored briefing for your executive team, please visit our report page or contact your PW Consulting account lead.
PW Consulting remains committed to translating market intelligence into executable strategy. This preview identifies the levers that will determine competitive winners in 2026; the full report supplies the playbooks to act on them.
For detailed analysis of this topic, please visit the official page: Sintered Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com