

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Recombinant Collagen Market to Surge at a 28.5% CAGR, Reaching USD 23.8 Billion by 2032

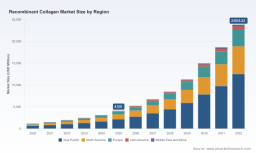
Recombinant Collagen Market: Strategic Imperatives for 2026 — A PW Consulting Preview
The recombinant collagen market has entered an accelerated growth phase. After expanding from USD 1,180.5 Million in 2020 to USD 4,120.0 Million in 2025, PW Consulting projects the market to surpass USD 5,200 Million in 2026 and to expand toward an addressable opportunity measured in the tens of billions by 2032 — driven by an expected compound annual growth rate of 28.5% over the 2026–2032 forecast window. For corporate leaders making 2026 budget, R&D and M&A decisions, this is a pivotal inflection year: technical maturation, regulatory momentum and early commercial wins are converging to make strategic moves materially consequential.
Recombinant Collagen Market
Why 2026 Is a Strategic Inflection Point
-
Clinical-grade supply is becoming industrially available. Several platform providers have announced or begun supplying formats intended for clinical use, shifting the vendor landscape from lab-demo to regulated product development.
Recombinant Collagen Market -
Regulatory pathways are crystallizing for first-in-class device and implant applications, and breakthrough designations and marketing authorizations in key jurisdictions are accelerating clinical translation and commercial acceptance.
Recombinant Collagen Market -
Manufacturing economics are improving. Advances in expression systems, higher fermentation yields and scale-up initiatives are lowering unit costs and enabling ton-scale aspirations — a prerequisite for wound care, implantable devices and high-volume cosmetic products.
-
Market structure favors both scale and specialization. The market shows medium-high concentration among a few established platform players while leaving white-space for niche specialists and regional champions — a dynamic that supports both M&A and focused organic strategies.
What PW Consulting’s Recombinant Collagen Report Delivers
This release is designed as an operational playbook for executives, investors and R&D leaders. While this preview outlines strategic themes and proprietary high-level market sizing, the full report contains granular segmentation, modelled scenarios, pricing curves and negotiation templates that are essential for executable plans. Key practical deliverables include:
-
Robust market sizing and multi-scenario forecasts (2020–2032) with sensitivity analysis across adoption, regulatory and price pathways.
-
A competitive intelligence dossier on platform and manufacturing players, including capability heatmaps, go-to-market vectors and partner-fit matrices.
-
Regulatory and clinical roadmaps by application class — highlighting milestone sequencing, recommended evidence packages and accelerated pathways to commercialization.
-
Manufacturing scale-up playbook: fermentation benchmarks, cost-of-goods sensitivity, CAPEX planning templates and contract manufacturing decision frameworks.
-
An M&A and partnership playbook: target archetypes, valuation heuristics, integration checklists and dilution-risk matrices for equity investors.
-
Commercial launch playbooks with pricing and channel recommendations, reimbursement considerations and first-customer acquisition strategies for B2B and B2C segments.
-
Risk registers and mitigation plans covering supply chain, regulatory, IP and bioprocess scalability risks — with prioritised tactical responses for 0–6, 6–18 and 18+ month horizons.
Competitive Landscape: Leaders, Challengers and Regional Dynamics
The competitive set is heterogeneous — composed of multinational specialty-chemicals players, synthetic-biology start-ups, cellular-agriculture companies and regionally dominant manufacturers. PW Consulting’s analysis synthesizes public disclosures, patent positions, manufacturing footprints and recent strategic moves to arrive at a pragmatic view of near-term winners and structural opportunities.
-
Evonik Industries — With the market's shift toward clinical-grade inputs, Evonik’s VECOLLAN® platform and its announced availability in clinical-grade formats mark a strategic transition from developer demos to regulated medical supply. For medtech partners seeking traceable, scalable inputs, this is a signal to re-evaluate vendor qualification timelines and master supply agreements.
-
CollPlant Biotechnologies — CollPlant’s progress in bioinks and 3D bioprinting (including preclinical demonstrations of full-sized constructs) and recent study results that compare favorably against legacy matrices exemplify how application-led differentiation—combined with a credible production platform—can unlock premium use-cases in regenerative and aesthetic medicine.
-
Geltor and Jellatech — These innovators are advancing specialized polypeptides and bio-identical collagen constructs geared to consumer-facing ingestibles, longevity and cosmetics. Their strength lies in molecular design and brand-aligned productization, enabling faster consumer adoption in low-regulation categories while building credibility for higher-bar clinical uses.
-
PlantForm and other plant-expression specialists — Plant-based platforms are de-risking allergenicity concerns and offering pathways to vegan, scalable outputs. Their collaborations on fiber-spinning and dry-spinning technologies are important to watch as they translate molecule-to-material economics into differentiated product formats.
-
China-based manufacturers (multiple entrants) — Regional players have demonstrated rapid commercialization of recombinant collagen for skincare and medical dressings, with some obtaining notable regulatory distinctions for implantable formats. Their large-scale fermentation investments and mature OEM/ODM capabilities create a dual dynamic: competitive pricing pressure in commodity applications and partnership potential for capacity-hungry western players.
Market concentration metrics underline strategic realities: the top three companies capture a substantial single-digit multiple of the market (our CR3 estimate), and the top five widen that reach meaningfully. The implication for 2026 is clear: scale provides both pricing power and credibility for clinical supply, but specialization and IP-backed productization remain viable pathways for focused entrants.
Technology and Manufacturing Dynamics
Two technical vectors are reshaping economics and strategic positioning. First, expression system performance: optimized microbial platforms are delivering markedly different yields (for example, contemporary E. coli strains report yields up to ~3 g/L while optimized Pichia strains show peaks above ~10 g/L). These deltas are not academic — they materially affect per-unit COGS and capital intensity for scale-up.
Second, downstream and material processing (including fiber spinning and bioink formulation) are converting molecular capability into product differentiation. Government and industry grants financing codevelopment of dry-spinning and other fiber-forming processes are reducing prototyping lead times and enabling new application forms that expand addressable markets.
Strategic Playbook for 2026 Decision-Makers
-
Prioritise regulatory-first pathways: for companies with clinical aspirations, focus on indications where regulatory clarity and reimbursement levers align with manufacturable product formats.
-
Make the partner vs. build decision explicit: use a total-cost-of-ownership model that internalises time-to-market, quality/regulatory risk and optionality value. Short-term supply agreements with clinical-grade vendors are often superior to greenfield build-outs unless ton-scale demand is certain.
-
Hedge supply risk via multi-source strategies: secure secondary suppliers or toll-manufacturing agreements to avoid single-point failures during pivotal trials and initial launches.
-
Targeted M&A and minority investments: for incumbents, acquire or invest in firms that close critical capability gaps (bioink, fiber formation, or expression-platform IP) rather than broad horizontal plays that duplicate internal capabilities.
-
Differentiate with downstream productization: owning the interface between molecule and use-case (for example, an implantable scaffold or a bioink package) captures outsized value relative to selling raw collagen alone.
Conclusion — The 2026 Imperative
For boards and investment committees planning 2026 allocations, recombinant collagen is no longer an exploratory bet — it is a strategically actionable market. What differs between winners and laggards will be the speed and quality of decisions made this year: clarity on regulatory route-to-value, pragmatic supply strategies, and focused productization will determine whether organizations capture leadership positions in nascent but rapidly consolidating segments.
PW Consulting’s full Recombinant Collagen Market report provides the granular segmentation, financial models, and executable templates required to convert insight into action. This preview outlines the strategic contours — the complete dataset and operational checklists await in the full report for teams preparing to act in 2026.
For detailed analysis of this topic, please visit the official page: Recombinant Collagen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com