

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Reverse Osmosis Market Poised to Reach USD 29.00 Billion by 2032 at 8.24% CAGR — Asia‑Pacific Leads with USD 7.21 Billion in 2025

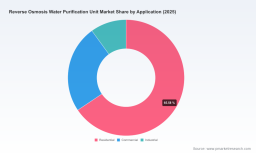
Reverse Osmosis Water Purification Unit Market: Strategic Imperatives for 2026 — PW Consulting Highlights
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an executive preview of our new market research on Reverse Osmosis (RO) Water Purification Units. Built to inform board-level decisions and capital allocation for 2026, this briefing synthesizes the data-driven signals that matter most to equipment manufacturers, system integrators, investors, utilities, and industrial end users. The full report contains the granular segmentation, regional and application breakdowns, and proprietary scenario models — intentionally withheld here to preserve the value of the complete study and to direct readers to our source webpage for subscription access.
Reverse Osmosis Water Purification Unit Market Research
Market trajectory and why 2026 is a strategic inflection
RO water purification is entering a sustained growth phase. Our analysis, anchored on a 2025 base year, documents a compound annual growth rate (CAGR) of 8.24% across the 2026–2032 forecast window. The global market scaled from just over USD 11.2 billion in 2020 to roughly USD 16.7 billion in 2025, and is projected to approach USD 29.0 billion by 2032. This persistent expansion is being driven by a confluence of regulatory tightening, rising water-quality awareness among residential and commercial consumers, industrial demand for high-purity process water, and continued technology-driven cost reductions that expand RO adoption into new use cases.
Reverse Osmosis Water Purification Unit Market Research
For executives making 2026 decisions, these dynamics mean the difference between marginal optimization and seizing first-mover advantage. Our report translates these macro trends into operational and financial playbooks — from near-term procurement strategies to multi-year R&D roadmaps and M&A scouting lists.
Reverse Osmosis Water Purification Unit Market Research
What the report delivers — practical content that CEOs and product leaders will use
-
Strategic market sizing and forecasting: rigorous top-down and bottom-up models, sensitivity scenarios (policy shock, raw-material stress, accelerated desalination uptake) and break-even analyses for common CAPEX/OPEX structures.
-
Competitive and value-chain maps: technology stacks, component sourcing footprints, and vendor scorecards tailored for procurement and partnership decisions.
-
Go-to-market playbooks: segmentation-based positioning, channel economics, service and subscription monetization models, and pilot-to-scale templates for OEMs and integrators.
-
Technology and product roadmaps: comparative assessments of membrane chemistries, energy-recovery integrations, hybrid NF/RO architectures, and embedded digital monitoring platforms.
-
Regulatory impact analysis: scenario planning for pending and prospective regulations (including PFAS-related drinking water rules and wastewater effluent guidance) with compliance cost estimates and remediation prioritization frameworks.
-
Supply chain risk and resilience tools: raw material risk scoring (polysulfone precursors, energy exposure), alternative sourcing strategies, and inventory hedging playbooks calibrated to volatility patterns.
-
Sustainability and end-of-life strategies: practical pathways for module reuse, recycling into UF/NF products, circular-economy business models, and stakeholder engagement templates to address plastic-waste scrutiny.
-
Investment and M&A intelligence: target lists, valuation multiples benchmarking, integration blueprints, and downside stress-testing for strategic acquisitions or joint ventures.
Competitive landscape — leaders, challengers, and strategic implications
The RO market exhibits moderate concentration: the top three players account for roughly a third of market revenue while the top five approach half. This structure creates a competitive environment where global scale and specialized IP coexist as differentiators. Key companies we profile in depth include legacy membrane innovators, global system integrators, and nimble appliance-focused manufacturers.
-
DuPont Water Solutions — A leader in high-rejection thin-film composite membranes, notable for its FilmTec™ portfolio and for enhancing system design capabilities (recent expansion of the WAVE PRO design tool in March 2026 to model RO/NF systems). Strategic interest: licensing, co-development of advanced modules, and digital design tool partnerships.
-
Toray Industries — A global membrane manufacturer with strong materials and process engineering capabilities. Strategic interest: large desalination and industrial project participation, and upstream chemistry collaboration.
-
Hydranautics (Nitto Denko) — Specialized in tailoring membranes for challenging feedwaters; important for municipal and industrial project wins where feed variability is high. Strategic interest: project-specific solutions and aftermarket services.
-
Pentair and Culligan — Residential and commercial system providers with established channel networks. Strategic interest: service-led revenue models, bundled offerings, and retail/OEM partnerships.
-
Veolia (including SUEZ), Evoqua, Nalco/Ecolab — System integrators and full-service providers for municipal and industrial clients with strong delivery and compliance capabilities. Strategic interest: vertical integration, turnkey project delivery, and lifecycle services.
-
Specialist membrane and systems players (Koch, LG Chem, Pure Aqua, APEC, PurePro) — Offer differentiated membrane chemistries, custom systems, and price/quality trade-offs attractive to specific segments. Strategic interest: component-level partnerships and OEM supply agreements.
-
Miura America — A notable entrant in 2026 with industrial RO offerings optimized for boiler-feedwater applications, signalling increasing focus on specialized industrial niches.
Recent developments that reshape near-term choices
-
Design and digitalization: DuPont’s March 2026 extension of the WAVE PRO tool to include integrated RO/NF modeling reduces engineering lead times and lowers project risk—an example of how digital design platforms are becoming procurement differentiators.
-
Product launches: Miura America’s January 2026 industrial RO systems and several consumer-facing introductions at major trade shows in early 2026 (e.g., whole-house and countertop innovations) indicate divergent R&D priorities across industrial vs. residential players.
-
Certifications and market entries: companies showcasing NSF/ANSI and other certifications at high-profile events signal accelerating credentialing activity as a route to U.S. market expansion.
Regulatory and input-cost dynamics — risks and actions for 2026
Regulation is a primary near-term driver. The U.S. EPA’s re-examination of wastewater regulations affecting coal-fired power-plant effluents and its extension/reconsideration of PFAS-related drinking water rules create both compliance obligations and opportunity windows for membrane technology providers. For strategic planners, this translates to two imperatives: model regulatory scenarios into project economics, and prioritize flexible, upgradeable system architectures that can absorb changing discharge or robustness requirements without full replacement.
On the supply side, volatility in key precursor chemicals (e.g., bisphenol-A and dichlorodiphenyl sulfone used in polysulfone production) has generated annual price swings in the high teens to low twenties percent range. Our report includes supplier risk heatmaps and tactical levers — long-term agreements, geographic supplier diversification, and material-substitution roadmaps — that reduce margin erosion during price spikes.
Sustainability and circularity — turning end-of-life into a strategic asset
End-of-life management is emerging from compliance nuisance to strategic differentiator. Estimates suggest millions of RO modules will reach end-of-life annually in the near term, creating both waste management pressure and raw material recovery opportunity. Our practical guidance outlines scalable pathways: modular redesign for component reuse, recycling processes to convert RO elements into UF/NF feedstock, and service models that monetize take-back programs. Companies that integrate circularity into product design and go-to-market propositions can achieve regulatory goodwill, cost offsets, and new value streams.
Five prioritized actions for 2026 decision-makers
-
Operationalize regulatory scenario planning: embed EPA and global regulatory scenarios into capital allocation and product certification roadmaps to avoid stranded assets.
-
De-risk supply chains: secure strategic agreements for polymer precursors, qualify alternate chemistries, and evaluate near-shore manufacturing options to mitigate energy- and logistics-driven volatility.
-
Invest in modular, upgradeable platforms: design systems with swappable membranes and digital overlays to capture service revenue and ease future regulatory upgrades.
-
Pursue targeted M&A and partnerships: prioritize deals that expand membrane IP, digital design capabilities, or service networks — especially in fast-growing use-cases such as industrial boiler-feed and decentralized whole-house systems.
-
Adopt circular-economy pilots now: pilot take-back and recycling programs in a subset of markets to establish operating models and regulatory relationships ahead of broader waste management requirements.
How PW Consulting’s report helps you act
Our report converts public and proprietary datasets into executable insights: actionable segmentation that links product types to channel economics, supplier-by-supplier exposure analysis, prioritized opportunity maps for ROI-focused market entry, and a curated list of partnership and acquisition targets segmented by strategic fit. The analysis is built for executives who must make defensible 2026 decisions — whether to expand manufacturing capacity, re-price aftermarket services, or commit to multi-year supplier contracts.
We designed the publication as a strategic tool: deep enough to build confidence in decision-making, but structured to protect the proprietary segmentation and company-specific metrics that are captured in the full deliverable. For procurement teams, R&D leaders, and corporate development groups, the report is a roadmap for converting the market’s 8.24% CAGR into sustained commercial advantage.
Next steps
For access to the full dataset, granular regional and application splits, vendor benchmarking templates, and the proprietary scenario models that power our forecasts, please visit the PW Consulting report page. Subscribing organizations receive a tailored briefing and a 60- to 90-day implementation support package to translate the report’s insights into a prioritized action plan for 2026.
PW Consulting remains available for executive workshops, M&A diligence support, and bespoke strategy engagements to ensure your organization captures the most valuable opportunities in the evolving Reverse Osmosis Water Purification Unit landscape.
For detailed analysis of this topic, please visit the official page: Reverse Osmosis Water Purification Unit Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com