

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Integral Total Station Market Poised to Reach USD 3,090.85 Million by 2032 at a 6.75% CAGR — Asia Pacific Tops with USD 836.17M

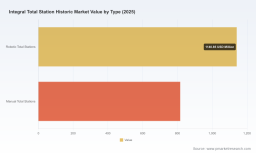
Integral Total Station Historic Market: Strategic Preview for 2026 Decision-Making
Executive snapshot
PW Consulting’s Integral Total Station Historic Market report provides a rigorous, decision-ready view of the total station landscape as companies plan capital allocation, product roadmaps, and go-to-market strategies for 2026. Grounded in five years of historical measurement and a seven-year forecast horizon, the study documents a market that has expanded significantly from 2020 through 2025 and is projected to continue steady, predictable growth through 2032. Key macro indicators — including a compound annual growth rate (CAGR) of 6.75% for the forecast period and clearly defined historical baselines — enable scenario-based planning without relying on anecdote.
Integral Total Station Historic Market
Why this matters to executives in 2026
-
Capital planning: With the market estimated at approximately USD 1.96 billion in 2025 and a trajectory that reaches roughly USD 3.09 billion by 2032 under the central forecast, procurement, R&D, and manufacturing investments must be phased to capture structural demand rather than short-term cyclical upticks.
Integral Total Station Historic Market -
Competitive posture: The industry shows meaningful concentration—our concentration metrics indicate the top three players control more than half of the market while the top five approach three quarters—creating windows for scale-driven differentiation as well as niche specialization.
Integral Total Station Historic Market -
Risk calibration: Supply chain intermittency (notably in sensor components) and evolving calibration/regulatory expectations mean that operational resilience and compliance readiness are now strategic priorities, not merely cost centers.
-
Digital transformation: Recent vendor moves toward cloud-based data management, integrated security features, and automation are accelerating the shift from hardware-first transactions to recurring services and platform monetization.
Macroeconomic and historical context (what the numbers reveal)
Our historical series shows a robust recovery and expansion phase from 2020 to 2025, reflecting renewed infrastructure investment cycles and accelerating adoption of automated surveying solutions across construction, mining, and utility sectors. The 2026–2032 forecast, modeled under multiple demand scenarios, applies a 6.75% CAGR to quantify medium-term opportunity while isolating structural drivers (urbanization, infrastructure renewals, and digitization) from transient shocks.
For strategic planners, the combined picture is clear: demand is not only growing, it is becoming more sophisticated. Buyers are purchasing instruments as part of integrated workflows (hardware, software, cloud) and seeking suppliers that can guarantee uptime, calibration integrity, and secure chain-of-custody for geospatial data.
Report contents — what PW Consulting delivers
This research is engineered for application. Beyond headline market sizing and forecasts, the report contains the following operational modules designed to guide 2026 decisions:
-
Actionable market framework: demand drivers, buyer personas, procurement cadence, and purchase-decision triggers across enterprise and contractor segments.
-
Supply-side diagnostics: component sourcing risk maps, supplier capacity profiles, and cost-inflation sensitivity analyses aimed at informing procurement hedge strategies.
-
Technology and product benchmarking: architecture-level assessments (robotic automation, reflectorless EDM performance, GNSS integration, and imaging-assisted stakeout), feature gap matrices, and upgrade pathways for installed bases.
-
Commercial playbooks: go-to-market sequencing, channel optimization for OEMs and distributors, service and SaaS bundling strategies, and aftermarket revenue models.
-
Regulatory and standards compendium: calibration, testing protocols, and survey accuracy frameworks relevant to international and project-specific requirements.
-
Scenario-based financial tools: sensitivity tables and ROI calculators that translate market outcomes into procurement and product investment thresholds for 2026–2028 planning cycles.
Competitive landscape — who to watch and why
The market combines legacy precision-instrument incumbents, global technology integrators, and a growing cohort of agile manufacturers from Asia. The competitive dynamic is being reshaped by platformization, automation, and services monetization. Our qualitative and comparative analysis highlights several strategic archetypes among incumbents and challengers:
-
Platform innovators: Companies introducing cloud-native data services and integrated security features are shifting value from one-time hardware sales toward recurring revenue streams. Recent product enhancements and platform releases by leading precision-instrument firms exemplify this move.
-
Workflow integrators: Vendors that combine total station hardware with GNSS, field software, and construction-management toolkits are improving on-site productivity and locking-in longer customer lifecycles.
-
Cost & service challengers: A set of vendors focusing on price-performance and regional service coverage are winning new accounts in price-sensitive markets by reducing total cost of ownership and improving local support turnarounds.
Key firms profiled in the report include global leaders known for precision and platform capabilities, several multinational integrators with extensive workflow ecosystems, and a range of regional manufacturers driving innovation on cost, usability, and field durability. We examine recent strategic moves—such as cloud platform rollouts, security and anti-theft integrations, partnerships for project-level deployment, and refreshed robotic product lines—to assess competitive intent and likely next moves through 2026.
Recent vendor developments shaping 2026 tactics
-
Integrated security and cloud data management: Leading precision-instrument manufacturers launched cloud data platforms and device-protection services in 2025 that materially alter the aftermarket support model and the buyer’s calculus for procurement and asset management.
-
Partnerships with large infrastructure contractors: Strategic collaborations announced in recent years embed total station capabilities into project execution workflows, accelerating deployment velocity and favoring suppliers that can integrate across the project lifecycle.
-
Robotic automation and improved data processing: New robotic total station releases continue to push operational productivity, but the most significant commercial differentiator is increasingly the software and ecosystem that surround hardware.
Supply chain, regulation and demand dynamics — what to model
Three structural dynamics must be modeled in every 2026 strategic plan:
-
Component vulnerability: Critical sensor components faced periodic tightness in 2025. Tactical purchasing and strategic stocking policies—alongside multi-sourcing and design modularity—are now standard mitigation options in supplier negotiations.
-
Standards and calibration: Adherence to international calibration and survey-accuracy standards is increasingly enforced by project owners and insurers. Vendors that certify robust calibration regimes and provide traceable testing protocols gain procurement preference.
-
End-market macro drivers: Infrastructure investment programs, urbanization patterns, and sectoral capex in construction, mining, and utilities remain the principal demand engines. Companies should align product roadmaps and field-service footprints with these drivers rather than rely on ad hoc sales cycles.
Strategic playbook for 2026
We advise leaders to embed the following strategic moves into 2026 plans:
-
Shift from transactional to platform economics: Invest selectively in cloud, device security, and data-services capabilities that convert single-instrument purchases into multi-year revenue relationships.
-
Optimize the supply chain for resilience: Implement dual-sourcing for critical sensors, negotiate longer-term contracts with capacity commitments, and design product variants that can tolerate component substitutions without recalibration penalties.
-
Pursue targeted partnerships: Align with construction firms and systems integrators to embed surveying into project workflows early and capture conversion at specification stages.
-
Differentiate through lifecycle services: Bolster calibration, rapid-response maintenance, and training offerings to reduce churn and increase lifetime value.
-
Use concentration to your advantage: In markets where a few vendors dominate, explore alliances or white-label opportunities; in fragmented segments, scale service networks to create defensible moats.
Risks and monitoring framework
Key risks include component price volatility, unexpected regulatory changes, and accelerated platform competition that could compress margins. Our report provides an early-warning indicator set—supply-price thresholds, regulatory adoption triggers, and competitor capability milestones—that enables continuous monitoring and rapid response.
Conclusion — what to do next
As companies enter 2026 planning cycles, PW Consulting’s Integral Total Station Historic Market report offers the empirical foundation and tactical playbooks necessary to align investment, product, and commercial strategies with a market that is both growing and evolving in sophistication. The high-level metrics—including the 2025 market baseline and the forecast path to 2032 at a 6.75% CAGR—frame opportunity size. Our deeper analyses unlock how to convert that opportunity into sustained advantage while mitigating supply and regulatory risks.
To access the full dataset, granular segmentation, and downloadable decision-support tools referenced in this release, please consult the complete PW Consulting report. The comprehensive annexes—featuring calibrated demand models, supplier scorecards, and scenario-specific ROI calculators—are essential for any organization that plans to lead rather than follow in the integral total station market in 2026.
For detailed analysis of this topic, please visit the official page: Integral Total Station Historic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com