

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Fire Retardant Additives Market Tops USD 9,450.0 Million in 2025, Set for Continued Expansion

Fire Retardant Additives Market 2026: Strategic Playbook for Decision-Makers
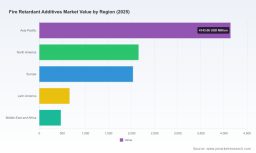
As global industries recalibrate supply chains and product portfolios for a decarbonizing, regulation-intense decade, flame retardant additives remain a strategic input with outsized operational and regulatory risk. PW Consulting’s latest Fire Retardant Additives Market report — with a base year of 2025 and a forecast horizon to 2032 — synthesizes primary research, pricing intelligence, regulatory mapping, and technology road‑maps to equip executives making 2026 investment and portfolio decisions. The market is projected to expand at a compound annual growth rate (CAGR) of 4.95% across the 2026–2032 forecast, building on a market value benchmarked at USD 9,450 Million in 2025 and evolving toward materially higher levels over the forecasting window. This briefing explains the report’s strategic value while preserving key proprietary segmentation detail for subscribers.
Fire Retardant Additives Market
Why 2026 Is a Pivotal Year for Strategic Choices
-
Operational inflection points. Raw material volatility and trade policy shifts have compressed supply buffers and increased procurement complexity. Recent spot-price movements for key feedstocks and the re‑shuffling of trade tariffs mean sourcing decisions made in 2026 will materially affect margin trajectories through 2028.
Fire Retardant Additives Market -
Regulatory acceleration. Several jurisdictions have tightened restrictions on legacy halogenated chemistries, while others are elevating labeling and disclosure requirements. Compliance timelines and substitution costs are front-loaded; delaying reformulation or certification work beyond 2026 raises both legal and go‑to‑market risk.
Fire Retardant Additives Market -
Technology convergence. Proprietary polymeric phosphorus chemistries and engineered mineral fillers (e.g., ATH and magnesium hydroxide derivatives) are maturing simultaneously, creating novel formulation trade-offs between cost, performance, and sustainability credentials.
Top‑line Market Context (What the Numbers Say)
-
Growth trajectory: The global market demonstrated steady expansion in the 2020–2025 historical window and is forecast to continue expanding at a mid-single-digit CAGR (4.95%) through 2032. This macro growth masks divergent dynamics across product classes and end‑use segments that the full report quantifies.
-
Concentration Snapshot: Market concentration is moderate — the top three suppliers account for under half of global revenues, and the top five capture just over half — pointing to persistent fragmentation and opportunity for scale-based competitiveness.
-
Volatility drivers: Short‑term topline movement is strongly correlated with raw material cycles, policy changes in major regulatory jurisdictions, and capital deployment by leading specialty chemical players.
Operational and Commercial Imperatives for 2026
-
Supply‑chain resilience and hedging: With alumina trihydrate and bromine prices experiencing recent spikes due to feedstock constraints and regional production cuts, procurement teams should implement layered hedging strategies (long‑term contracts with indexed clauses, dual-sourcing, and strategic safety stocks) tailored to product chemistry and customer lead‑time tolerance.
-
Regulatory‑first product roadmaps: The tightening of REACH and state-level labeling regimes has accelerated reformulation timelines. R&D and compliance teams must prioritize alternatives that balance performance with acceptance in regulated regions. Early engagement with notified bodies and certification labs in 2026 will shorten time-to-market for replacement chemistries.
-
Commercial pricing models: Sales leaders should revisit pass‑through mechanisms, value‑based pricing for differentiated halogen‑free solutions, and segmented margin targets by application. The report provides sensitivity matrices linking raw material cost swings to gross margins by chemistry class to enable 2026 budget planning.
Competitive Landscape: Profiles and Strategic Positions
Our proprietary competitive framework evaluates technology bread‑and‑butter (e.g., mineral fillers, brominated systems, phosphorus chemistries), go‑to‑market footprint, and investment cadence. Highlights from the competitive set include:
-
Clariant AG (Muttenz, Switzerland) — A leader in halogen‑free phosphorus solutions with a recent product cadence focused on polyolefin applications. Their product launches are aimed at rapid adoption where regulatory pressure is highest.
-
BASF SE (Ludwigshafen, Germany) — Strong in engineered intumescent systems and specialty phosphorus additives, benefiting from scale in engineering plastics and coatings markets.
-
Lanxess AG (Cologne, Germany) — Focused on polyurethanes and flexible foam formulations, with established phosphate ester portfolios.
-
Albemarle Corporation (Charlotte, NC, USA) — A major bromine‑based supplier with deep penetration in electronics and building-materials channels; exposed to bromine price swings.
-
ICL Group Ltd (Tel Aviv, Israel) — Recent capacity expansions underscore an aggressive supply strategy in phosphorus-based chemistries for wire & cable and textiles.
-
Huber Engineered Materials (Atlanta, GA, USA) and Rio Tinto (London, UK) — Positioning around mineral hydrates and engineered fillers; their product positioning plays to composites and cost‑sensitive polymer systems.
-
FRX Polymers (Chelmsford, MA, USA) and Thor Specialties (Speyer, Germany) — Focused on innovation in oligomeric phosphorus polymers and specialized formulations for industrial textiles and niche polymers.
-
Dow Inc. (Midland, MI, USA) — Delivers synergists and integrated additive packages aligned with mainstream polyolefin and styrenic value chains.
Recent corporate moves tracked in our research — including new product launches, capacity expansions, and certification updates — are mapped to likely competitive reactions and pricing implications in 2026. These movements, combined with feedstock price signals and trade-policy changes, form the basis of several near-term disruption scenarios explored in the report.
Risk Scenarios and Strategic Responses
-
Scenario A — Feedstock shock: If alumina trihydrate or bromine prices sustain elevated levels, expect accelerated migration to mineral‑light or polymeric alternatives. Tactical response: prioritize formulations that reduce active load while preserving performance and certify those alternatives for key markets before competitors.
-
Scenario B — Regulatory tightening: Rapid imposition of bans or labeling requirements increases compliance costs and forces product delistings. Tactical response: deploy staged reformulation roadmaps, accelerated sunset clauses for legacy products, and customer communication playbooks to preserve relationships.
-
Scenario C — Consolidation wave: Given mid‑market fragmentation, opportunistic M&A by scale players can shift bargaining power. Tactical response: develop a transaction playbook, identify bolt‑on targets, and run commercial synergies models that stress-test integration assumptions.
What the PW Consulting Report Delivers (Practical, Executable Content)
-
Granular demand model (2020–2032): A transparent, scenario‑capable demand model anchored to engineering assumptions by chemistry class and end application. Subscribers receive the model with editable assumptions for bespoke planning.
-
Supplier heatmaps and procurement scorecards: Vendor‐level assessments covering technical capability, capacity flexibility, pricing behavior, and regulatory risk exposure — built to streamline 2026 sourcing decisions.
-
Regulatory and compliance playbook: Detailed timelines and impact matrices for major jurisdictions, with recommended compliance timelines for product reformulations and certifications.
-
Raw‑material sensitivity analysis: Cost‑to-price pass‑through templates, hedging options, and inventory optimization guidelines calibrated to different lead‑time tolerances.
-
Innovation and product roadmap diagnostics: Comparative evaluation of emergent chemistries (polymeric phosphorus, advanced mineral fillers, synergists) against performance and sustainability KPIs.
-
M&A and partnership framework: Screening criteria, valuation heuristics, and integration checklists tailored to mid‑market consolidation strategies.
-
Commercial playbooks: Sales segmentation rules, pricing architecture templates, and go‑to‑market motions for launching differentiated flame retardant solutions.
How Executives Should Use This Intelligence in 2026
-
CFOs: Calibrate capex and working capital to the report’s stress‑tested scenarios — prioritizing investments in flexible capacity or backward integration where strategic advantage is material.
-
Head of Procurement: Rebalance supplier portfolios using scorecards and initiate flexible contracting options to mitigate raw‑material price spikes.
-
Chief Technology Officer: Fast‑track certification pathways for halogen‑free and low‑toxicity alternatives; use our innovation diagnostics to prioritize chemistries with the best total cost of ownership.
-
Business Development and Strategy Leads: Use our M&A framework to identify targets that fill technology gaps, expand capacity in priority geographies, or deepen penetration in high-margin end uses.
Closing: The Decision Horizon
For stakeholders deciding where to allocate capital, which suppliers to commit to, and which product lines to sunset in 2026, the right intelligence shortens lead times and reduces execution risk. PW Consulting’s Fire Retardant Additives Market report combines market sizing (base year 2025), a transparent CAGR projection (4.95% for 2026–2032), regulatory trackers, supplier diagnostics, and executable playbooks to make those choices operationally tractable. We intentionally preserve detailed sub‑segment datapoints in the full report to ensure subscribers receive the competitive advantage that comes with proprietary modeling and supplier scoring.
Next Steps
-
Download the executive summary on our website for a condensed briefing and schedule a tailored briefing to walk through scenario models relevant to your business.
-
Engage our advisory team for a rapid 4–6 week strategic diagnostic to translate the report’s findings into a bespoke 2026 action plan.
PW Consulting’s multidisciplinary analysis is engineered to bridge the gap between market theory and boardroom execution. For access to the full dataset, granular segmentation, and supplier dossiers that power the models described here, please visit our report page and secure the complete Fire Retardant Additives Market research package.
For detailed analysis of this topic, please visit the official page: Fire Retardant Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com