

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Multi-Junction Gallium Arsenide Solar Cells Market to Soar to USD 2,005.11 Million by 2032 at a 13.01% CAGR

Multi-Junction Gallium Arsenide (GaAs) Solar Cells Market: Strategic Outlook for 2026 Decision-Makers
Executive summary
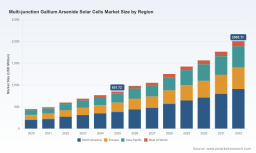
As the global satellite, aerospace and high-concentration photovoltaic sectors accelerate deployment of high-efficiency power systems, the multi-junction GaAs market is entering a phase of sustained expansion. PW Consulting’s new market study — anchored on a 2025 base year and covering historical performance from 2020–2025 with a forecast to 2032 — quantifies a market that has nearly doubled in five years and is projected to maintain a double-digit growth trajectory through the next planning cycle. The market was estimated at USD 851.72 Million in 2025 and is forecast to reach USD 979.63 Million in 2026, growing at a compound annual growth rate (CAGR) of 13.01% over the 2026–2032 period to reach an anticipated USD 2,005.11 Million by 2032.
Multi Junction Gallium Arsenide Solar Cells Market
For 2026 corporate planning, these topline dynamics imply a market environment where scale and technology differentiation matter in equal measure. Our analysis shows a concentrated supplier base (CR3 ~62.5%, CR5 ~78.4%), meaningful supply-chain vulnerability around critical III-V inputs, and accelerating technology milestones that are reshaping product roadmaps and procurement strategies. This release highlights the strategic implications; the full report contains the operational playbooks, quantitative models and supplier dossiers that executives will need to act with conviction.
Multi Junction Gallium Arsenide Solar Cells Market
Why these macro trends matter for 2026 decisions
-
Rapid commercialisation window: The market’s near-term jump from USD 851.72M (2025) to USD 979.63M (2026) signals a compressing window for securing qualified supply and flight heritage — a key constraint for satellite OEMs and constellation investors planning 2026–2028 launches.
Multi Junction Gallium Arsenide Solar Cells Market -
High-growth runway: At a modeled CAGR of 13.01% across 2026–2032, demand growth will compound supplier advantage for firms that retain manufacturing scale and technology leadership. Firms that delay strategic investments risk higher sourcing costs or longer qualification cycles as lead times lengthen.
-
Market concentration: With the top three and five suppliers commanding a dominant share of the market, bilateral commercial structures, long-term offtake agreements and co-development partnerships will increasingly determine who wins mission contracts and who competes for commoditised opportunities.
Competitive landscape — what to watch in 2026
The multi-junction GaAs ecosystem remains anchored by firms with deep flight heritage and specialized manufacturing capabilities. Our report profiles each major player and evaluates their strategic positioning across technology, cost-to-qualify, production scale and partner networks.
-
Spectrolab Inc. (Boeing subsidiary): A legacy leader in space-grade multi-junction cells with proven >30% AM0-class architectures and extensive flight qualification. Its incumbency on high-profile missions makes it a natural strategic partner for prime contractors.
-
AZUR SPACE Solar Power GmbH: European specialist with a balanced footprint across space PV and terrestrial concentrator projects. Strong relationships with European primes position it well for continental programs and qualification flows.
-
EMCORE Corporation: Focuses on radiation-hardened designs and recently announced a notable triple-junction efficiency milestone in its R&D program — an indicator of the pace of incremental performance gains that can shift system-level trade-offs.
-
MicroLink Devices: A technology differentiator through flexible, lightweight cells produced by epitaxial lift-off and inverted metamorphic routes — particularly relevant to mass-constrained smallsats and novel aerospace platforms.
-
SolAero Technologies (now under Rocket Lab ownership): Emphasizes high power-to-mass architectures and turnkey panel assemblies for satellite constellations — an attractive offering for integrators focused on rapid deployment.
-
Sharp, Alta Devices, CESI and other specialized suppliers: These firms collectively contribute materials know-how, niche manufacturing options and qualification services critical to mission assurance and commercial CPV applications.
The full competitive module in our report includes supplier scoring across 40+ criteria (technology readiness, qualification backlog, vertical integration, foundry access, IP position, and pricing power) and a map of realistic co-sourcing pathways for buyers seeking to reduce single-supplier exposure.
Industry dynamics, risks and supply-chain realities
-
Critical raw materials: Gallium remains a fundamental input. Recent USGS intelligence places average gallium import unit value near USD 580 per kilogram in 2025, and primary low-purity production is highly geographically concentrated. These realities create price and availability volatility that cascades through epitaxy costs and device margins.
-
Geopolitics and trade policy: Regulatory shifts in 2024–2025 materially affected supply flows. Notably, a temporary export policy adjustment in late 2025 eased certain constraints, while tariff regimes and targeted equipment exclusions persist in influencing near-term sourcing strategies. Buyers and investors must bake varying trade-policy scenarios into procurement and capital-allocation decisions for 2026.
-
Technology and performance: Incremental efficiency improvements—such as recent breakthroughs reported by industry participants—are accelerating capability updates and shortening product lifecycles. Firms that can move from lab milestones to qualified flight products fastest will capture disproportionate margin and specification-led demand.
-
Funding and policy support: Public-sector R&D investment into III-V photovoltaics and concentrator technologies is increasing, aimed at reducing material and manufacturing costs. These programs create co-funded pathways for shared risk in scaling novel architectures, and they form part of the incentive calculus for private R&D commitments in 2026.
What the PW Consulting report delivers (practical, actionable outputs)
Our study was designed to be a 2026 playbook for corporate strategy and M&A teams, procurement leaders, and technology heads. Key deliverables include:
-
Topline and scenario-based market models (historical 2020–2025; base year 2025) with roll-forward forecasts to 2032, sensitivity analysis and demand-by-application scenarios to stress-test capex plans.
-
Supplier dossiers and a 40+ metric scorecard mapping production capacity, qualification timelines and probable qualification windows for different customer archetypes (satcom primes, constellation operators, aerospace integrators, CPV vendors).
-
Supply-chain heatmaps identifying single points of failure (materials, epitaxy capacity, specialized thin-film steps), plus recommended mitigation levers and commercial contracting templates to lock supply at acceptable economics.
-
Technology roadmaps and cost curves illustrating where efficiency gains, mass-reduction techniques (ELO/IMM), and manufacturing scale materially alter system-level cost-per-Watt and mission trade-offs.
-
M&A and partnership playbooks tailored to acquirers seeking bolt-on technologies, near-term capacity additions, or de-risked access to flight-proven product lines.
Actionable recommendations for 2026
-
Prioritise supply diversification early. Given the concentrated supplier landscape and material exposure, secure second-source routes through qualified foundries or co-development arrangements today to avoid steep lead-time and qualification premiums in 2027–2028.
-
Lock in strategic material hedges and collaborative purchasing for gallium and specialty substrates. Contracts that include price-band mechanisms or shared inventory provisions materially reduce program-level cost volatility.
-
Translate laboratory efficiency gains into a clear qualification roadmap. If your organisation relies on specification-led procurement, require suppliers to present a six- to twelve-month qualification-to-flight path when evaluating new cell architectures.
-
Consider targeted vertical integration or JV with epitaxy/service providers where margin capture and schedule control justify capital commitment. Our cost models identify break-even thresholds for in-house epitaxy versus long-term outsourcing.
-
Use public R&D and incentive programs as leverage for co-funded risk-sharing. Engage national labs and relevant DOE initiatives to accelerate cost-downs in materials and concentration methods while preserving proprietary system integration work.
-
Embed trade-policy scenarios into procurement and program budgets. Build contingency buffers and alternative logistics routes to account for tariff changes and export-control shifts that may re-emerge in short policy cycles.
-
Prioritise partners with flight heritage for mission-critical deployments and pursue smaller, flexible suppliers for experimental or risk-tolerant platforms where weight or flexibility yields system advantage.
How PW Consulting accelerates decision-making
Beyond market numbers, our approach is operational: we convert forecasts into executable options. For 2026 planners this means receiving not just demand curves but procurement templates, heatmaps of supplier risk, and M&A candidate shortlists that are vetted against both technical and commercial thresholds. The report is structured to move a strategic discussion from “what might happen” to “what we will do” within 30–90 day decision cycles.
Next steps
Executives preparing capital plans, supply agreements or technology roadmaps for 2026 should treat this study as a strategic brief and operational toolkit. To preserve the commercial edge and because the most valuable segmentation and supplier-level data are intentionally gate-kept, PW Consulting is making the full dataset, supplier scorecards and scenario models available through the report portal. Access to the complete deliverables will allow teams to run custom scenarios against their specific program timelines, procurement constraints and regulatory exposures.
Contact PW Consulting to obtain the full Multi-Junction Gallium Arsenide Solar Cells Market report and the companion decision-support package that operational teams can plug directly into 2026 planning workflows.
For detailed analysis of this topic, please visit the official page: Multi Junction Gallium Arsenide Solar Cells Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com