

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 6.42% CAGR for Automated Side Load Garbage Trucks Market Through 2032

Automated Side Load Garbage Trucks Market: A Strategic Preview for 2026 Decision-Makers
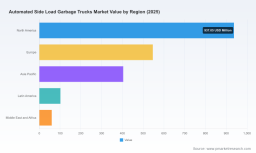
PW Consulting’s latest market study on Automated Side Load Garbage Trucks (base year 2025) arrives at a pivotal moment for municipal fleets, haulers, OEMs and investors. Built on proprietary modelling across the 2020–2025 historical window and a 2026–2032 forecast horizon, the analysis quantifies market momentum—showing growth from USD 1,502.4 Million in 2020 to USD 2,050.0 Million in 2025, and a projected rise to approximately USD 3,168.9 Million by 2032 at a compound annual growth rate (CAGR) of 6.42%. This briefing explains why those numbers matter in 2026 and how executives should translate them into practical moves that protect margins, accelerate decarbonization, and capture service-led revenue.
Automated Side Load Garbage Trucks Market
Why the 2026 Inflection Matters
Two interlocking forces are pushing automated side loaders to the center of fleet investment plans. First, regulatory tightening in North America and Europe is making low- and zero-emission collection platforms an operational imperative rather than an option. Second, rapid product evolution—encompassing independent battery systems for collection duties, smarter arm mechanics, and mandatory safety systems—means that replacement cycles and retrofit pathways carry meaningful financial and operational implications.
Automated Side Load Garbage Trucks Market
PW Consulting’s modelling shows that the market is no longer a niche technical play: steady, mid-single-digit CAGR coupled with accelerating electrification and safety-driven upgrades creates a multi-year runway for suppliers and service providers. For public-sector procurement teams and private operators planning 2026 budgets, this is the moment to move from exploratory pilots to structured fleet transition programs.
Automated Side Load Garbage Trucks Market
Market Dynamics: Regulation, Technology and Total Cost of Ownership
-
Regulatory acceleration: Environmental standards and municipal clean-air targets are raising adoption pressure for electric and CNG-compatible automated side loaders. Compliance is now tied directly to procurement decisions, grant eligibility, and lifecycle emissions accounting.
-
Safety as a compliance and value lever: Automated side loaders must increasingly integrate anti-collision sensors, operator presence detection, and emergency override systems to meet OSHA and EU Machinery Directive requirements. These systems reduce liability and can improve route efficiency, but they require investment in validation and policies for field retrofits.
-
Powertrain and systems integration: Leading electric variants operate with independent battery packs to power collection mechanisms while remaining compatible with multiple chassis types. This architectural pattern enables modular upgrades—an important consideration for mixed fleets during the 2026–2029 transition window.
-
TCO drivers: Beyond sticker price, executives must model compaction efficiency, utilization, maintenance intervals for hydraulic arms, battery lifecycle and residual values. Our scenarios show that properly managed electrified automated side loaders can achieve competitive TCO within 5–7 years depending on duty cycles and energy costs.
Product and Segment Characteristics to Watch
-
Mechanics and ergonomics: Common designs include hydraulic arms capable of lifting containers from roughly 30 to 300 gallons, with reach envelopes up to about 9 feet. Compaction rates in many designs approach high single-digit hundreds of pounds per cubic yard, making body selection a key determinant of route productivity.
-
Power architecture: Electric collection bodies that utilize independent battery systems reduce chassis constraints and allow pairing with diverse truck platforms—an important enabler for municipalities seeking fleet flexibility.
-
Serviceability and retrofitability: The long operating life of refuse bodies means retrofit options—safety suites, alternative-fuel conversions, or battery packs—will be a major aftermarket growth area through the late 2020s.
Competitive Landscape: Who’s Shaping the Market
Our competitive review profiles the established bodybuilders and specialists defining the automated side loader segment. These firms represent diverse strategic profiles: legacy OEMs intensifying electrification programs, specialist players focused on one product line, and mid-sized builders emphasizing versatility and durability.
-
Heil Environmental (Chattanooga, Tennessee) —Heil’s portfolio spans the DuraPack continuous-pack platforms and the RevAMP Electric side load body. The company’s emphasis on extended-reach arms and purpose-built electric bodies positions it well for residential and mixed-service routes that prioritize reach and zero-emission operation.
-
McNeilus Truck and Manufacturing (Dodge Center, Minnesota) —With models like Zero Radius and AutoReach, McNeilus emphasizes modularity, arm geometry for constrained environments, and flexibility across powertrains. Their strength lies in balancing traditional diesel platforms with electrified options.
-
Labrie Enviroquip Group (Quebec) —Labrie’s Expert and Automizer series offer manual-to-fully-automated permutations, supporting municipalities that require mixed-mode operations during transition. Their North American footprint supports rapid aftermarket response in key markets.
-
New Way Trucks (Scottdale, Iowa) —Models such as Sidewinder and Wolverine focus on high lift capacity and under-CDL options that enable lightweight chassis pairings—beneficial where route density and maneuverability are priorities.
-
Amrep (California) —Amrep’s use of wear-resistant steels and broad product set (front loaders, side loaders, hoists) positions the firm as a durability-first supplier to contractors with heavy-duty routes and high abrasive loading.
-
Curbtender Inc. (USA) —A historic innovator in the segment, Curbtender remains focused on automated side loaders with a tight product portfolio and deep operational know-how—an advantage for service reliability and route-focused engineering.
-
KANN Manufacturing (USA) —KANN’s Curb Master bodies span a range of volumes and compaction strategies, including full-eject options. Their product set is aimed at maximizing payload and reducing cycle times on dense collection routes.
For procurement teams, supplier selection will hinge on three strategic vectors: compatibility with fleet decarbonization timelines, service network depth, and modular upgrade pathways that protect capital investments as regulations and routes evolve.
Strategic Recommendations for 2026
-
Move from pilot to program: Municipal and private fleets that ran pilots through 2024–2025 should now formalize staged rollouts with clear KPIs—availability, energy use per route, operator ergonomics, and safety incidents per 10,000 lifts. Aim for outcome-based procurement clauses that tie payments to availability and verified emissions reductions.
-
Prioritize modular architectures: When evaluating new body purchases, prioritize designs with independent collection batteries or modular sub-systems. These architectures lower obsolescence risk and enable phased electrification.
-
Invest in safety and digital retrofits: Anti-collision and operator-presence systems are now compliance items in many jurisdictions; retrofitting existing fleets can buy time and mitigate occupational safety exposure while full replacements are staged.
-
Redesign procurement and financing: Seek mixed financing (operating leases, performance bonds, grants) to smooth capital outlays. Include warranty-extension and depot-spares clauses to protect uptime—serviceability is a differentiator that affects TCO materially.
-
Forge strategic supplier partnerships: Leading bodybuilders can be co-investment partners in trials, battery lifecycle programs and local service hubs. Structured partnerships reduce lead times and secure prioritization for chassis supplies and bodies alike.
-
Plan for aftermarket and residual value: Forecasting residuals and setting trade-in agreements today will reduce future replacement costs. Consider standardized telematics and data schemas to preserve resale value and simplify fleet handovers.
What PW Consulting’s Full Report Delivers
Our full market study goes well beyond headline market sizing. It provides the operational playbooks and procurement tools that matter to 2026 strategists, including:
-
Scenario-based forecasts and sensitivity analyses (fuel price swings, capex subsidies, regulatory tightening) calibrated to route density and duty cycles.
-
Supplier benchmarking across product design, electrification readiness, aftermarket coverage and service SLAs—presented as actionable scorecards to streamline RFPs.
-
Fleet transition frameworks that include pilot design templates, KPIs, depot conversion checklists, and operator training modules.
-
Procurement templates for outcome-based contracts, leasing structures, and risk-sharing arrangements suited to public-private partnerships.
-
Technical appendices on arm mechanics, compaction performance, battery integration patterns and retrofit feasibility that inform both engineering and capex teams.
-
Primary-data driven insights from OEM interviews, supplier specifications and fleet deployments informing pragmatic adoption timelines and cost curves.
How to Use This Intelligence in 2026
Executives should use the report as a decision-calibration instrument: benchmark current fleet economics against PW Consulting’s scenarios, stress-test procurement specifications for regulatory and safety compliance, and prioritize investments that improve uptime and reduce lifecycle emissions intensity. For suppliers and investors, the report identifies where to focus R&D (battery-integration, sensor suites, compact high-efficiency compaction bodies) and where service models can capture recurring revenue.
We crafted this preview to highlight strategic direction and the operational levers that matter in 2026 while preserving the detailed, cited segment-level analytics that underpin supplier negotiations and investment commitments. To unlock the full datasets, supplier scorecards and ready-to-use procurement templates that will inform next-generation RFPs and capital plans, access the complete PW Consulting Automated Side Load Garbage Trucks Market report.
For detailed analysis of this topic, please visit the official page: Automated Side Load Garbage Trucks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com