

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Acquired Immunodeficiency Syndrome Market Set to Expand at a 5.42% CAGR Over 2026–2032

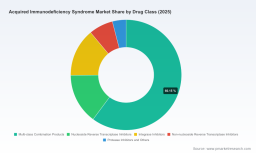
Acquired Immunodeficiency Syndrome Market 2026: Strategic Intelligence for Decision-Makers
Executive snapshot
PW Consulting's latest Acquired Immunodeficiency Syndrome (AIDS/HIV) Market report equips life‑science executives, payers, procurement agencies and investors with the strategic intelligence required to make high‑stakes decisions in 2026. Built on a five‑year historical baseline (2020–2025) and a seven‑year forecast window (2026–2032), the study projects the global market to expand at a 5.42% compound annual growth rate (CAGR). In monetary terms the market is assessed at roughly USD 36,250 Million in the base year (2025) and is modeled to approach the mid‑USD 52,000 Millions by 2032 under our core scenario.
Acquired Immunodeficiency Syndrome Market
Why this report matters in 2026
-
Timing: 2026 is a watershed year marked by multiple regulatory milestones, late‑stage clinical readouts and the first wave of large‑volume generic entry planning to reshape access dynamics. The report interprets these inflection points into concrete strategic choices.
Acquired Immunodeficiency Syndrome Market -
Actionability: Beyond market sizing and forecasts, the deliverable emphasizes commercially actionable outputs — launch readiness playbooks, payer engagement scenarios, and procurement/pricing models tailored to differing country archetypes.
Acquired Immunodeficiency Syndrome Market -
Concentration and competitive pressure: The market remains highly concentrated, with the top three and top five players capturing the majority share — a structural reality that influences pricing, innovation incentives and partnership calculus.
Market trajectory: what the macro numbers tell us
The AIDS market’s mid‑decade momentum reflects several converging forces. Long‑acting prevention and maintenance options have accelerated uptake in higher‑resourced health systems while persistent unmet needs and large treatment programs in low‑ and middle‑income countries sustain baseline demand. Our base‑case forecast translates a steady 5.42% CAGR into an incremental expansion of the market from an assessed 2025 value of approximately USD 36.25 billion to an expected market exceeding USD 52 billion by 2032. Short‑term volatility tied to discrete product launches and access agreements is modeled through alternate scenarios in the report, enabling clients to stress‑test commercial plans against optimistic and downside uptake curves.
What’s inside the report: practical modules
-
Market sizing & forecast engine — deterministic and scenario branches across 2026–2032 with sensitivity to pricing, procurement timelines and generics entry. (Note: detailed regional and drug‑class splits are reserved for the full report.)
-
Pipeline & clinical watchlist — phase‑by‑phase tracker for next‑generation oral and long‑acting modalities, including probability‑adjusted launch timelines and commercial risk assessments.
-
Commercial opportunity matrices — prioritized segments and country archetypes for market entry, differentiated by payer fragmentation, procurement mechanisms and local manufacturing constraints.
-
Access & pricing playbooks — contracting templates and tiered pricing scenarios aligned to donor, government and private payer models; procurement timing simulations for program managers.
-
Supply chain and capacity assessment — supplier maps, API bottleneck analysis and mitigation strategies for scale‑up of long‑acting injectable production.
-
M&A and partnership intelligence — target screening criteria, valuation comparators and integration checklists for buyers seeking inorganic growth in therapeutics, diagnostics and service platforms.
-
Regulatory and reimbursement trackers — rolling updates on pivotal approvals and HTA outcomes that materially affect uptake curves.
Competitive landscape: strategies to watch
The therapeutic field is polarized between specialist HIV players with deep portfolios in long‑acting and single‑tablet regimens, and large generic manufacturers enabling scale in volume markets. Leaders are pursuing three parallel routes to sustain growth: innovation in dosing and delivery, broadening combinations to extend patent life and indication, and access partnerships that preempt competitive erosion in high‑volume low‑price markets.
-
Innovation leaders: Major originators are doubling down on long‑acting injectables and combination single‑tablet regimens to defend premium pricing and adherence benefits. Late‑stage clinical results for new combinations and switch studies (presented in 2026) are important demand signals that the report analyzes in depth, including expected time‑to‑peak sales and cannibalization risk against existing regimens.
-
Generics and access players: Several established generic manufacturers are positioned to supply high‑volume treatment programs and LMIC prevention initiatives. Planned agreements for low‑cost formulations — including announced arrangements to provide prevention injectables at highly concessional unit economics — will materially compress pricing in targeted markets and are modeled in our access scenarios.
-
Collaborators and new entrants: Strategic alliances between originators and generics, as well as cross‑company co‑development deals, are reshaping incumbents’ competitive moats. The report identifies where partnerships create mutual value (e.g., combined R&D and pooled procurement), and where they introduce execution risks (manufacturing scale, IP carve‑outs).
Recent industry signals and their implications
-
Regulatory momentum: The approval of new regimens during 2025–2026 and key NDA acceptances have compressed the uncertainty window for some late‑stage assets. Our commercial uptake models incorporate approved product launches and near‑term regulatory catalysts that will determine 2026 adoption curves.
-
Clinical readouts: Positive phase‑3 switch‑study data for investigational combination regimens strengthen the case for targeted switching programs in virologically suppressed populations. The report quantifies likely switch rates under conservative and accelerated adoption assumptions.
-
Access agreements: Concessional pricing deals announced for prevention injectables and generic licensing pathways for certain novel agents introduce a bifurcated pricing landscape — premium markets where originator brands maintain higher prices and large volume public programs where concessionary pricing is expected. We model the revenue tradeoffs and margin impacts for each archetype.
Strategic implications for 2026 — an action agenda
We translate insights into a focused checklist for executive teams to act on this year. The report expands each item into executable next steps and templates; the highlights below indicate the priority sequence for 2026.
-
Reassess portfolio prioritization with dosing modality in mind. Prioritize resources for long‑acting injectables and simplified FDCs that demonstrably improve adherence or reduce total cost of care.
-
Model dual‑track pricing strategies. Prepare differentiated commercial playbooks for premium payers and large public procurement channels to protect revenue while securing scale in high‑volume markets.
-
Lock strategic manufacturing and API capacity early. Scenario planning should include rollover contracts and contingency suppliers for injectable manufacturing and specialized API supply.
-
Pursue targeted partnerships with global procurement agencies. Engage CHAI, Unitaid and major multilateral purchasers with submission packages that demonstrate total cost of ownership and programmatic feasibility.
-
Invest in real‑world evidence and adherence infrastructure. Payer acceptance for premium products increasingly depends on robust outcomes data; build pragmatic trials and registry plans pre‑launch.
-
Screen M&A opportunities for complementary capabilities — small biotech with novel delivery tech, regional manufacturers with WHO prequalification, or niche diagnostics that de‑risk regimen selection and adherence monitoring.
Risk and monitoring framework
Key risks to monitor through 2026 include faster‑than‑anticipated generic penetration in major high‑volume markets, slower public procurement rollouts for new prevention tools, and unexpected safety or resistance signals from broader population use. The report provides a prioritized early‑warning dashboard (regulatory milestones, tender wins, price announcements, and real‑world uptake metrics) so clients can trigger contingency plans with minimal lag.
Conclusion: what PW Consulting delivers
Our Acquired Immunodeficiency Syndrome Market report is built to inform immediate 2026 choices while providing a durable strategic playbook to 2032. By combining rigorous macro‑modeling (historic 2020–2025; base year 2025; forecast 2026–2032 at a 5.42% CAGR), transactional intelligence, and executable go‑to‑market modules, the study helps leaders convert uncertainty into prioritized action.
To preserve competitive value, the public summary intentionally omits the granular regional and drug‑class level allocations. For full access to the detailed segmentation, regional scenarios, and the downloadable commercial toolset referenced throughout this briefing, visit PW Consulting’s Acquired Immunodeficiency Syndrome Market report page or contact our advisory team to schedule a briefing and receive the complete dataset and modeling workbook.
For detailed analysis of this topic, please visit the official page: Acquired Immunodeficiency Syndrome Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com