

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Precision Agriculture GNSS Guidance Market to Nearly Double from USD 3.53B in 2025 to USD 6.35B by 2032 at 8.75% CAGR — North America Leads with USD 1.41B in 2025

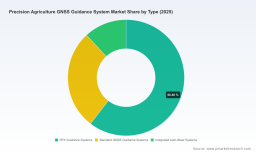
Precision Agriculture GNSS Guidance System Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting today releases an advanced preview of our forthcoming market intelligence on the Precision Agriculture GNSS Guidance System market. Designed as a decision-grade briefing for senior executives, product leaders, investors, and policy teams, this preview frames the near-term strategic choices that will determine competitive advantage in 2026 and beyond. Our analysis integrates a full market sizing and forecast anchored to a 2025 base year (USD 3,530.0 Million) and projects continued expansion at a compound annual growth rate (CAGR) of 8.75% through the 2026–2032 forecast window, underscoring a trajectory toward meaningful scale for high-precision guidance technologies.
Precision Agriculture Gnss Guidance System Market
Why 2026 is a Strategic Inflection Point
-
Acceleration in adoption: Farmers and contractors are moving from pilot deployments to fleet-level rollouts. The economics of precision steering and active implement control—improved yields, input savings, and labor productivity—are reaching a tipping point where capital allocation decisions in 2026 will lock in share for the next product cycle.
Precision Agriculture Gnss Guidance System Market -
Technology differentiation is narrowing: High-precision positioning (RTK, PPP and carrier-phase solutions), sensor fusion and vision systems are becoming table stakes. Innovations in robustness (e.g., ionospheric disturbance mitigation) and in non-GNSS fallbacks will be decisive for reliability in marginal conditions.
Precision Agriculture Gnss Guidance System Market -
Regulatory and market catalysts: Policy moves and infrastructure changes—such as free regional augmentation services, upcoming GPS datum modernization activities, and government incentives—create time-bound windows for product updates, farmer outreach programs, and channel incentives.
Key Macro Signals and Their Strategic Implications
-
Market scale and growth profile: With the global market anchored at USD 3,530.0 Million in 2025 and an 8.75% CAGR to 2032, supplier strategies should balance near-term monetization with investments in modular platform architectures that deliver multi-year revenue streams.
-
Consolidation dynamics: The market exhibits meaningful concentration at the top—our analysis shows the three largest vendors control a majority share and the top five concentrate nearly seven in ten dollars—creating both barriers and acquisition opportunities for challengers and new entrants.
-
Regulatory inflection points: EGNOS and similar augmentation services materially alter value propositions in regions where they are available by lowering operating costs for high-accuracy guidance. Meanwhile, the 2026 GPS datum modernization requires firmware, mapping, and workflow updates for systems used in mapping and guidance to avoid operational drift—making a 2026 compliance roadmap essential for OEMs and retrofit providers.
-
Funding and adoption incentives: Public programs, notably new provisions in the 2026 US Farm Bill, increase affordability via high reimbursement rates for precision agriculture technology adoption. Suppliers that align channel financing and incentive-aware go-to-market models stand to accelerate penetration.
Competitive Landscape — Who Matters and Why
The competitive field is populated by a mix of vertically integrated OEMs, specialized guidance suppliers, and GNSS component incumbents. Competitors fall into at least three strategic archetypes: OEM-integrated platform owners, universal retrofit/guidance specialists, and GNSS receiver and correction-service providers. Recent vendor activity illustrates these strategic plays.
-
John Deere (Deere & Company) — A platform-first incumbent with factory-integrated AutoTrac and StarFire ecosystems designed for seamless user experience across machines. Deere’s strength lies in brand, dealer networks, and the integration of guidance into machine lifecycle services.
-
PTx Trimble (Trimble / PTx Trimble) — A retrofit and mixed-fleet enabler offering Autopilot and Precision-IQ with RTK/RTX corrections and recent advances in ionospheric disturbance mitigation (IonoGuard). Trimble’s multi-vendor compatibility and precision services make it a default choice where fleet heterogeneity is high.
-
CHC Navigation (CHCNAV) — A retrofit specialist positioning with competitive precision via its NX series and PointSky PPP service, emphasizing cost-effective cm-level accuracy in challenging coverage areas.
-
Hexagon (NovAtel / HxGN AgrOn) — OEM-aligned GNSS receiver and antenna supplier focusing on TerraStar corrections and integration partnerships with machine manufacturers seeking turnkey precision subsystems.
-
Topcon — A systems supplier extending into autonomy through partnerships (notably with robotics players for vision-integrated autonomy), blending correction services with guidance controls.
-
AG Leader, CNH Industrial (Raven), Hemisphere GNSS (Outback Guidance) — Each occupies niche positions from console- and data-centric solutions to modular guidance stacks and GNSS product lines, collectively shaping aftermarket choices and integration complexity.
Notable recent moves include Trimble’s introduction of IonoGuard to improve RTK robustness during ionospheric disturbances and Trimble/PTx’s product showcases that signal expanded retrofit and active implement capabilities; CHCNAV’s market positioning of NX series with PPP services; and Topcon’s strategic partnership with a robotics firm to marry vision autonomy with GNSS control. These actions reflect an industry shifting from single-technology differentiation to integrated stack strategies (GNSS + correction services + perception + autonomy).
What the Full PW Consulting Report Contains (Practical, Actionable Deliverables)
-
Methodology and market model: Transparent assumptions, sensitivity testing, and downloadable forecasting models (Excel) that permit users to run alternate scenarios without exposing proprietary segment line-item disclosures in this preview.
-
Scenario planning: Three conviction-weighted scenarios mapping technology adoption, policy interventions, and supply-chain shocks to revenue and margin outcomes through 2032.
-
Vendor benchmarking: Multi-dimensional scorecards covering precision performance, integration footprint, channel strength, service monetization and R&D trajectories (detailed company profiles are provided in the full document).
-
Commercial playbooks: Go-to-market templates for OEMs, aftermarket suppliers and channel partners—including financing and incentive alignment to capture rebate-driven demand.
-
Operational checklists: GPS datum modernization readiness, firmware compatibility matrices, and field validation protocols for ionospheric resilience and RTK/PPP switching strategies.
-
M&A and partnership directory: A calibrated list of acquisition and alliance targets, and quick-screen metrics for diligence prioritization (including integration cost ranges and expected time-to-value).
Strategic Priorities and Tactical Moves for 2026
-
Update product roadmaps immediately to account for GPS datum modernization and regional augmentation services. Firms that incorporate datum-change timelines into firmware and mapping releases will avoid operational gaps that erode customer trust.
-
Prioritize robustness in positioning. Invest in ionospheric disturbance mitigation, hybrid PPP/RTK failover workflows, and sensor fusion (vision + IMU) to guarantee uptime in marginal conditions—this capability is becoming a transaction winner in mixed-fleet environments.
-
Go-to-market: design incentive bundles aligned to reimbursement programs. With generous public funding available in key markets, offering turnkey installation + finance + rebate handling will materially shorten sales cycles.
-
Service monetization: move up the value chain by packaging correction subscriptions, data services, and fleet analytics. The growth profile favors platforms that convert one-time hardware sales into recurring revenue.
-
Channel & partnerships: accelerate pilot-to-deployment transitions by building dealer enablement kits, retrofit centers of excellence and verified integration partnerships with autonomy/vision players—Topcon’s partnership trend is an early signal.
-
Supply chain resilience: mitigate commodity and tariff exposure via dual-sourcing and inventory hedging for critical components; early planning reduces price volatility and protects launch timelines.
-
M&A play: the market’s concentration suggests well-timed acquisitions of niche retrofit specialists, correction-service providers, or analytics firms can unlock rapid capability build without protracted R&D cycles.
Using This Report to Inform Board-Level Decisions in 2026
Executives need a concise set of investment options with quantified outcomes. The full PW Consulting report equips decision-makers with: scenario-based ROI curves, supplier risk heatmaps, prioritized product feature backlogs tied to customer willingness-to-pay, and a playbook for channel activation aligned with public reimbursement schedules. Whether the mandate is to defend market share, enter aftermarket retrofit, or pursue inorganic growth, the report translates market dynamics into executable programs with timing guidance calibrated to 2026 windows of opportunity.
Next Steps and How to Access the Complete Intelligence
This preview highlights the strategic contours and immediate actions that will shape winners in the Precision Agriculture GNSS Guidance System market. For full access to granular forecasts, proprietary segmentation, vendor scorecards, and the operational toolkits described above, please visit the PW Consulting report page. The full report contains the detailed data and executable templates necessary to convert the 2026 inflection into sustained competitive advantage.
PW Consulting — Senior Strategic Advisory & Industry Analysis Team
For detailed analysis of this topic, please visit the official page: Precision Agriculture Gnss Guidance System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com