

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Acute Care Telemedicine Market Poised for Rapid Growth — 14.82% CAGR Forecast Through 2032

Acute Care Telemedicine Services Market: Strategic Directions for 2026 — PW Consulting Executive Brief
As health systems, payers, and technology providers prepare budgets and strategic roadmaps for 2026, acute care telemedicine has moved from “opportunity” to operational imperative. PW Consulting’s latest market research — anchored on a 2025 base year, with historical analysis from 2020–2025 and a forecast window spanning 2026–2032 — synthesizes commercial, clinical, regulatory, and operational intelligence that senior executives need to convert momentum into sustainable advantage.
Acute Care Telemedicine Services Market
Market snapshot: scale, pace, and implications
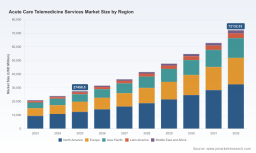
The acute care telemedicine market is expanding rapidly. Our model projects growth from a firm 2025 baseline to more than double that scale by 2032, reflecting a compound annual growth rate (CAGR) of 14.82% through the forecast period. This pace signals structural adoption across hospital systems, community networks, and specialized telemedicine vendors and implies sustained investment in clinical staffing, network infrastructure, and integrated care pathways.
Acute Care Telemedicine Services Market
For decision-makers, the implications are threefold: (1) timing matters — early strategic alignment with telemedicine-enabled care models captures disproportionate operational and clinical benefits; (2) scale and margin dynamics are shifting — platform providers and vertically integrated clinical services are beginning to drive differential pricing power; and (3) risk is concentrated around execution — readiness in licensing, bandwidth standards, and accreditation will determine whether investments realize projected returns.
Acute Care Telemedicine Services Market
Why this report matters for 2026 planning
- Actionable growth scenarios: We translate the market’s headline CAGR into pragmatic investment pathways tied to specific go-to-market choices (partnerships, build vs. buy, hub configurations), showing the incremental revenues and margin levers executives should prioritize.
- Operational playbooks: Hospital leaders receive implementation-level guidance on staffing models, clinical governance, and technology architecture that de-risk deployment and accelerate time-to-value.
- Regulatory and reimbursement mapping: The research decodes the regulatory landscape and reimbursement trends that will determine cash-flow timing in 2026, enabling accurate financial forecasting and advocacy strategies.
Core market dynamics shaping strategy
- Reimbursement posture: Temporary and permanent policy shifts in the last 24 months have materially affected revenue visibility for acute telemedicine lines. For example, parity provisions for select services through recent physician fee schedule rulings have reduced short-term payer risk, but long-term coverage variability remains a strategic uncertainty for providers and vendors.
- Licensure and interstate practice: Interstate care models increase addressable patient populations but require careful licensure strategies — including participation in compacts or targeted state-by-state licensing — that affect workforce planning and time-to-market.
- Clinical and technical standards: Adoption of minimum bandwidth and video-quality standards is now table stakes for clinical decision support, particularly in time-sensitive acute workflows such as stroke and critical care telemedicine. Investments in reliable connectivity are no longer optional.
- Labor economics: Specialist shortages and competitive demand for acute-care tele-physicians have increased staffing costs materially. Our synthesis of workforce data indicates margin pressure for providers that rely on premium locum or remote specialty staffing without compensating operational efficiencies.
- Accreditation and quality: Accreditation requirements for telehealth programs delivering acute services have emerged as an important gate to payer and system acceptance — programs that embed Joint Commission standards into governance demonstrate faster contracting cycles and lower clinical risk profiles.
Competitive landscape — who moves first, who scales fastest
The acute telemedicine competitive map is a mix of specialist clinical networks, digital platform incumbents, and vertically integrated hospital systems. Market concentration is moderate: the top three players account for a meaningful portion of activity, and the top five increase that share further — a structure that favors both regional specialists and platform-scalers depending on route-to-market.
- Access TeleCare (Dallas, TX) — A rebranded national provider emphasizing 24/7 acute telemedicine across neurology, psychiatry, critical care, hospital medicine, and ED support. The rebrand signals a strategic bet on multi-specialty bundling and enterprise partnerships. Executives should watch how cross-specialty integration is leveraged to increase wallet-share per hospital.
- Eagle Telemedicine (Leawood, KS) — Focused on hospitalist, intensivist, and acute specialist coverage for rural and critical access hospitals. Recent expansion into new partner hospitals reflects an aggressive regional consolidation play in underserved markets where on-site coverage is scarce.
- Avera eCare (Sioux Falls, SD) — Operates a large-scale command-center model delivering ICU oversight, ED support, and inpatient coordination across hundreds of facilities. Its strategic partnerships with regional systems illustrate the commercial viability of a networked command-center approach for rural emergency care.
- Teladoc Health (Purchase, NY) — Leverages an enterprise telehealth platform to deliver acute services including tele-stroke, tele-ICU, and ED physician support. Platform incumbents bring distribution advantages and cross-selling ability to integrated health systems.
- Amwell (Boston, MA) — Offers a hospital-facing Converge platform designed for urgent consultations and hybrid care models. Amwell’s strength lies in integrating vendor-neutral workflows into legacy hospital IT stacks.
- Sound Physicians (Tacoma, WA) — Integrates tele-hospitalist and tele-ICU into comprehensive acute care management programs, positioning telemedicine as an operational tool for bed management and length-of-stay optimization.
Collectively, these players exemplify two distinct strategic archetypes: platform-scale providers competing on technology breadth and contracting leverage, and clinically focused networks winning through specialty depth and tight hospital integration. The top-of-market concentration metrics point to an environment where strategic partnerships and selective M&A will continue to shape national footprints into 2026.
Report contents — what you get (practical, implementation-ready)
Our research is structured to serve executives executing 12–36 month plans. Highlights include:
- Market model and scenarios — A transparent model (2020–2032) with best-, base-, and downside cases tied to reimbursement, licensure, and adoption assumptions. The model allows executives to run sensitivity tests for alternative pricing, staffing, and channel strategies.
- Commercial playbooks — Step-by-step guides for negotiating hospital contracts, structuring shared-savings agreements, and building referral-aligned pricing that accelerates adoption while protecting margins.
- Operational blueprints — Playbooks for hub-and-spoke vs. on-demand delivery designs, clinical staffing templates, credentialing workflows, and bandwidth-redundancy requirements to meet clinical standards and accreditation.
- Vendor and tech evaluation framework — Scorecards and RFP templates to assess platforms on interoperability, latency, security, and clinical workflow fit — enabling procurement teams to compare vendor trade-offs objectively.
- Regulatory & reimbursement tracker — A living matrix mapping state licensure conditions, interstate compact status, and payer reimbursement policies that materially affect rollout timing and revenue recognition.
- Deal pipeline and M&A lens — Strategic scenarios identifying acquisition targets and partnership archetypes to accelerate geographic or specialty expansion, with valuation benchmarks and integration risk assessments.
How to use this intelligence in 2026
- CFOs: Integrate our market scenarios into capital planning and rolling forecasts to avoid under- or over-provisioning for staffing and technology spend.
- Chief Medical Officers and Clinical Operations: Leverage the operational blueprints to reduce clinical onboarding time, achieve accreditation readiness, and tune clinical governance for tele-stroke/tele-ICU workflows.
- Commercial leaders: Use the negotiation playbooks and payer mapping to accelerate contracting cycles and secure parity or bundled-payment arrangements where the economics are strongest.
- Product and Technology leaders: Adopt the vendor-evaluation framework to prioritize investments in low-latency video, interoperability, and security that materially affect clinical acceptance.
What we’re tracking into 2026
- Durability of reimbursement parity and the emergence of service-specific coding guidance.
- Acceleration of interstate licensure reforms and the operational impact of compacts on workforce deployment.
- Capital flows into platforms that can demonstrate demonstrable reductions in length-of-stay and transfer rates for acute populations.
- Strategic partnerships between platform incumbents and regional clinical operators that combine scale with specialty depth.
Next steps — limited preview and full access
This executive brief is designed as a strategic trailer: it highlights the rigor of PW Consulting’s methodology and the practical value of the work without disclosing proprietary segmentation and unit-level forecasts reserved for report subscribers. PW Consulting’s full Acute Care Telemedicine Services Market report contains granular regional and service-line modelling, vendor scorecards, and downloadable financial models for scenario analysis.
For health system executives, payers, and technology investors planning 2026 capital and operating strategies, the full report provides the definitive, execution-oriented intelligence to convert market growth into measurable outcomes. Contact PW Consulting or visit our report page to access the full research package, detailed tables, and the financial model.
For detailed analysis of this topic, please visit the official page: Acute Care Telemedicine Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com