

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cryoablation for Cancer Market Poised for Robust Expansion — Projected 9.42% CAGR

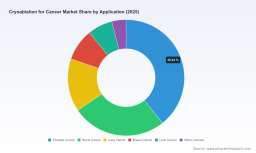
Cryoablation For Cancer Market — Strategic Imperatives for 2026
PW Consulting’s new market study positions cryoablation as one of oncology’s most dynamic device markets entering the mid-2020s. The global market for cryoablation technologies has moved from a niche modality to a mainstream procedural option: our model estimates the market reached approximately USD 475 million in 2025 and, under our central forecast, will expand at a compound annual growth rate (CAGR) of roughly 9.42% through the 2026–2032 horizon, approaching the high hundreds of millions by the end of the period. For executives making strategic choices in 2026—product road‑maps, capital deployment, M&A and market access—this report translates those macro trends into actionable decision levers.
Cryoablation For Cancer Market
Why 2026 is an Inflection Year
-
Regulatory and guideline momentum: Recent approvals and guidance updates have moved cryoablation from investigational to guideline-supported care pathways in select indications, creating a clearer pathway for commercialization and adoption.
Cryoablation For Cancer Market -
Clinical evidence is scaling: Industry sponsors are launching larger post‑marketing and pivotal trials designed to expand indications and to generate the real‑world evidence payors now demand.
Cryoablation For Cancer Market -
Procedural economics and site-of-care shifts: Hospitals and ambulatory surgery centers are re-evaluating capital investments and service mix amid rising technology-driven competition, opening opportunities for devices that demonstrate clear value across episode costs, throughput and patient experience.
-
Technology differentiation: Advances such as multi‑needle cryoablation, improved imaging integration and novel cryogen delivery systems are reshaping competitive advantage from single‑product differentiation to platform-plus-consumables economics.
What PW Consulting’s Report Delivers (Practical, Transaction‑Ready)
-
Proprietary market model with end‑to‑end forecasts (2026–2032) and scenario sensitivity: executives can stress‑test growth by indication, channel and technology adoption curves. Note: full subsegment and regional tables are reserved for subscribers and the full report.
-
Adoption playbooks: step‑by‑step commercialization frameworks for early‑stage innovators and incumbents alike, including center‑of‑excellence rollouts, surgical training programs and bundled‑care approaches.
-
Reimbursement and regulatory roadmaps: mapping coding, coverage and approval strategies across major markets with line‑by‑line guidance for pivotal trial design and post-market evidence generation.
-
Competitive intelligence and M&A scenarios: detailed profiles of incumbent and challenger firms, capability maps, and deal valuation sensitivities keyed to execution risk and reimbursement outcomes.
-
Operational models: CapEx and consumable margin simulations, procurement negotiation templates, and hospital ROI calculators tailored to device, probe and service bundles.
-
Primary research insights: interviews with leading interventional oncologists, hospital procurement officers, and payor medical directors that inform adoption timing and contracting levers.
Competitive Landscape — Strategic Read Across
The cryoablation market is concentrated among a relatively small group of device manufacturers and service providers. The top three vendors account for the majority of market share, and the top five firms exert significant control over product platforms and channel relationships. This concentration creates both entry barriers and strategic windows for focused entrants.
-
Medtronic: A global powerhouse with a broad portfolio and strong distribution reach. Their advantage is platform breadth and hospital relationships; however, incumbency can be a double‑edged sword in markets that prize nimble innovation and lower capital intensity.
-
Boston Scientific (including Galil Medical): Technology leadership in multi‑needle systems and imaging‑integrated solutions positions them strongly in complex ablation cases. Their play emphasizes procedure expansion and integration with interventional oncology suites.
-
IceCure Medical: A paradigm case for how focused clinical and regulatory progress can reshape competitive dynamics. Recent De Novo market authorization for a clearly defined breast cancer population and subsequent trial approvals have accelerated their commercial runway and created a template for indication expansion via robust post‑market evidence.
-
Mid‑market and regional players (CooperSurgical, AtriCure, Erbe, and several specialized probe manufacturers): These companies compete on niche indications, cost structures and service models. Many are attractive targets for bolt‑on acquisitions by larger platforms seeking consumable revenues and differentiated clinical workflows.
Strategic implication: with CR3 and CR5 concentration metrics indicating a market where the top players control a substantial share, new entrants should pursue asymmetric plays—licensing, clinical partnerships, or value‑based pilots—rather than head-to-head platform battles where incumbents can leverage scale.
Regulatory & Reimbursement Developments to Watch
-
Regulatory wins change the conversation: The recent authorization pathway cleared a narrowly‑defined indication for a minimally invasive breast procedure, and the design approval of a multi‑site post‑marketing trial will be a bellwether for broader coverage decisions.
-
Coding is necessary but not sufficient: Procedural codes and HCPCS classification exist for key device elements, but sustainable coverage and favorable payment levels require aggregated clinical and economic evidence demonstrating reduced downstream costs and improved patient outcomes.
Operational Considerations for 2026 Decisions
-
CapEx and procurement strategy: Advanced cryoablation platforms remain capital equipment investments. Health systems are prioritizing technologies that can deliver rapid throughput and recurring consumable revenue; manufacturers must provide flexible acquisition options and predictable service models.
-
Consumables and margin mechanics: Long‑term revenue from probes and disposables will increasingly determine device economics. Firms should model consumable replacement cycles, single‑use vs reusable tradeoffs, and contracting strategies aligned to total cost of care.
-
Clinical evidence and adoption curve: Pivotal and post‑market trials should be designed to support both label expansion and value‑based contracting. Early investment in registry and RWE platforms will accelerate coverage negotiations.
-
Channel and training: Successful rollouts will combine proceduralist training, proctor networks and integrated imaging partners to lower adoption friction.
Five Immediate Strategic Moves for Executives in 2026
-
Prioritize evidence that unlocks coverage: Identify the minimum dataset payors require to move from limited to routine coverage and invest in the trials or registries that produce it.
-
Lock down consumable economics early: Design probe pricing and channel contracts to protect margins while enabling rapid procedural scale in high‑value sites of care.
-
Explore targeted M&A: For incumbents, prioritize tuck‑ins that add consumables, imaging integration or indication‑specific IP; for challengers, seek distribution partnerships to accelerate scale without disproportionate capex burden.
-
Deploy flexible acquisition models: Offer hospitals capex-light alternatives—leasing, pay‑per‑procedure or hybrid service contracts—to overcome procurement cycles and budget constraints.
-
Operationalize an outcomes narrative: Build a measurable clinical and economic story (through pilot programs) that links cryoablation to improved throughput, lower complication rates and measurable patient‑reported outcomes.
How the Report Supports 2026 Decision‑Making
This study is structured to support corporate strategy, commercial execution and transaction diligence. Clients receive the market model with scenario toggles, a prioritized list of target hospitals and key opinion leaders for pilot programs, a reimbursement playbook and detailed competitor intelligence. Critically, the report is designed to be actionable within 60–90 days—supporting near‑term commercial pilots, regulatory planning, or M&A diligence.
PW Consulting’s analysis blends quantitative forecasting with qualitative, operational insights. We combine a proprietary financial model with primary interviews across payors, providers and industry executives so that the recommendations are grounded in real execution constraints—not just top‑down projections.
Next Steps
For a deeper read—including the full regional and indication splits, company profiles with revenue estimates, detailed cost models and downloadable Excel scenarios—visit the PW Consulting report page to access the complete Cryoablation For Cancer Market study. The full report contains the segment granularity and data exports necessary for valuation work, business planning and negotiation strategy.
In a market where clinical validation, reimbursement traction and platform economics converge, 2026 will be the year when strategic choices made by product, commercial and M&A leaders determine who captures the next wave of adoption. PW Consulting’s report is designed to make those choices clearer, faster and more defensible.
For detailed analysis of this topic, please visit the official page: Cryoablation For Cancer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com