

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Carpal Tunnel Syndrome Treatment Market to Grow at a 6.12% CAGR Through 2026–2032

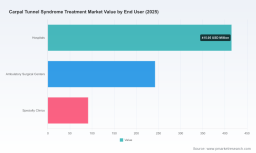
PW Consulting Strategic Brief: Carpal Tunnel Syndrome Treatment Market — A 2026 Decision Framework
PW Consulting today publishes a focused strategic brief to accompany our full market research report on the global Carpal Tunnel Syndrome (CTS) treatment market. With the market estimated at approximately USD 748.6 Million in 2025 and projected to grow to about USD 1.13 Billion by 2032, at a compound annual growth rate (CAGR) of 6.12% over the 2026–2032 forecast window, 2026 represents an inflection year for clinical practice, reimbursement, and commercial strategy. This briefing highlights the report’s practical value for executives, investors, clinicians, and health system leaders who must make near-term choices that determine competitive positioning through the next growth cycle.
Carpal Tunnel Syndrome Treatment Market
Why 2026 Is a Strategic Inflection Point
-
Reimbursement and coding dynamics are reshaping commercial economics. The introduction of a Category I CPT code for percutaneous carpal tunnel decompression effective January 1, 2026, and the corresponding procedural coding developments for endoscopic options alter revenue capture and site-of-service calculus for manufacturers and providers. The code’s 0‑day global period and day-of-service valuation create immediate implications for ambulatory settings and bundled-care models.
Carpal Tunnel Syndrome Treatment Market -
Regulatory and evidence milestones are accelerating technology adoption. Between late‑2024 and early‑2026 we have seen multiple 510(k) clearances for novel percutaneous and endoscopic systems, and the publication of independent reviews supporting ultrasound‑guided carpal tunnel release (UGCTR). These developments materially lower adoption friction for minimally invasive, image‑guided treatments and create new categories of clinical evidence that payers will weigh.
Carpal Tunnel Syndrome Treatment Market -
Diagnostic and point‑of‑care innovations (handheld ultrasound with AI nerve assessment) are compressing diagnostic-to-treatment timelines. FDA clearance of automated median nerve ultrasound tools signals a move toward office‑based triage and treatment pathways that can shift volumes away from traditional operating rooms.
-
Heightened regulatory scrutiny of unvalidated modality claims underscores the need for disciplined clinical and regulatory strategy. Recent enforcement actions against devices marketed with unsupported therapeutic claims demonstrate the risk of reputational and commercial setback when evidence gaps persist.
What PW Consulting’s Full Report Delivers (Practical, Actionable)
Our report is built as an operational playbook for 2026 decision‑making rather than a purely academic exercise. Key deliverables include:
- Market sizing and forward-looking scenario forecasts with three adoption trajectories (base, conservative, accelerated) across the 2026–2032 horizon.
- A reimbursement matrix mapping new CPT and payer coding impacts, site-of-service economics, and billing considerations for percutaneous, endoscopic and non‑surgical pathways.
- Regulatory pathway mapping for device, diagnostic and combination product strategies — including required clinical endpoints and pragmatic study designs that de‑risk market entry.
- Commercial archetypes and go‑to‑market playbooks tailored to hospitals, ambulatory surgical centers, and specialty clinic channels, with recommended sales motions, KOL engagement plans, and pricing frameworks.
- Vendor benchmarking and capability heatmaps assessing technology, clinical evidence, commercialization reach, and partnership fit for M&A or alliance diligence.
- Implementation tools: HCP adoption curve models, cost‑benefit calculators for hospital and ASC decision‑makers, pilot design templates, and KPI dashboards for monitoring uptake.
- M&A screening criteria and an acquisition heatmap identifying strategic targets across device, imaging/AI, and services segments.
Competitive Landscape — Strategic Implications for Market Players
The CTS treatment market today sits at the intersection of established surgical incumbents and a new wave of minimally invasive, image‑guided entrants. Incumbent orthopedics and surgical systems firms continue to offer proven endoscopic and open surgical platforms that dominate established hospital pathways. At the same time, smaller, specialized device companies and diagnostic vendors are pushing the clinical envelope with ultrasound‑guided percutaneous systems and AI‑enabled handheld imaging that enable office‑based workflows.
-
Large device manufacturers — firms with broad orthopedic and hand‑surgery portfolios retain advantages in distribution, surgeon relationships, and integrated instrument ecosystems. Their strategic choices will determine whether they extend into office and ASC channels through product line extensions, new service models, or partnerships with imaging/AI vendors.
-
Specialist innovators — companies commercializing ultrasound‑guided release devices and percutaneous systems are redefining the value proposition of minimal invasiveness, lower facility requirements, faster recovery, and potentially differentiated reimbursement. Regulatory clearances and independent publications supporting these modalities represent important inflection points for commercial scaling.
-
Diagnostic/AI entrants — handheld ultrasound and automated nerve assessment tools are lowering the logistical barriers to diagnosis and creating new data flows that can be monetized through bundled clinical pathways or integrated vendor solutions.
-
Commercial dynamics — expect intensified partnership activity (device + imaging + services), selective consolidation, and competitive moves to secure early ASC adoption. Pricing pressures will emerge as percutaneous and office treatments mature and payers refine coverage criteria under the new coding landscape.
Key players profiled in the report include global orthopedics and surgical device companies known for endoscopic and minimally invasive instruments, as well as focused innovators advancing ultrasound guidance and percutaneous technologies. Our competitive assessment synthesizes product positioning, recent regulatory milestones, evidence generation status, and channel strength to identify likely winners and the critical gaps they must close.
Recent Developments Shaping 2026 Strategies
- Regulatory clearances in 2024–2025 for image‑guided and endoscopic systems have broadened the menu of minimally invasive options and paved the way for broader outpatient adoption.
- Independent clinical publications in 2026 supporting ultrasound‑guided release add robustness to the evidence base that payers and health systems will evaluate.
- Diagnostic AI clearances for median nerve assessment accelerate office triage workflows and create adjacencies for device vendors.
- Regulatory enforcement actions regarding unsupported therapeutic claims highlight the need for rigorous clinical governance and compliant commercial messaging.
Recommendations — What Manufacturers, Investors, and Providers Should Do in 2026
-
Manufacturers: Prioritize clinical evidence that aligns with payer and system decision criteria (comparative effectiveness vs. standard surgical approaches, real‑world outcomes in ASC/office settings). Build reimbursement playbooks tied to the new CPT landscape and pilot bundled care offerings with high-volume ASC partners.
-
Investors: Focus diligence on companies with defensible evidence-generation plans, direct access to ASC networks, and partnerships with diagnostic/AI providers. Look for capital-efficient pathways to commercialization that minimize large randomized trials while delivering meaningful outcomes data.
-
Providers and Health Systems: Evaluate near‑term pilots for percutaneous and ultrasound‑guided workflows that can lower cost-per-case and improve throughput. Require robust post‑market data collection and harmonize credentialing pathways to reduce adoption friction.
-
Payers: Define coverage pathways that reward documented outcomes and efficiency gains, and engage early with manufacturers on registry designs that generate longitudinal value data.
How to Use the Report to Make 2026 Decisions
PW Consulting’s full report is structured as an executable roadmap. For executives needing rapid orientation, the report’s “90‑day sprint” checklist identifies immediate actions (regulatory filings, payer engagement, pilot site selection). The 12–24 month operational plan aligns evidence generation, commercial deployment, and partnership development to capture the fastest routes to sustainable adoption. For M&A teams, the vendor heatmap and financial scenario models isolate targets that deliver complementary clinical capability or ASC access.
About the Methodology and Data Transparency
The report combines primary interviews with clinicians, payers, and procurement leaders; proprietary patient and provider utilization models; and a bottom‑up commercial analysis to produce the market sizing and forecast. While this briefing highlights high‑level market scale and growth (2020–2025 historical trajectory and the 2026–2032 projection), the full report contains the granular segmentation, channel economics, and downloadable datasets required for transaction diligence and operational planning.
Next Steps
PW Consulting’s CTS treatment market brief is a strategic primer for 2026. We intentionally provide depth of insight while reserving detailed segment tables, regional splits, and company-level revenue breakdowns for the full report and datasuite. For access to the complete analysis, bespoke briefings, or to commission focused market due diligence, please visit our report page or contact PW Consulting’s strategic advisory team.
For detailed analysis of this topic, please visit the official page: Carpal Tunnel Syndrome Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com