

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 6.8% CAGR for Selective Soldering Equipment Market (2026–2032): From USD 582.1M in 2025 to USD 922.6M by 2032 — Asia Pacific, In‑line Systems & Automotive Electronics Lead; Top‑5 Hold 64.2%

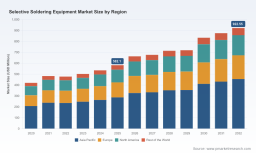
Selective Soldering Equipment Market — PW Consulting 2026 Strategic Brief
PW Consulting’s latest Selective Soldering Equipment Market report frames the near-term competitive landscape and delivers an actionable strategic playbook for procurement, operations, and M&A decisions in 2026. Our baseline sizing shows a market that expanded from approximately USD 420.15 Million in 2020 to USD 582.1 Million in 2025, and that is forecast to grow at a compound annual growth rate (CAGR) of 6.8% through our projection window (2026–2032), reaching an estimated USD 922.55 Million by 2032. These headline metrics speak to steady, technology-driven demand — but the strategic value of the report lies in the operational intelligence, vendor benchmarking, and scenario-ready recommendation sets that translate that growth into executable choices.
Selective Soldering Equipment Market
Why 2026 Is an Inflection Year
-
Technology convergence: The combination of PCB miniaturization, lead-free solder mandates, and mixed-technology assemblies is accelerating selective soldering adoption where precision and thermal control matter most. Adoption is no longer an option for high-reliability assemblies — it is a supply chain requirement.
Selective Soldering Equipment Market -
End-market dynamics: Electrification (notably in vehicle electrics and ADAS modules), industrial automation, and high-reliability consumer/medical devices are collectively driving higher-value unit demand for selective solutions. Manufacturers face a choice in 2026: accelerate investment to capture volume and quality gains, or accept longer qualification cycles and potential yield penalties.
Selective Soldering Equipment Market -
Regulatory & quality drivers: Standards such as IPC-A-610 are tightening expectations around voiding and joint integrity in critical end-markets. Selective soldering is increasingly positioned as the process of record to meet these thresholds for aerospace, automotive, and medical electronics.
What the Report Delivers — Practical, Transaction-Ready Content
This release intentionally previews the report’s operational depth while withholding granular segment tables to protect our proprietary analysis. The full report is highly pragmatic; it is built for decisions, not just insight. Highlights include:
-
Market sizing & trend drivers: Year-by-year historical and forecast revenue series (2020–2032) with transparent assumptions, scenario sensitivity for demand shocks, and a clear explanation of the 6.8% CAGR drivers.
-
Capital planning tools: CAPEX phasing templates and TCO calculators that let manufacturers model purchase vs. lease, utility and nitrogen consumption, planned throughput, and depreciation schedules.
-
Operational metrics and benchmarking: Benchmarked throughput, mean time between failures (MTBF) expectations, and service-cost buckets to support supplier negotiations and maintenance contract design.
-
Competitive heatmaps & supplier scorecards: Relative positioning by product architecture (modular in-line platforms, standalone/batch systems, robotic mini-wave solutions), engineering differentiation, aftermarket reach, and channel footprint.
-
Technology roadmap & upgrade pathways: Roadmaps for electromagnetic pumps, multi-nozzle architectures, and dual-pot inline configurations, paired with upgrade-impact analyses for throughput and yield.
-
Procurement playbooks: Decision matrices for use-case prioritization (prototype to high-volume production), risk-adjusted supplier checklists, and sample bid evaluation templates.
-
Regulatory and materials linkage: Mapping of process selection to compliance outcomes, with linkage to solder flux market trends and cost exposure across the value chain.
Key Market Signals and Raw-Material Context
Two cross-cutting inputs materially affect equipment selection and life-cycle economics. First, the upstream solder flux and process-chemicals complex remains a meaningful cost and technical constraint: analysts place the solder flux market in the multi-billion-dollar range as of 2025, with projected growth through the next decade. Second, process-efficiency differentials are non-trivial — selective soldering can produce dramatically lower consumable usage and reduced nitrogen demand versus legacy wave soldering approaches, an important lever when modeling operating expenditure.
Competitive Landscape — Who Matters and Why
The selective soldering supplier field is a mix of global OEMs, regional specialists, and value-focused challengers. Market concentration statistics indicate a moderately concentrated supply base, reflecting the presence of large established players and room for specialized entrants. That dynamic creates disciplined pricing advantages for market leaders while leaving strategic niches open to differentiated technologies and service models.
-
Kurtz Ersa GmbH (Germany) — A global leader with modular VERSAFLOW and ECOSELECT platforms spanning entry-level to high-volume needs; known for electromagnetic pump technology and multi-nozzle configurations. Recent product introductions and trade-show activity in early 2026 signal a push on throughput and integration across reflow/rework lines.
-
Nordson SELECT (United States) — Offers a full spectrum from standalone to multi-station inline systems and is supported by a broad global service network; strong aftermarket and installation capabilities make it a common choice for multinational manufacturers seeking consistent performance across sites.
-
SEHO Systems GmbH (Germany) — Focused on productivity through integrated fluxing, preheating and soldering zones; well-regarded for systems optimized around throughput and process repeatability.
-
Pillarhouse International Ltd (United Kingdom) — The technology pioneer with deep IP in selective soldering; relevant for firms prioritizing engineering pedigree and patented innovations.
-
JUKI Corporation (Japan) — Offers reliable batch-platform solutions and remains a staple for through-hole-heavy production profiles and legacy continuity.
-
Apollo Seiko (Japan) — Expanding inline portfolios and dual-pot innovations; recent trade-show showcases underline a strategic push into higher-throughput segments.
-
DDM Novastar, RPS Automation, TM Soldering Solutions, INERTEC, VennTek-SASinno, Hentec Industries — A mix of cost-competitive and niche-capability providers that are relevant for short-to-medium production runs, select regional markets, and specialized process capabilities (mini-wave, precision nozzle control, legacy-system support).
Recent vendor activity in late 2025 and early 2026 — including product launches and North American market expansion initiatives — confirms that suppliers are competing on throughput, service coverage, and platform modularity rather than purely on price. For buyers, this elevates the importance of total-cost-of-ownership and multi-site standardization when selecting partners.
Strategic Imperatives for 2026 Decision-Makers
-
Adopt a two-track procurement strategy: pilot modular/inline solutions for high-growth product lines while retaining flexible standalone systems for low-mix, high-reliability assemblies.
-
Integrate TCO modeling into capital approval: include energy, nitrogen usage, consumables, downtime costs, and service SLAs. Small differences in operating parameters materially shift ROI horizons.
-
Prioritize suppliers with demonstrable global service footprints if you operate multi-site manufacturing; local uptime and consumables logistics can dominate lifetime cost for a system.
-
Use staged rollouts to defray qualification risk: qualify new platforms on non-critical product lines before scaling to mission-critical modules for automotive, aerospace or medical uses.
-
Monitor raw-material and process-chemical dynamics: solder flux pricing and availability influence operating budgets; the report includes approaches to hedge or mitigate supplier exposure.
-
Embed compliance metrics into procurement specs: require vendors to provide process evidence aligned with IPC-A-610 thresholds and voiding-performance data as part of acceptance testing.
How PW Consulting Builds Confidence in 2026 Decisions
Our methodology combines primary interviews with OEMs and end-users, equipment shipment and booking analysis, buy/sell-side capex tracking, and bottom-up process modeling calibrated to market activity between 2020–2025 (base year 2025). We apply scenario stress-testing across demand shocks, supply-chain interruptions, and raw-material volatility to produce a spectrum of outcomes rather than a single point forecast. The result is a set of decision-ready recommendations, procurement templates, and technology roadmaps you can operationalize in 30–120 days.
What We Are Deliberately Not Releasing Here
To preserve the strategic value of the complete study, we have intentionally omitted granular regional shares, application-by-application percentages, and specific revenue splits across subsegments in this release. The full report contains those tables, supplier-by-supplier revenue breakdowns, and downloadable excel models that allow you to tailor projections to your specific factory footprint and product mix.
Next Steps
For manufacturers, OEMs, component distributors, and investors looking to convert the 6.8% CAGR and the underlying market momentum into competitive advantage, PW Consulting’s full Selective Soldering Equipment Market report provides the operational tools and vendor intelligence required to act in 2026. The report is designed to be used directly by capital planners, process engineers, and sourcing teams to accelerate purchasing cycles, strengthen supplier negotiations, and reduce qualification time-to-value.
Access the full report, interactive models, and supplier scorecards on PW Consulting’s publication page or contact your PW Consulting account lead to schedule a briefing and scenario workshop tailored to your organization’s footprint and program priorities.
For detailed analysis of this topic, please visit the official page: Selective Soldering Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com